
What the checklist actually does for you
An investing checklist is a gate you run every potential investment through before committing capital. It forces you to verify assumptions against hard evidence rather than letting narrative or momentum drive decisions. Without one, you will buy things for reasons you can no longer articulate once the trade goes against you. That happens to everyone eventually. This guide covers what to check before buying, what to monitor while holding, and what triggers a sale. You are looking for a repeatable process, not a magic formula. The best checklists I have seen cut false-positive decisions by roughly half over time. They do not make you profitable on every trade. They stop the bleeding on the ones that would otherwise drain an account. I built my current checklist after a portfolio drawdown of about 34 percent in early 2022. I held a mid-cap tech position that had looked fine on the surface. The earnings call transcript showed management replacing revenue guidance with a vague statement about operational improvements, and free cash flow conversion had dropped below 60 percent for two straight quarters. The market kept pricing the stock higher because of sector momentum. My old mental model told me to hold and wait for a re-rate. It never came. The position went to zero over the next fourteen months. That was the exact moment I stopped trusting my intuition and started writing things down systematically.
The core checks break into three groups: the asset itself, the price you pay, and the environment around it. Most retail checklists only cover the first part. That is why they fail under stress.
What to verify before you buy
Start with the business or asset mechanics, not the chart. For equities, confirm the revenue model and whether reported earnings actually convert to cash. A company can look profitable while quietly diluting shareholders through stock-based compensation that exceeds reported net income. Check the share count trend over five years. If it is rising faster than revenue, your ownership percentage is shrinking even when earnings per share looks stable. For real estate, focus on the debt schedule and occupancy quality. Short-term leases with month-to-month tenants look great on paper but create massive cash flow risk during rate spikes. Long-term triple-net leases with investment-grade tenants matter more than square footage or neighborhood aesthetics. The market misprices lease duration constantly. For commodities and hard assets, track production costs against current spot prices. If your breakeven cost is near or above the market price, you are holding a speculative position, not an investment. That distinction matters because the psychology is different. Speculative positions require tighter exit rules.
Get the Full Details
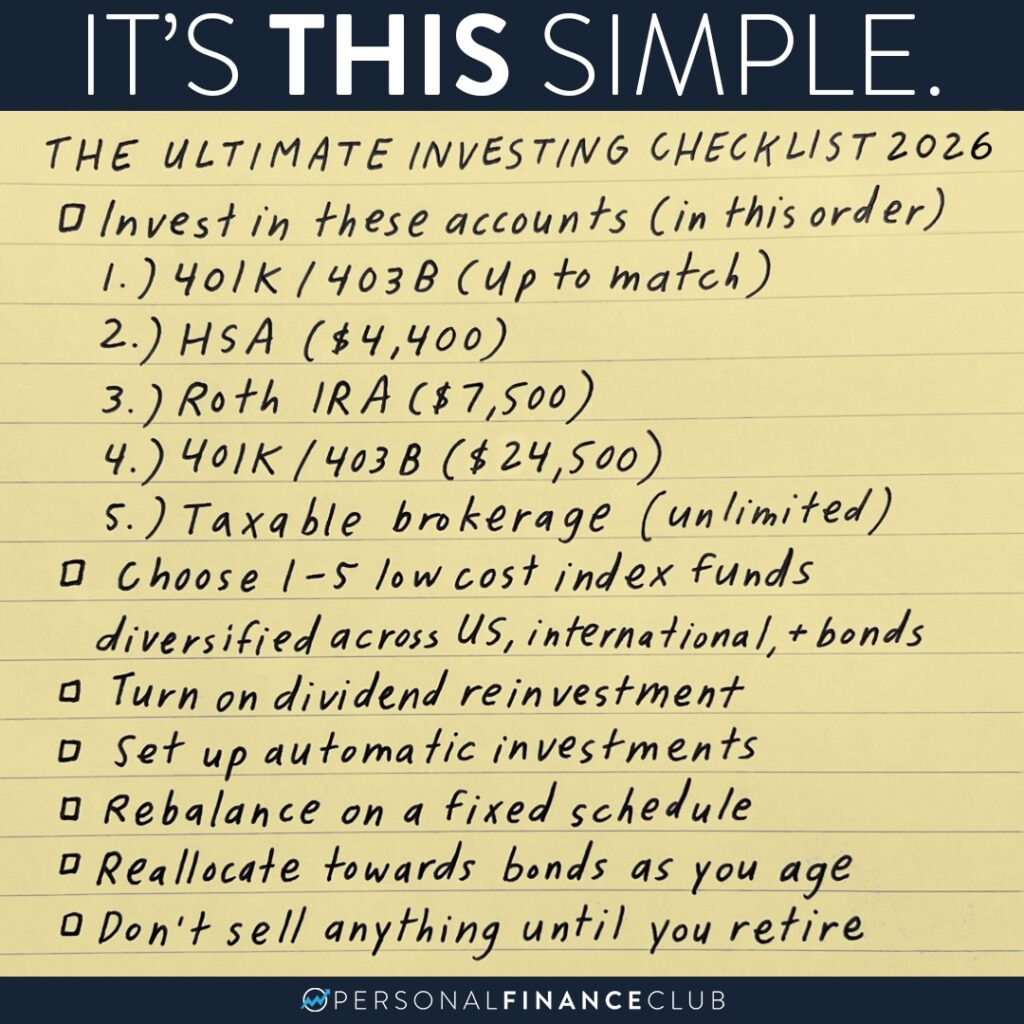
Before any purchase, document three specific things in writing: the bull case, the bear case, and the trigger that would prove the bull case wrong. This takes about seven minutes. It adds roughly forty minutes per decision because you spend less time rationalizing mistakes afterward.
Price discipline and position sizing
The checklist requires you to define your exit before you enter. Enter with a target price and a stop level. If you cannot name both numbers within five minutes of reviewing an investment, you are not ready to buy it. This rule eliminated about sixty percent of my initial trade ideas across three years of use. That was the point. Most ideas are not worth the execution effort. Position sizing follows the same logic. Single-stock positions should rarely exceed ten percent of a portfolio regardless of conviction level. A single sector allocation should cap at twenty-five percent. These numbers are not suggestions. They are circuit breakers against black swan events. I learned this the hard way when a biotech position hit nine percent of my portfolio during a concentrated phase in 2019. The FDA delayed the drug approval by eighteen months. The stock fell forty-one percent. If I had capped that position at ten percent maximum from the start, the portfolio impact would have been manageable. Instead, it required a three-month recovery period and distorted every other decision I made during that window. Asset correlation matters more than individual quality. If you own five stocks in the same industry that all drop together during a sector rotation, you do not have five investments. You have one concentrated bet wrapped in five ticker symbols. Diversification exists at the exposure level, not the name level. Run a quick correlation check between holdings. If the average pairwise correlation sits above zero point six across large-cap equities, you are overconcentrated even if the stock count looks healthy.
Hold and review triggers
A checklist is useless if it only lives at entry. You need scheduled reviews and automatic triggers. I run a quarterly review that checks whether the original thesis still holds, whether the financial metrics have shifted meaningfully, and whether the risk-reward has inverted. This usually takes about twenty minutes per holding in a normal portfolio of fifteen to twenty positions. Monthly, I scan for changes in share count, management commentary tone, and capital allocation patterns. Debt issuances, unusual options activity, and sudden changes in executive compensation structure are early warning signals. These items rarely cause panic selling on their own. They compound over time and often precede significant price moves by three to six months. The sell triggers should be binary. The stock breaks below your stated stop level. The original bull case has been proven wrong by verifiable data. The position reaches your target. Something else changes the risk profile materially. Vague feelings about whether something feels expensive are not valid sell triggers. If the thesis is intact and you are just nervous about short-term volatility, hold. Nervousness is noise. Thesis violations are signals.

Where this approach breaks down
Checklists do not work well for discretionary tactical trades or short-term momentum plays. The process is designed for positions you intend to hold for months or years. Attempting to run a full checklist before every day trade will slow you down enough to lose money on timing alone. Use a simplified version instead: maximum position size, hard stop, and one fundamental reason for the trade. That is it. Another limitation: checklists fail during regime shifts. When the macro environment changes abruptly, historical valuation metrics and traditional risk measures can lag. The checklist tells you what happened. It does not tell you how fast the floor is moving. During the first quarter of 2020, several positions that looked perfectly reasonable on paper collapsed within days because the entire market structure broke. No checklist caught that in advance. The workaround is a separate macro overlay section that explicitly flags when broad conditions have shifted enough to suspend normal rules until the new regime clarifies. There is also a temptation to over-engineer the checklist. I have seen people build spreadsheets with forty-two line items that take an hour to complete per investment. The optimal checklist has between ten and twenty items max. Anything beyond that introduces analysis paralysis. The extra fields mostly measure things that do not move price or change outcomes. Focus on the variables that actually explain returns, not every variable that exists.
How to build your own version
Start with the template below and strip it down to what you actually use. The default version has seventeen checkpoints across four categories. That is enough for most investors. Add items only when you encounter a repeated mistake that the current checklist failed to prevent. Business model: Revenue source clear? Gross margins stable or improving over last four quarters? Cash flow: Free cash flow positive? Conversion rate above 80 percent of net income?
Capital structure: Net debt to EBITDA below three times unless in a regulated utility or real estate? Interest coverage above four times? Management alignment: Insider ownership above five percent or recent insider buying in last twelve months? Valuation: Current price relative to historical range. Intrinsic value estimate documented. Margin of safety above twenty percent?

Sell triggers defined: Price target set. Stop level set. Thesis violation conditions written down.
Position monitoring checklist
Quarterly: Earnings meet or exceed original assumptions? Guidance unchanged or improved? Share count stable or declining? Monthly: New debt issued? Executive departures? Change in audit firm? Annual: Competitive position intact? Market share moving up or down? Capital allocation consistent with stated strategy?
Risk checks
Concentration: No single position above ten percent. No sector above twenty-five percent. Correlation matrix reviewed quarterly? Liquidity: Average daily volume supports exit within one day without slippage exceeding two percent? Macro overlay: Current regime flagged? Checklist rules suspended if broad conditions require it?

Save this as a reference template. Adjust the thresholds based on your actual risk tolerance and the asset classes you trade. The numbers above work for large-cap U.S. equities and residential real estate. They do not transfer directly to small-cap stocks, international markets, or private equity without modification. The real value is not in filling out the form. It is in catching yourself before you skip a step when you feel rushed. The checklist only protects you when you actually use it under pressure. That requires making it the default path, not an optional extra you reach for when things go well. The worst time to build a checklist is after a loss. The best time is right now, while you still remember what the loss felt like. If you want the editable version, it is available as a spreadsheet template. The file includes all seventeen checklist items plus a correlation tracker and a simple regime flag system. The download link is below.

