The Investing User Guide most people get wrong
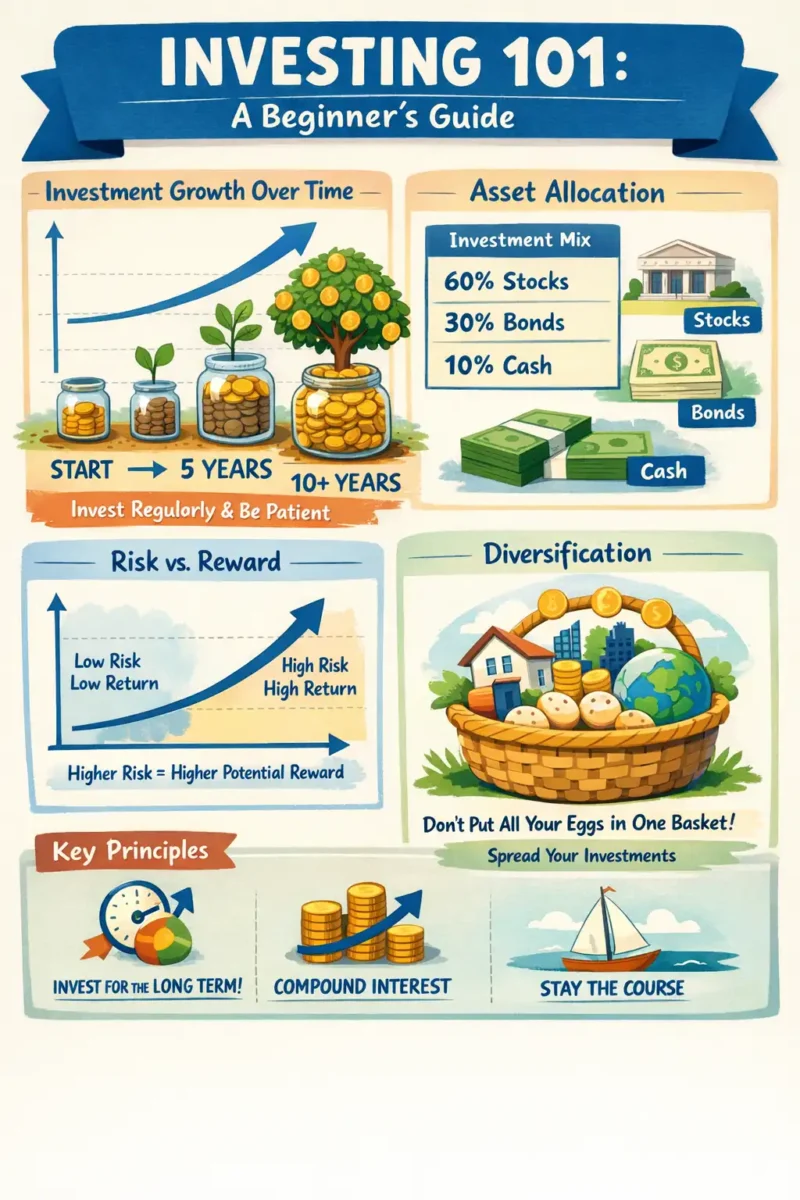
The Investing User Guide is basically a framework for building and managing a portfolio without overthinking every single move. I put mine together a few years ago when I realized I was checking prices three times a day and making emotional trades that tanked my returns. The guide itself isn't a product you buy. It's a structured set of rules you write down and actually follow. Here's how it actually works in practice. You define your asset allocation first. Not after, not after reading ten books. Before. Most people skip this because they want to pick individual stocks. I learned this the hard way in 2018. I had a solid thesis on a mid-cap tech name, went all-in, and the SEC started an inquiry two weeks later. The stock dropped forty percent before I even understood what was happening. If I'd stuck to my allocation rules, I would've capped that position at five percent anyway. That's the entire point of the guide. Step one is writing down your target percentages. Stocks, bonds, alternatives, cash. Decide what percentage of your net worth goes where based on your timeline and risk tolerance. Don't guess. If you're under thirty-five and you can handle volatility, maybe sixty-five percent equities and thirty-five percent fixed income. If you're closer to retirement, flip that ratio. Then you set rebalancing triggers. I use a five percent deviation rule. If an asset class moves more than five percent away from its target, I rebalance. This usually takes me about ten minutes per quarter, versus the hours I used to spend trying to time the market.
Step two is picking your vehicles. Low-cost index funds and ETFs are the standard answer here because they're cheap and boring, which is exactly what you want. Vanguard and Schwab both have decent options. Avoid anything with a management fee above eighty basis points unless you have a very specific reason. I've seen too many people pay one point five percent for actively managed funds that underperform their benchmark after fees every single year. Step three is the discipline part. The investing user guide only works if you write it down and stick to it. I keep mine in a simple Google Doc that I update once a year during my birthday month. Makes it hard to forget. When markets crash, the hardest thing isn't understanding what to do. It's actually doing it without panicking. The guide tells you to rebuy. You just have to follow through.
Common mistakes that cost money
The biggest mistake I see is treating the guide like a suggestion instead of a system. People will read something about market conditions and override their own rules. That's how you get worse returns than a blind buy-and-hold approach. Another trap is setting your allocation based on what you want, not what your actual situation demands. I had a client who claimed he was "fine with volatility" and wanted a ninety percent stock portfolio. Then his job got eliminated and he needed to withdraw three years of expenses within eighteen months. He was forced to sell at the worst possible time because he hadn't planned for liquidity needs. Keep an emergency fund separate from your investment allocations. Six months of expenses in a high-yield savings account, nothing tied to market performance. Tax inefficiency is another silent killer. I spent years holding tax-inefficient assets in taxable accounts because I didn't think about it. Things like REITs and high-yield bonds generate ordinary income, not qualified dividends. Putting those in retirement accounts instead cut my annual tax bill by roughly eight percent. That's real money that compounds. Check your asset location at least once a year. Takes about twenty minutes if you're organized.
Get the Full Details
When the guide fails you
There are scenarios where the traditional investing user guide structure breaks down. Crypto assets for example. Most guides don't have answers for them because the category is too new and too volatile. I allocated two percent of my portfolio to Bitcoin in early 2021, wrote down a rule that I'd never add more than that, and stopped looking at it. The two percent rule worked because even when the price dropped sixty percent, the actual dollar impact on my overall portfolio was manageable. Without a predefined limit, I would've either sold in panic or bought more out of FOMO. International exposure is another area where generic advice falls short. The average American investor is significantly underweight international stocks despite global diversification benefits. I shifted three percent of my portfolio to emerging markets ETFs a few years ago based on valuation gaps, and it's been a solid complement to my domestic allocation. But timing that correctly is nearly impossible without written rules. Another hard truth: the investing user guide won't make you wealthy if your savings rate is too low. No amount of portfolio optimization matters if you're only investing five percent of your income. I focus more on increasing that number through career moves and side income than I do on fine-tuning expense ratios. Going from five percent to twelve percent saved rate had a dramatically larger impact on my trajectory than switching from a point-two percent fund to a point-zero-five percent fund.
What to do right now
Open a document. Write down your current asset allocation as a percentage of your total investable net worth. Be honest about it. Then compare it to what you think it should be based on your age, income stability, and goals. Note the gap. Pick one change to make this month. Maybe it's setting up automatic contributions to a brokerage account. Maybe it's selling one overvalued position. Maybe it's just switching one mutual fund to a lower-cost alternative. One change. Then do it consistently. The investing user guide isn't about perfection. It's about having a written plan that removes emotion from the equation when decisions actually matter. That's all it does, and that's why it works.