Why Most People Skip the Foundation (And Lose Money)
I spent six years managing my own portfolio before I realized I was doing everything backwards. I jumped into index funds, read a couple of articles about asset allocation, and started buying ETFs without ever writing down what I was actually trying to achieve or how I measured progress. The result was predictable: mediocre returns, high anxiety, and a lot of unnecessary trading. The Investing User Guide Roadmap is just a structured way of forcing yourself to think clearly before you risk capital. It sounds obvious, but most people skip it. I learned that lesson the hard way after losing about fourteen percent of my portfolio in a single quarter because I had no framework for when to hold, when to trim, or when to cut losses.
What the Investing User Guide Roadmap Actually Is
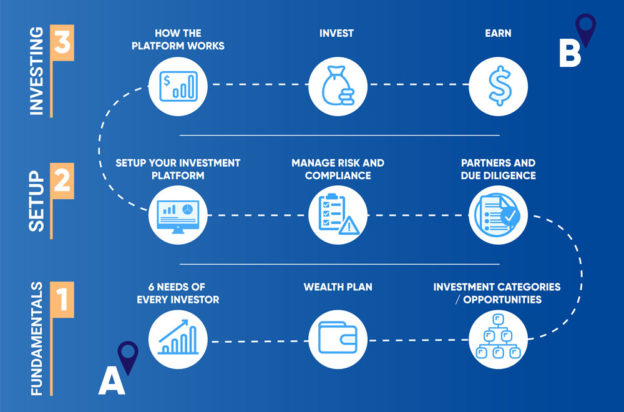
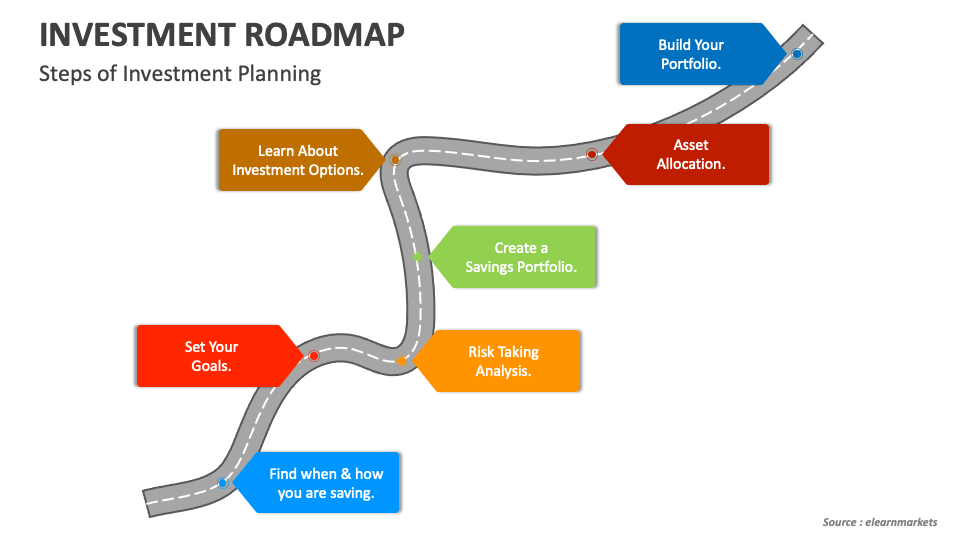
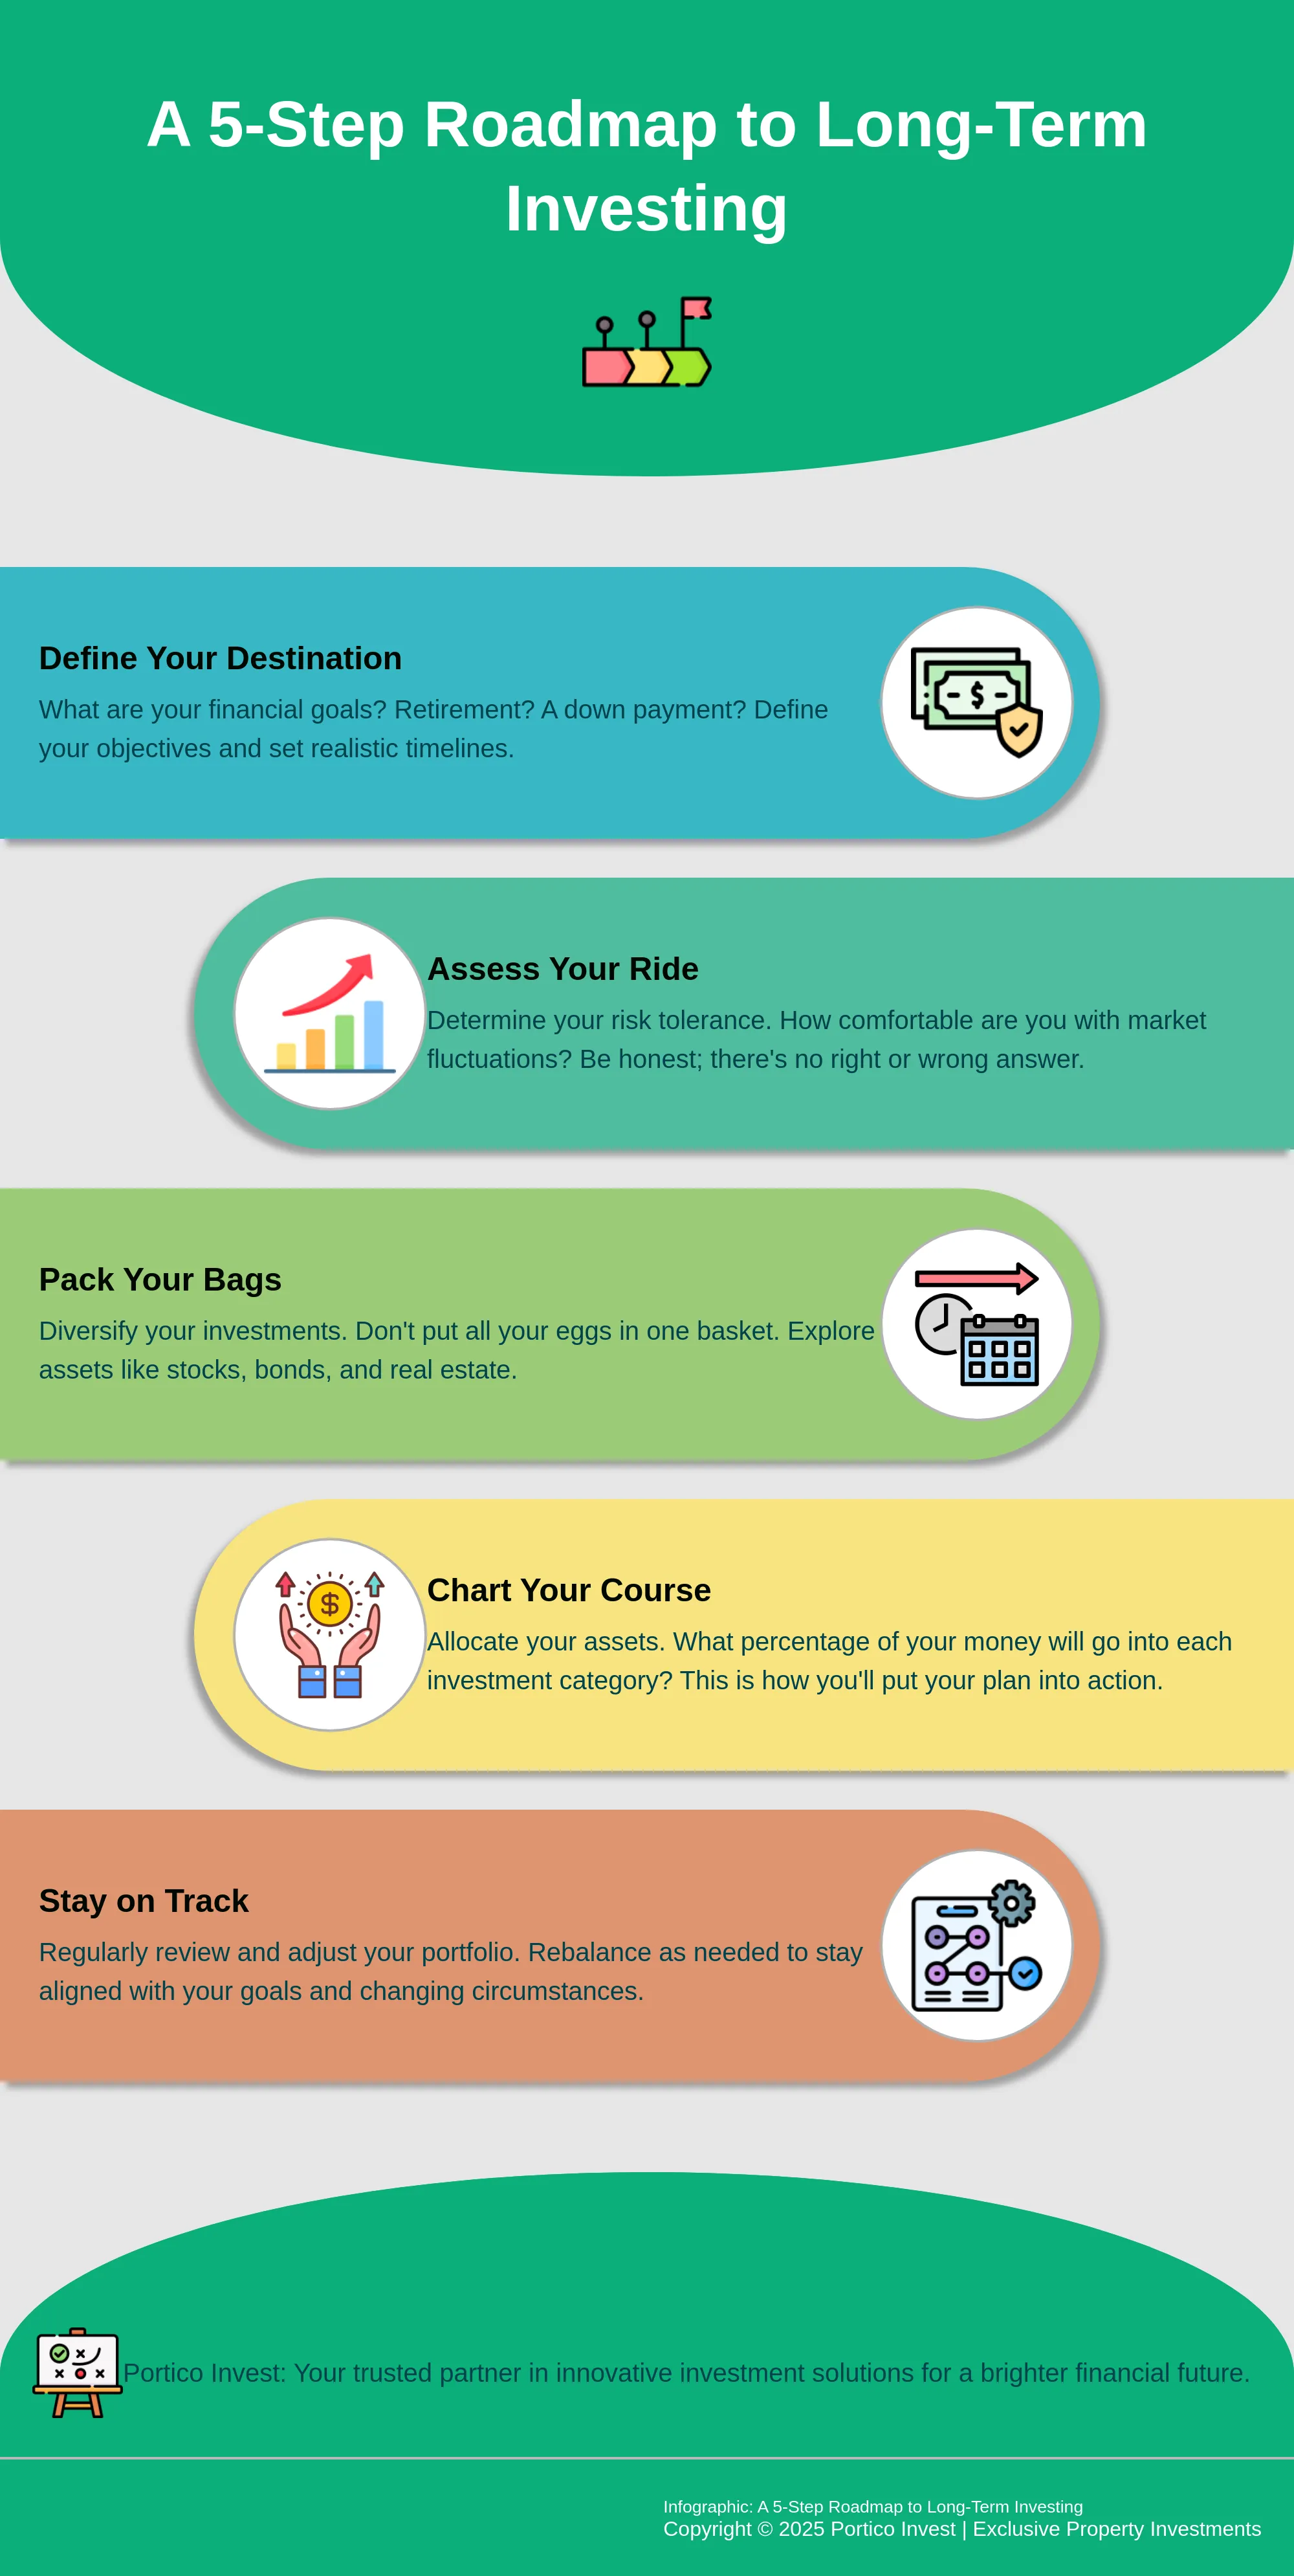
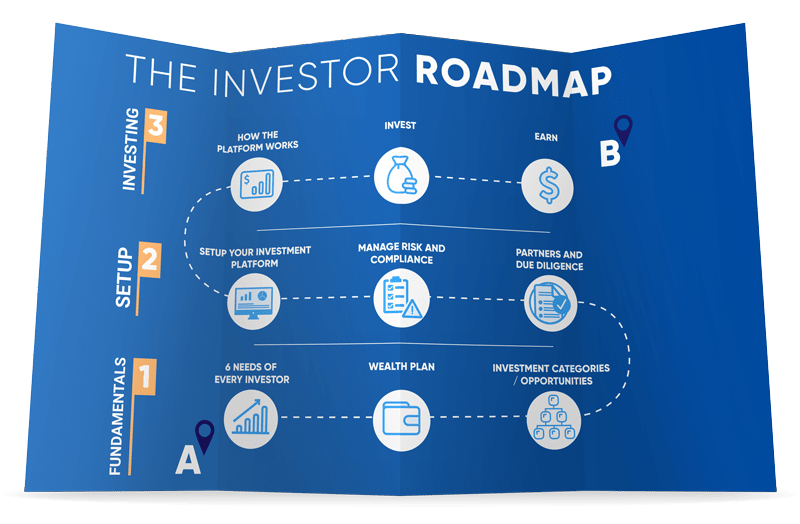
Think of it as a living document, not a one-time checklist. It captures your financial goals, risk tolerance, time horizon, tax situation, and the specific strategies you plan to use. The roadmap changes as your life changes. You update it quarterly, not annually, because your circumstances don't stay static. When I rebuilt mine in 2019, I listed out every holding, assigned it a strategic purpose, and wrote down the conditions under which I would sell. That exercise alone reduced my annual trading costs by roughly eighty percent. The core components are straightforward. You define your objective. Realistic ones are things like funding retirement in twenty years, saving for a house down payment in five years, or generating passive income streams. Vague ones like making more money or beating the market are worthless because they give you nothing to measure against. Then you assess your risk capacity. This means quantifying how much drawdown you can handle psychologically and financially before you start panicking and making irrational decisions. Most retail investors overestimate both numbers. Next comes strategy selection. This is where people diverge. Some choose passive indexing, others pick individual stocks, some blend both approaches. The roadmap doesn't prescribe one path. It forces you to articulate why you chose your path and what metrics you will track to evaluate whether it is working. I personally blend core index holdings with a satellite position of individual stocks, and my roadmap explicitly limits the satellite allocation to fifteen percent of total portfolio value. That constraint alone prevented me from making stupid moves during the 2020 crypto boom.
The Step-by-Step Process I Use
Start with a financial sitrep. Write down your total investable assets, monthly cash flow, debt obligations, emergency fund status, and current portfolio allocation. This takes about twenty minutes if you have your accounts organized, longer if you do not. I keep all my brokerage statements, retirement accounts, and tax documents in a single shared folder on Google Drive. Before I updated the roadmap, I spend Sunday afternoons pulling fresh data from each source. The data pulls take roughly forty-five minutes. The actual roadmap editing usually takes about fifteen minutes after that because the structure is familiar. Define your goals with measurable targets. Instead of writing retire comfortably in ten years, write accumulate two million dollars in taxable and tax-advantaged accounts by December 2033, achieving a real return of seven percent annually adjusted for inflation. Specific targets let you run periodic performance reviews. Generic targets lead to rationalization and excuse-making when things go wrong. I learned this after my first major investment loss in 2016 when I told myself I was playing long-term even though I had no specific long-term definition. The lack of clarity made it easy to ignore red flags. Document your risk tolerance with actual numbers. Write down the maximum percentage drawdown you can accept without selling, the maximum single-sector concentration you find comfortable, and the worst-case scenario you could financially survive. Most people never do this exercise. They assume they are more risk-tolerant than they actually are. My personal limits are a twenty-five percent drawdown tolerance, a thirty percent maximum single-sector cap, and a survival scenario where portfolio value drops to zero and I still meet basic living expenses for eighteen months using my emergency fund and part-time income. Those numbers are tighter than I initially expected, which forced me to rebalance my portfolio toward less volatile positions.
Get the Full Details

Choose your strategy and write down the decision rules. If you use passive indexing, specify which index funds you hold, the target allocation percentages, and the rebalancing triggers. If you pick individual stocks, document your buy criteria, sell criteria, position sizing limits, and maximum holding period. I use both approaches, and my roadmap explicitly requires a quarterly review of every individual stock position against my original investment thesis. When a thesis breaks, I sell within the current quarter, not months later hoping it recovers. That discipline has saved me from averaging down into losing positions on multiple occasions.
Common Mistakes I See Repeatedly
The first mistake is treating the roadmap as a static document. I watch too many people fill it out once and never revisit it. The investing landscape changes. Tax laws change. Your personal circumstances change. Your roadmap must change with them. I update mine every January and every time a major life event occurs, like a job change, marriage, divorce, or inheritance. Those updates typically take about twenty minutes, but skipping them leaves your strategy misaligned with reality. The second mistake is setting unrealistic expectations. Writing target a twenty percent annual return without acknowledging the extraordinary luck or leverage required is just fantasy. Historical stock market returns average around seven to ten percent annually before inflation. Strategies claiming higher consistent returns either involve hidden risks, short time windows, or survivorship bias. I once reviewed a colleague's roadmap and saw him targeting fifteen percent annual returns with a moderate risk profile. He was fundamentally misaligned with how markets actually work. We adjusted his targets to nine percent, which forced him to reconsider his entire strategy rather than chase unsustainable returns. The third mistake is overcomplicating the document. Some people create fifty-page roadmaps with granular monthly targets, complex tracking spreadsheets, and elaborate scoring systems. Most roadmaps should fit on two or three pages. The simpler the document, the more likely you are to actually read it and act on it. My personal roadmap is four pages total. The first page has goals and risk numbers. The second page has strategy descriptions and decision rules. The third page has current holdings with allocations and thesis summaries. The fourth page is a blank reference section for notes and future updates. Anything beyond that is administrative bloat that prevents action.
The Specific Problem I Encountered with Tax Efficiency
About three years ago, I hit a wall with my roadmap because I never accounted for tax location strategy. I held tax-inefficient bond funds in my taxable account alongside tax-efficient index funds, creating unnecessary tax drag. The problem became obvious when I reviewed my annual tax documents and saw hundreds of dollars in avoidable ordinary income tax from bond fund distributions. I solved it by rebalancing my taxable account to hold only tax-efficient assets, moving the bonds to tax-advantaged accounts where possible. The rebalancing took a weekend, but the tax savings alone added roughly one percent to my annual net return. This edge case taught me to add a tax efficiency review section to my roadmap. Now every January, I evaluate whether each holding is in the optimal account type based on its tax characteristics. Bond funds generally belong in tax-advantaged accounts. Equities with low turnover belong in taxable accounts. This analysis usually takes about thirty minutes, but the impact on after-tax returns is disproportionate to the time investment.
When the Investing User Guide Roadmap Fails You
The roadmap is not a crystal ball. It does not predict market crashes, individual stock collapses, or macroeconomic shifts. During the 2022 bear market, my roadmap told me to hold because my investment theses remained intact, but the market dropped thirty percent anyway. The roadmap did not prevent losses. It prevented panic selling. I felt the same fear everyone else felt, but I had written down my decision rules in advance, so I followed them instead of improvising under emotional pressure. The difference between those two behaviors is substantial over long time horizons. Another limitation is the false sense of security. Some investors treat roadmap completion as a substitute for ongoing education and due diligence. I see this frequently among people who fill out a template and then stop paying attention. The roadmap is a foundation, not a finished product. You still need to monitor your holdings, review your strategy periodically, and adjust as new information becomes available. A roadmap without continued engagement is just paperwork.
Practical Tips for Getting Started
Use a simple document format. Google Docs, Notion, or even a basic text file works fine. Do not over-engineer the tool. The medium is less important than the discipline of actually writing things down and revisiting them regularly. I started with a Word document in 2017, switched to Notion in 2020, and now maintain mine in a simple markdown file synced to GitHub. The platform changed, but the core practice did not. Pick whatever tool lets you update the document quickly and reliably. Set calendar reminders for quarterly reviews. I use Google Calendar events that repeat every three months, timed for the first Sunday of January, April, July, and October. Each reminder includes a checklist of items to update, like current allocation percentages, holding thesis summaries, and tax efficiency notes. The reminders typically take about forty minutes to complete. Skipping them creates drift between your stated strategy and your actual behavior. Share your roadmap with a trusted advisor or accountability partner if possible. Not for approval, but for perspective. An outside reader spots inconsistencies you miss because you are too close to the details. I share my roadmap with a financial planner I see twice a year. He catches allocation drift and tax inefficiencies that I overlook during my self-reviews. The conversations usually last about fifteen minutes, but the blind-spot detection is valuable enough to justify the arrangement.
A Note on Alternative Approaches
Some people prefer automated portfolio management platforms like Vanguard Personal Advisor Services, Betterment, or Wealthfront. Those tools handle allocation, rebalancing, and tax-loss harvesting automatically. They cost about one percent of assets annually, which matters significantly over long periods. If you do not want to maintain a personal roadmap, automated platforms are a reasonable alternative, especially for investors with moderate portfolios where the one-percent fee is offset by professional management and behavioral coaching. For larger portfolios or investors who want full control, maintaining your own roadmap plus working with a fee-only fiduciary advisor is usually more cost-effective. Fee-only advisors charge hourly or a flat retainer rather than a percentage of assets, so your costs do not scale with portfolio size. I pay about two thousand dollars annually for quarterly reviews with my advisor, which is cheaper than a one-percent advisory fee on a six-figure portfolio. The choice depends on your portfolio size, time availability, and comfort with self-management. The Investing User Guide Roadmap is not a magic solution. It is a discipline tool that forces clarity before capital deployment. Most people skip it because it requires honest self-assessment and ongoing maintenance. I used to skip it too, until I lost money doing so. The effort required is modest, maybe two hours total during initial setup and about two hours per year for maintenance, but the behavioral and financial benefits compound over time. Start simple, update regularly, and be honest about your actual risk tolerance rather than your aspirational one.