How to Actually Use an Investment Mortgage Calculator Without Losing Your Mind
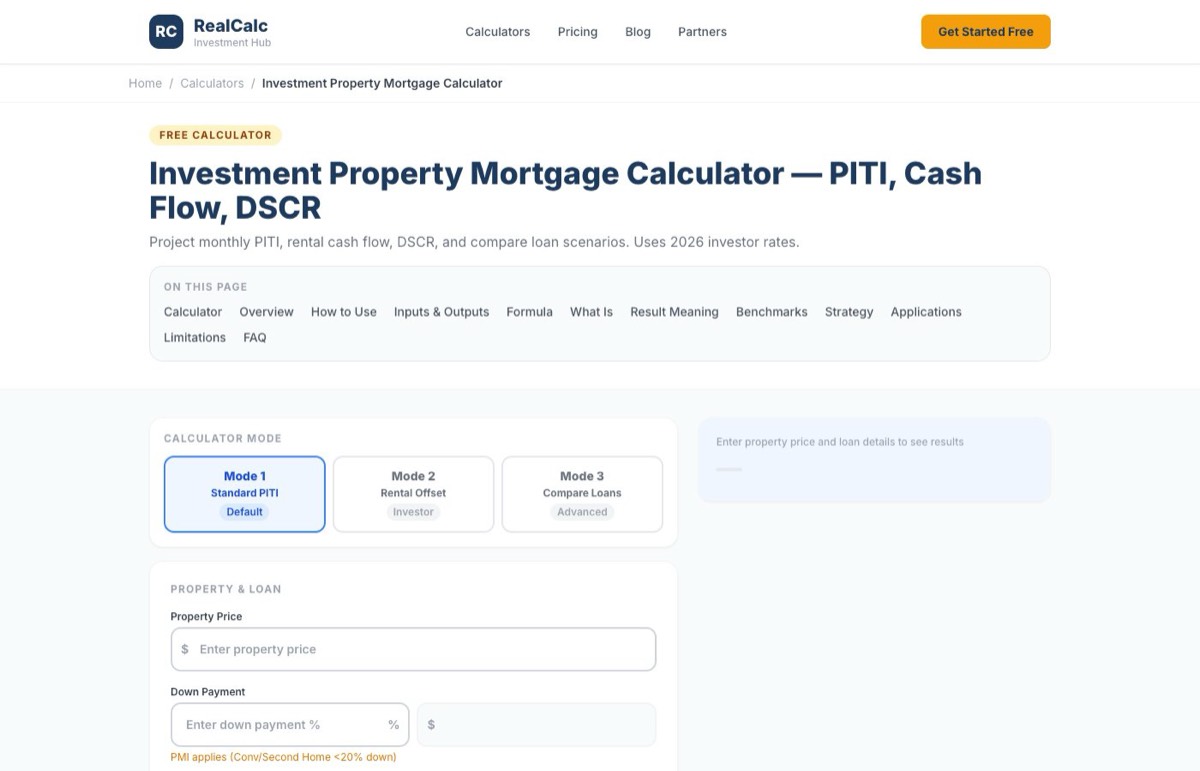
You plug in the numbers, you hit calculate, and you get back a monthly payment that looks completely wrong compared to what your broker quoted. This happens constantly. The gap is almost never a bug in the calculator. It is usually something specific about how the tool handles vacancy reserves, property management fees, or the way it rounds debt service coverage ratios. I spent three years dealing with rental property underwriting before I learned to trust my own spreadsheets over whatever generic calculator a lending platform pushes onto you. At its core, an Investment Mortgage Calculator computes the monthly payment on a loan intended for a rental property rather than a primary residence. That distinction matters because the rate is typically higher, the down payment requirement is stiffer, and the underwriting looks at the property's ability to cover the payment through income rather than your personal salary alone. A basic calculator will spit out principal and interest using the standard amortization formula. Anything more useful will also factor in taxes, insurance, HOA fees, vacancy, and maintenance to give you a complete monthly out-of-pocket number. That complete number is what actually determines whether a deal works or blows up six months later. Most online tools default to optimistic assumptions. You need to force them to use your actual numbers. Start by selecting the right loan type. Investment properties sit in a different risk bracket, so lenders price them differently. You will see rates jump 0.5 to 0.75 percent above owner-occupied rates on average. The calculator should let you adjust this manually if it does not do it automatically.
Next, handle the down payment correctly. The industry standard minimum is 20 to 25 percent, though some portfolios allow 15 percent with a higher rate. If you are running numbers for a multi-unit property with up to four units, the lender may let you treat it closer to a residential loan. Your calculator needs to reflect that variance. I once ran a four-plex deal through a free online Investment Mortgage Calculator and got back a payment that was $200 per month too low because the tool was applying a primary-residence debt-to-income framework instead of the investment property cash flow analysis the lender actually requires. I caught it when the underwriter asked for a revised schedule. The workaround was straightforward: I rebuilt the model in a simple spreadsheet, set the cap rate assumption to 5.5 percent for that market, plugged in a 1.25 vacancy multiplier, and ran the DSCR calculation separately before feeding it back into the payment estimate. It took twenty minutes and saved me from walking into a commitment I could not fulfill.
Advanced Inputs Most Calculators Miss
Here is where beginners get burned. An Investment Mortgage Calculator that only computes principal and interest is giving you roughly half the picture. You need to account for several line items that either get ignored or hidden behind vague assumptions. Vacancy and credit loss. The standard rule of thumb is 5 to 10 percent of gross scheduled income. In markets with high tenant turnover, push it to 12 percent. The calculator should let you enter this as a percentage rather than a fixed dollar amount because it compounds across years. Property management. If you are not living on site and managing the units yourself, budget 8 to 12 percent of collected rent. Some investors forget this entirely until the numbers do not cover the payment and they realize they are subsidizing their own property from their day job income.
Get the Full Details
Maintenance reserves. The 1 percent rule is a starting point, not a law. Roof, HVAC, water heater, and appliances all have replacement cycles that do not care about your cash flow projections. Set aside 5 to 15 percent of gross rent depending on the age and condition of the building. Older properties absolutely require the higher end of that range. Special assessments and CAM charges. If you are dealing with a condo or co-op investment, these can eat your cash flow silently. They show up on your closing statement but not on any standard payment estimate.
Counter-Intuitive Insights That Save Deals
The first thing most people miss is that the loan amount and the income the property generates exist in a feedback loop. Higher purchase price means higher loan, which means higher payment, which means you need more income to qualify, which often means a lower price you can actually afford. Running the numbers linearly instead of iteratively will make you think a deal qualifies when it does not. Use an iterative approach. Pick a target payment, work backward to the maximum loan amount the property can support at your assumed vacancy and expense ratios, then compare that to the purchase price. If they do not align, adjust your assumptions or walk away. The second thing nobody tells you about investment mortgage calculations is that prepayment penalties can distort your exit strategy. Many investment property loans carry a yield maintenance clause or a soft prepayment penalty for the first five to seven years. If your calculator does not factor in the cost of selling early, your pro forma returns will look better than they actually are. A 2 percent prepayment penalty on a $400,000 loan is $8,000 that disappears the moment you try to refinance or sell in year three. That is not a small number.
When to Ditch the Calculator and Do Manual Underwriting
Generic calculators fail in specific scenarios. If you are analyzing a value-add renovation project where rents will increase significantly after improvements, most tools cannot handle phased income assumptions. If you are dealing with a mixed-use property where commercial and residential spaces occupy the same building, the loan structure changes and standard residential calculation engines will give you garbage output. If the property has unusual lease structures like triple net leases or percentage rent agreements, the calculator will not know how to model the income variability. In these cases, build a simple spreadsheet with separate tabs for purchase assumptions, operating expenses, debt service, and cash flow projection. Use actual rent rolls instead of market averages. Run twelve months of projected income with seasonal vacancy built in. Calculate DSCR at the loan level, not just at the property level. The whole process takes about 45 minutes for a typical single rental property and about two hours for a small multi-unit building. The Investment Mortgage Calculator tools you find online will get you to an answer in thirty seconds, but that answer will be wrong half the time on anything beyond a standard stick-built rental in a stable market.
Practical Limits You Need to Accept
Even a well-built calculator cannot predict the actual terms a lender will offer you. Rates shift weekly. Lender overlays on investment properties vary wildly between institutions. A calculator might tell you a $350,000 loan at 7.5 percent gives you a payment of $2,449, but the lender you eventually talk to might price you at 7.875 percent or require a 30 percent down payment because of their internal risk scoring. The calculator is a planning tool, not a commitment. Use it to screen deals and eliminate obvious failures quickly. Then verify every number with actual lender quotes before you make an offer. The margin between a good deal and a bad one on investment property is usually smaller than the error margin in your assumptions, which is exactly why manual underwriting matters even when the calculator says everything is fine. The best approach is to use a reliable Investment Mortgage Calculator for initial screening, then rebuild the same deal in your own spreadsheet with conservative adjustments to every variable, and finally confirm the numbers with a lender who underwrites investment property loans on a regular basis. That three-step process removes most of the blind spots that trip people up.