Modern Portfolio Construction Is Mostly About Risk Budgeting
You don't need complex models to start building portfolios. The core mechanics are straightforward, but the mistakes people make are consistently the same ones. Most of them skip the risk allocation step and jump straight into picking assets. That approach produces uneven risk concentrations without the person realizing it. Let's talk about the actual workflow instead of definitions. Here's how I build and maintain a portfolio, then I'll circle back to the theory behind it.
How to Build a Portfolio Using Investment Theory
Start by deciding your universe. Pick the asset classes you're comfortable holding for extended periods. A realistic set might include US equities, international developed equities, emerging market equities, aggregate bonds, TIPS, and real estate. Don't add more than six or seven categories in the beginning. More categories create tracking problems and dilute your ability to think clearly about each one. Next, estimate expected returns and risks for each category. This is the hardest step because people treat these estimates as facts. They aren't. Back-test periods don't predict forward results. A practical workaround is to use long-run historical averages adjusted for current valuations. For equities, if the Shiller P/E ratio is above 25, trim your equity return expectation by 1 to 2 percentage points from the historical average. It's crude. It works better than doing nothing. Calculate the correlation matrix. This is where most people stop paying attention, and it's the reason portfolios blow up. Correlations spike toward 1 during drawdowns. The 2008 financial crisis demonstrated this clearly across every asset class that claims to be uncorrelated. You need to stress your correlation assumptions against at least one major crisis period. I built a spreadsheet that runs my portfolio through 2008, 2011, and March 2020. The difference between the model output and reality during those periods is significant enough to change allocation decisions.
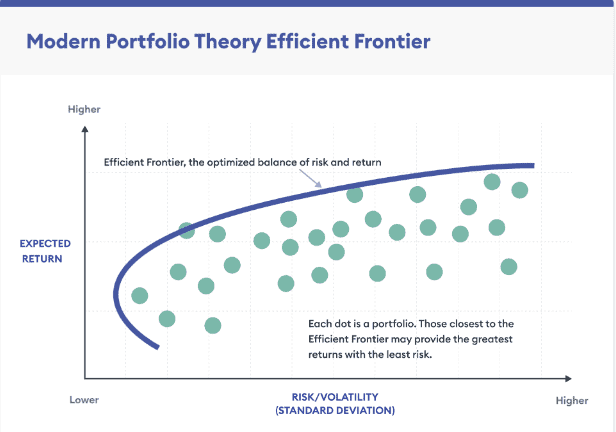
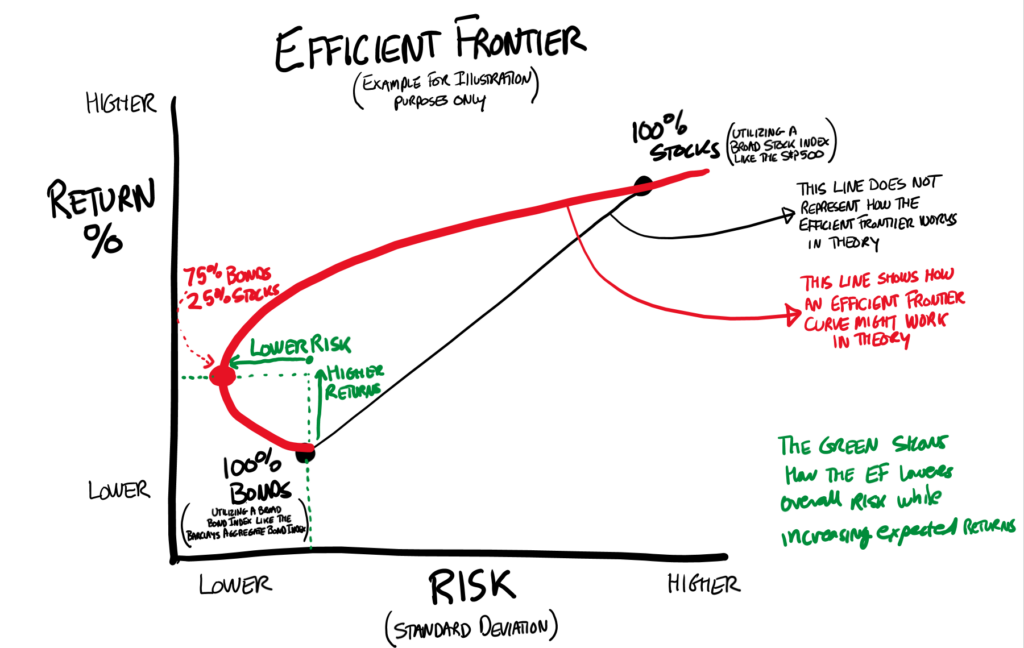
Run a mean-variance optimization. Any decent spreadsheet or free tool like Portfolio Visualizer will do this. The output you get from a standard optimizer is almost always impractical. It assigns extreme weights to a few assets and negative weights to others. I learned this the hard way in 2019 when I optimized a custom mix of factor ETFs. The optimizer gave me 60 percent in value, -30 percent in quality, and 70 percent in momentum. I tried implementing it through a broker that allowed short selling, and the margin requirements nearly liquidated me during a routine volatility spike. The workaround was simple: constrain the optimizer to weights between 0 and 35 percent per asset class, require minimum positions of 5 percent, and cap any single factor exposure at 25 percent. Translate the optimized weights into actual holdings. Account for rebalancing costs, tax implications in taxable accounts, and trading liquidity. A 200-basis-point transaction cost on a position you allocated 3 percent to eats most of the expected benefit. Rebalancing bands work better than calendar rebalancing. Set a threshold of 5 percent absolute deviation from target weight, or 25 percent relative deviation, whichever comes first. This cut my rebalancing activity from quarterly to roughly twice a year without materially affecting risk characteristics.
Get the Full Details

The Risk Parity Alternative
Mean-variance optimization has a well-documented flaw: it is extremely sensitive to input errors. Small changes in expected return assumptions produce wildly different portfolio compositions. Risk parity addresses this by allocating based on risk contribution rather than capital contribution. Bonds typically contribute far less risk than equities, so a risk parity approach increases bond allocation until each asset class contributes equal risk. This shifts the portfolio toward a more diversified risk profile. The trade-off is lower expected returns during equity bull markets. I use a hybrid approach. Core holdings follow a risk parity framework, and satellite allocations use mean-variance outputs with the constraints I described above. Investment Theory works well in stable macro environments with normal market dynamics. It fails during structural regime changes. The period from 2020 to 2022 showed exactly this. Bonds and equities moved together, correlations collapsed to zero or turned positive, and standard diversification provided almost no protection. The theory isn't wrong. The inputs were just based on a decades-long environment of falling inflation and rates that no longer exists. When regime shifts happen, you need to adjust your expected return assumptions and correlation matrices, not abandon the framework entirely. The adjustment process adds maybe 30 minutes of work per quarter. It prevents catastrophic alignment failures. Another limitation worth stating plainly: Investment Theory assumes rational actors and normal distribution of returns. Markets don't behave normally. Fat tails and skewness matter. A portfolio can look perfect on paper and still suffer a 40 percent drawdown because of an event that hasn't happened before. I size my positions based on scenario analysis rather than pure optimization output. This usually reduces expected returns slightly but increases survival probability significantly. That trade-off is worth it for most investors.