What This Job Actually Looks Like Day to Day
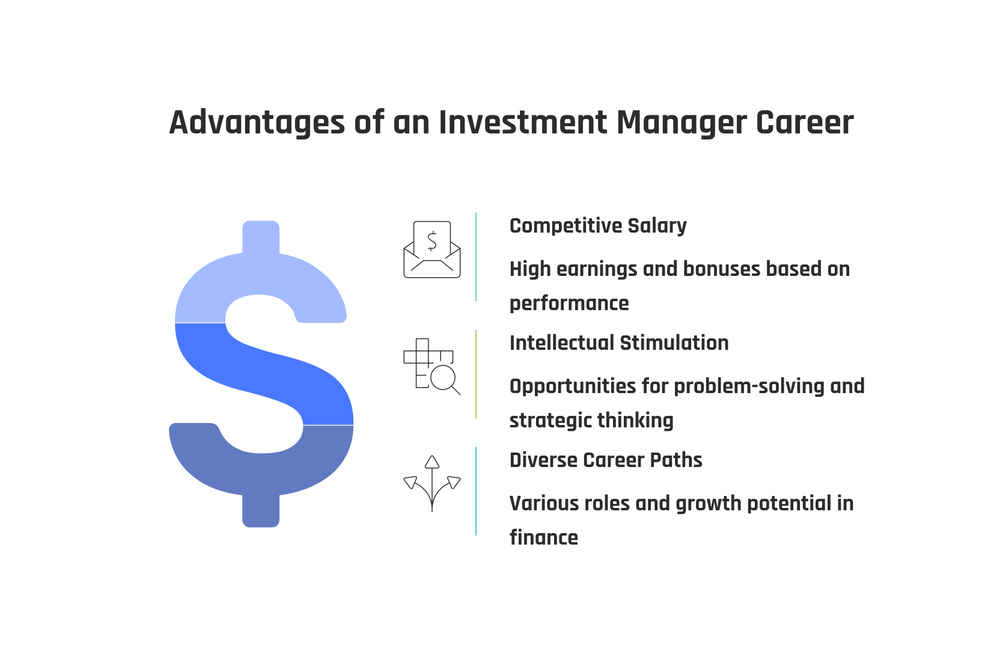
You walk into a room full of people who already have money and need someone to make sure it stays there while quietly growing. The work is part finance, part psychology, part compliance paperwork that will eat your evenings if you let it. It is not glamorous. It is not the TV version either. Most days you are running projections, reconciling client expectations, and dealing with people who panic when their portfolio drops three percent in a week. The compensation can be solid. Entry-level analyst roles at mid-tier firms often start somewhere between 55 and 75 thousand with bonuses tied to book growth and referral activity. Associates pushing toward CFA or CFP credentials can see total comp climb to 120 to 180 thousand within five to seven years, assuming you bring in and keep clients. Senior portfolio managers at established firms routinely clear 250k plus, but those spots require demonstrated AUM responsibility and a track record that survives a market downturn, not just a bull run.
Is Wealth Management A Good Career
The honest answer depends entirely on what kind of person you are and how well you handle rejection. This is a sales-adjacent profession wrapped in fiduciary language. You will meet clients who do not want you. You will lose accounts because a competitor offered a slightly lower fee or because a client's child talked them into switching firms. You will also watch people hand you their most important financial decisions because they trust you, and that trust is the currency that actually drives income here. I have seen people burn out in eighteen months because they treated it like a pure investment job. It is not. It is relationship management first, analysis second. The people who last and thrive are the ones who enjoy talking to strangers about things most humans find stressful. If that describes you, the ceiling is genuinely high. If you dread cold outreach and client calls, you will be miserable regardless of the pay scale.
The Skills That Actually Matter
Licensed professionals need a Series 7 and Series 65 minimum, sometimes a Series 66 depending on state requirements. That takes about four to six weeks of focused study for someone with a finance background. After that comes the real work: learning how to construct portfolios that survive tax events, understanding the difference between tax-loss harvesting and wash sale traps, and knowing when to recommend municipal bonds versus taxable holdings based on a client's marginal bracket. Most juniors underestimate estate planning and insurance needs analysis. They think clients just want stock picks. They do not. A properly structured revocable trust discussion can differentiate you from three other advisors in the same room. A gifting strategy review using annual exclusion amounts is another area where real value shows up without requiring complex derivatives or hedge fund access. The technical side converges around financial planning software like eMoney or MoneyGuidePro. Learning these tools properly cuts client proposal time from four hours down to forty-five minutes. The default templates are terrible though. You will spend your first few months building your own assumption libraries and scenario ranges. It is tedious but it compounds quickly.
Get the Full Details
A Problem I Actually Faced
Early in my career I inherited a client whose portfolio was heavily concentrated in restricted stock from a company exit. The liquidity event had happened eighteen months prior and the shares were technically unrestricted but the client refused to sell anything above a certain threshold. He had emotional attachment to the ticker and every time I flagged diversification risk he got defensive and almost walked. The workaround was not a conversation about modern portfolio theory. It was constructing a structured sell plan using limit orders layered across twelve months with predefined price triggers, paired with a tax cost analysis showing him that holding concentrated exposure was mathematically costlier than gradual rebalancing. I ran the numbers showing the incremental tax basis impact versus the diversification benefit. He signed off on a phased reduction over two years. He still checks his position quarterly and occasionally asks about selling more but the account is nowhere near the concentration risk it was before. This is the actual job. Not chart patterns. Structured conversations with hard data backing every recommendation so the client feels in control even when you are the one driving the decision.
Where This Career Breaks Down
Regulatory overhead is heavier now than it was ten years ago. SEC and state level exam cycles mean your compliance department will audit your client communications, your suitability files, and your marketing materials on random schedules. Some firms require pre-approval on every email draft that mentions a specific security. This slows everything down and adds administrative cost that gets passed through in fees or eaten into margins. The fee compression trend is real. Large institutional players and digital robo platforms have pushed advisory fees from the historical one percent range down to forty to sixty basis points for straightforward portfolios. You are either moving upmarket to ultra-high-net-worth clients who pay for complexity and family governance work, or you are scaling volume to compensate. Both paths have structural pressure. Burnout comes from the combination of quota-driven cultures at some broker-dealer firms, the emotional labor of managing anxious wealthy clients, and the seasonal spike in spring filing season when every client suddenly needs their retirement income plan updated alongside their tax situation. The calendar is not forgiving. December through April is heavy. Summer is lighter but never empty.
If you want a lower-stress path with steady income and less direct client interaction, consider moving into institutional asset allocation or portfolio construction roles at larger funds. The pay is good and the hours are more predictable but the ownership of client relationships disappears. Wealth management is fundamentally a people business. Lose interest in that and the rest does not compensate.
How to Enter Without Wasting Time
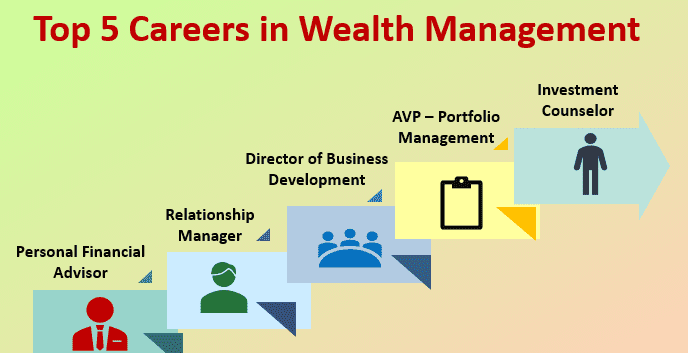
Start with the licensing. Series 7 first, then Series 65. Study materials from Kaplan or Brainscape cards work fine. Do not overcomplicate it. Most firms sponsor the exams and pay the fees if you pass on the first attempt. If you fail twice, they start asking questions about your commitment level. Pick a firm whose business model matches your personality. Wirehouses like Morgan Stanley and Raymond James push aggressive business development. Regional firms like St. John Capital or independent RIA shops prioritize relationship depth over volume. The compensation structures are different enough that choosing wrong means two years of rebuilding your pipeline from scratch. Learn one specialization deeply before applying. Tax-efficient withdrawal strategies, social security optimization, or executive compensation planning are niches where genuine expertise commands higher fees and creates stickier client relationships. Generalists survive. Specialists bill better.
The career works if you tolerate the sales reality, respect the compliance framework, and accept that wealth management is mostly about managing expectations rather than chasing alpha. Most portfolios cannot beat their benchmark net of fees anyway. The value is in behavior coaching, tax logistics, and keeping clients from making emotional decisions during drawdowns. That is the actual job description behind every title and salary figure.