Filling Out the NY IT-201 Can Be a Pain. Here's What Actually Works.
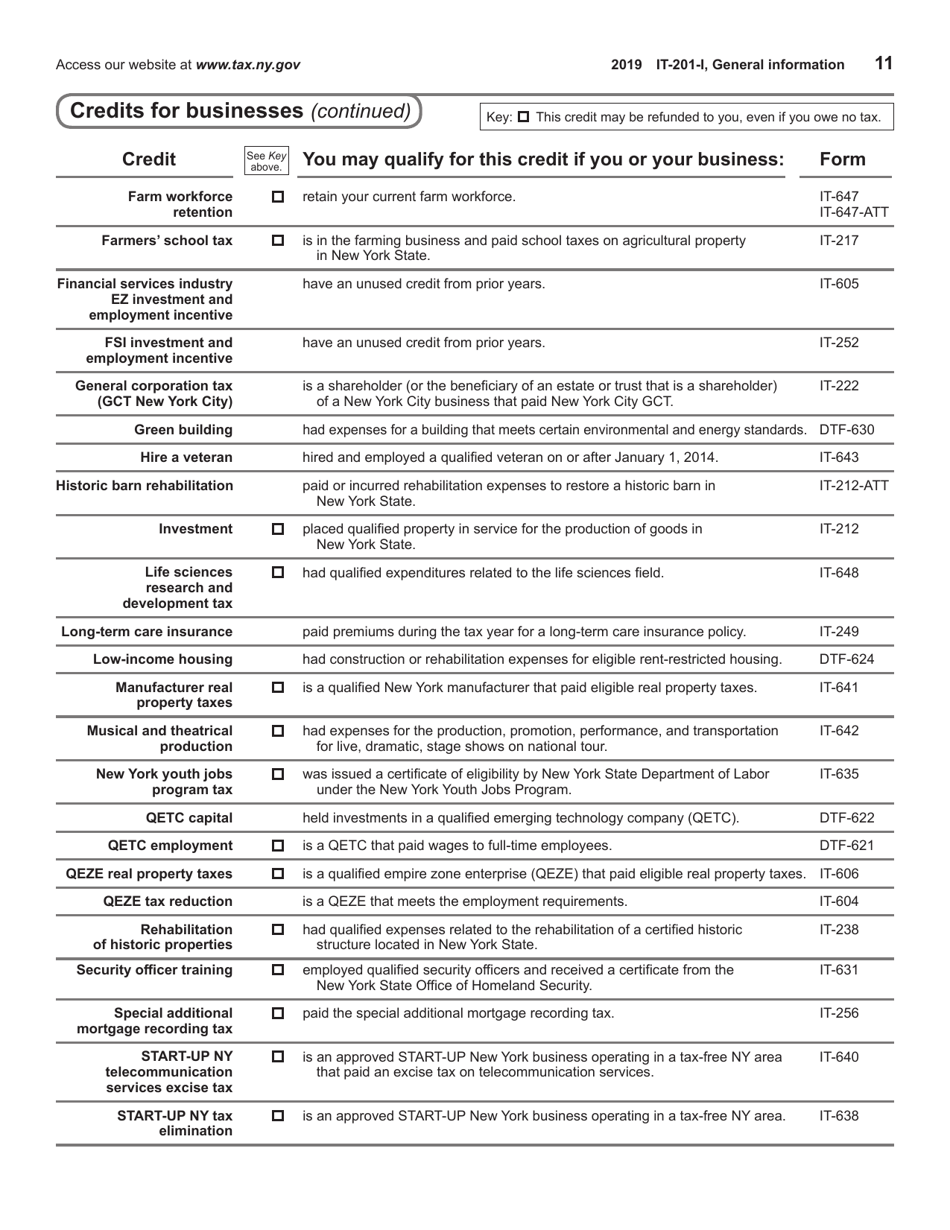
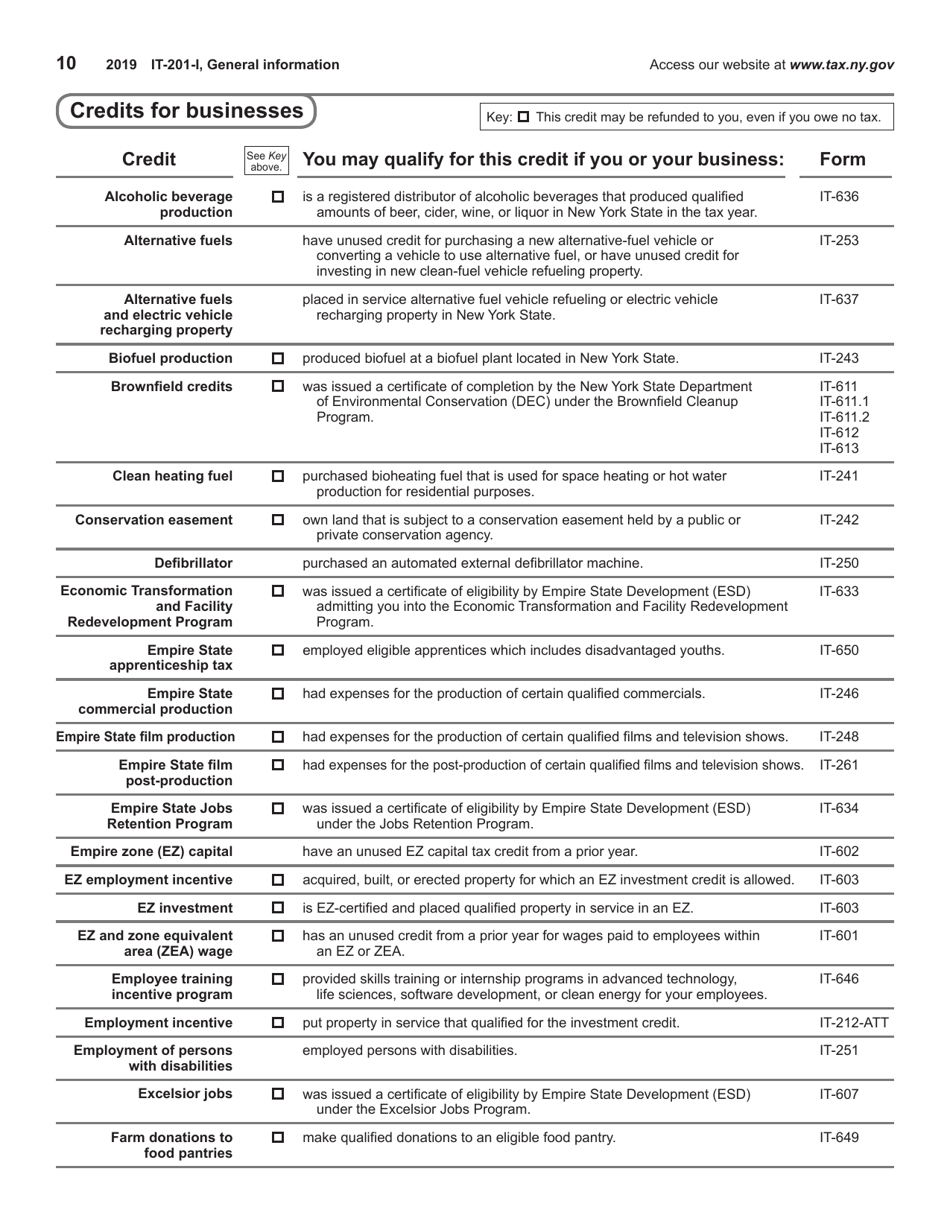
The New York State IT-201 is the corporate franchise tax return, and the ATT section is where most people lose track of themselves. The attachments—Schedule T, T-INT, T-SCI, UBT, and the various worksheets—aren't just extras. They're where the actual calculation happens for most filers. The instructions that come with It 201 ATT Instructions will tell you the requirements in a fairly readable way if you actually sit down and work through them instead of skimming. The NYS Department of Taxation and Finance website is the primary source. Go to nyc.gov/tax and search for IT-201, or use the direct form page. You want the current year's package, which includes the form itself, the attachment schedules, and the companion instruction booklet. If you're filing electronically, the same documents apply but you'll populate them in the system rather than printing and mailing. Stick with the official source. Third-party sites often have outdated versions, and filing with the wrong schedule numbers is a real headache to unwind later. Important: the instruction booklets and forms change somewhat every year. Don't rely on last year's packet.
The Attachments Breakdown
The core ATT schedules map directly to different parts of the tax calculation. Most corporations will deal with at least Schedule T, which handles the allocation and apportionment factors. If you have intangible income, you'll need T-INT. Real or personal property income goes on T-SCI. Unincorporated business tax entities have their own worksheet (UBT). There are also supplemental schedules for things like the manufacturing deduction, the C-Corp specific adjustments, and any credit carryforwards you're claiming. Here's the thing that catches people off guard: the instructions often cross-reference each other. Page 3 of the Schedule T instructions might tell you to "see Schedule T-INT, line 8." If you're working through the form linearly and skip that, you'll end up with mismatched numbers and the return gets rejected or you owe more than you should. Another quirk: some schedules require you to calculate values on one worksheet, transfer the final number to the main IT-201, and then ALSO report a detail line on a separate attachment. That's by design, not an error. Just make sure your cross-checks are consistent before you finalize.
How I Actually Work Through It Year After Year
I don't start with the IT-201 itself. I start with the attachments because they drive the numbers. My process is roughly: First, I pull the prior year's return and the current year's trial balance or general ledger. I check for any structure changes—mergers, acquisitions, new subsidiaries, or business line sales—because those dictate which schedules you need beyond the standard ones. If there was a sale of real or personal property used in the business, you'll need T-SCI regardless of whether it shows up prominently in your GL. Then I work Schedule T. The allocation and apportionment percentages are the backbone. The three-factor formula (property, payroll, and sales) still applies for most C corps, but the weighting changed in recent years. Check the current instruction booklet for the exact weights for the tax year you're filing. One thing people consistently miss: the payroll factor numerator includes compensation paid to employees in New York, but the definition of "compensation" here follows federal withholding rules, not GAAP. If you've got stock-based comp or deferred compensation, the numbers on your financial statements won't match what goes in the payroll factor without adjustment.
Get the Full Details
After T comes T-INT and T-SCI if applicable. Then the UBT schedule if you're dealing with passthrough entities. After that, I fill in the main IT-201 body using the totals from the schedules. Finally, I review the credits section and any required disclosures.
A Specific Problem I Ran Into (and How I Fixed It)
Once, I had a client who had a subsidiary that was taxed as a partnership for federal purposes but file a consolidated return at the state level. The IT-201 ATT instructions for the consolidated filing section assumed certain intercompany transactions were already eliminated, but the subsidiary's schedule K-1 had pass-through items that showed up on the parent's IT-201 ATT worksheets in a way that double-counted income in the apportionment factors. The return looked fine on the surface because the total tax came out close, but the allocation percentages were wrong, and we'd have been subject to a penalty if the state had caught it. The workaround was straightforward once I found it: I went to the consolidated return instructions, located the intercompany transaction adjustment section, and manually removed the subsidiary's NYS-sourced payroll and property from the apportionment numerator before entering the final T schedule numbers. I also flagged the issue in the supporting documentation so any subsequent review would have the trail. It added maybe 45 minutes to the workload but saved us from what could have been a much larger problem down the line.
Common Mistakes I See Repeatedly
People forget to attach schedules that are technically required. The instructions sometimes say "file if applicable," and filers interpret that as optional when it's not. If the calculation on the main form produces a number that depends on an attachment, the attachment is mandatory regardless of how the instructions phrase it. Another frequent issue is using the wrong tax year's forms. The NYS fiscal year and federal calendar year don't always align in how they're reported, and the forms themselves have year-specific line numbers. If your client's books close on a different date than the standard calendar year, you need to make sure the forms match. Electronic filers sometimes skip the attachment upload step or upload PDFs in the wrong format. The system will accept some file types and reject others. Check the e-file documentation for the specific requirements before you try to submit.
What This Method Doesn't Handle Well
The NYS IT-201 ATT instructions are thorough but they assume a fairly standard corporate structure. If you're dealing with multi-state consolidation, foreign subsidiaries, or complex credit structures, the instructions alone won't get you to the right answer. You'll need to reference the general corporation tax law sections and possibly get professional guidance. The instructions also don't cover edge cases like basis step-up elections under recent federal legislation and how those flow into the NYS apportionment calculation. If your situation is straightforward—a domestic C corp with one or two active businesses, no unusual deductions or credits—the IT-201 ATT packet and the companion instructions will get you through. For anything more complex, budget additional time for research and possibly consulting a tax professional who knows New York corporate filing specifically. The state doesn't give you much room for interpretation errors, and the penalties for underpayment based on incorrect apportionment can add up quickly.
It 201 ATT Instructions Download and Final Notes
You can download the full instruction package, including all attachment schedules, from the NYS tax website. Look for the "Forms and Instructions" section under the IT-201 heading. The package typically includes the main form, every applicable ATT schedule, the worksheet pages, and the instruction booklet. Take the time to read the instruction booklet cover to cover before you start filling anything out. It takes about 20 minutes and will probably save you hours of rework. Keep a copy of every schedule you file, even the ones that seem routine. The state can audit returns years later, and having the supporting documentation organized from the start makes that process significantly less stressful.