What IT Financial Management Actually Looks Like When You Are Doing It
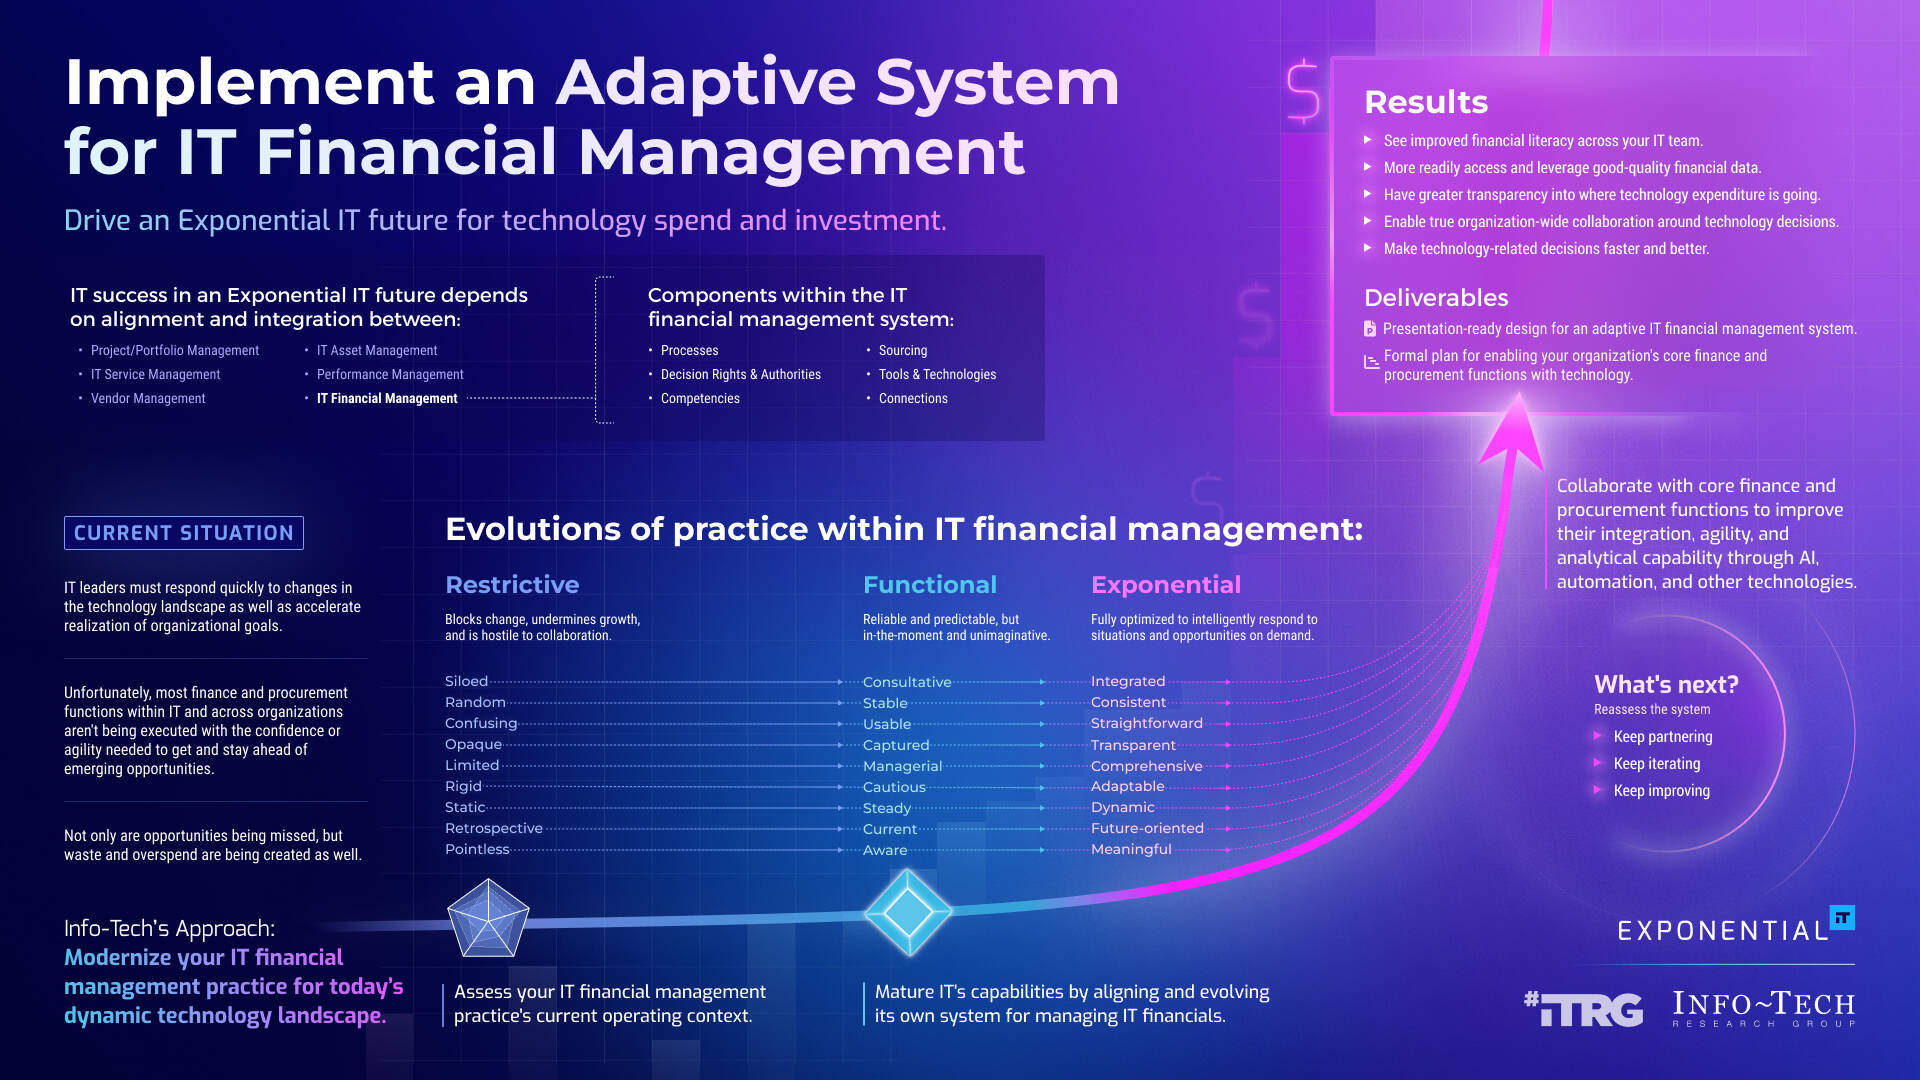
Most people treat IT Financial Management like it is a checkbox exercise. They set up a budget template, copy last year's numbers, adjust for inflation, and call it a day. That approach works fine until costs start migrating to cloud services, licensing models change, or business leaders ask why the infrastructure bill doubled without a clear explanation. The process breaks down fast when you do not have a working model for how IT spend connects to actual service delivery. IT Financial Management, sometimes called ITFM or IT financial planning, is the practice of tracking, allocating, and reporting on the cost of delivering IT services. It combines accounting principles with IT service management frameworks. The goal is simple: know what IT costs, know why it costs that much, and be able to explain it to someone who does not live inside spreadsheets. The reality is messier than that definition suggests.
It Financial Management: The Parts That Actually Matter
The framework rests on three core functions. Cost accounting tracks the real expense of each IT service. Chargeback allocates those costs to the business units that consume them. Showback displays the costs without actually billing anyone. Most organizations use all three to some degree, but they rarely implement them consistently across every service line. Cost modeling is where most projects stall. You need to map indirect costs like power, facility space, and network bandwidth onto the services that depend on them. A single shared data center floor supports finance applications, engineering tools, and customer support platforms. Splitting the cost requires decisions about allocation drivers. Square footage works for physical space. Headcount works for help desk labor. Usage metrics work for cloud compute. The choice of driver changes the numbers significantly, and leadership usually does not notice until the report goes out and someone questions why their department's allocation jumped thirty percent. I ran into this exact problem last year with a legacy application that shared infrastructure across three business units. The original allocation model used headcount, which was easy to pull from HR. But the application was being maintained by a small senior team while adoption spread through a larger junior staff. The cost per user looked artificially low for the power users and inflated for everyone else. The workaround was switching to a hybrid model that used vCPU hours for compute costs and seat licenses for software costs, weighted by actual consumption data from the monitoring tool. It took about three weeks to rebuild the allocation tables, but the revised numbers matched what operations was actually seeing in the cloud bill.
One counter-intuitive thing about cost accounting is that getting the numbers exactly right is usually a waste of time. Most organizations spend more effort chasing precision than they save through better decisions. An allocation that is within five to ten percent of reality is good enough for budget discussions. The real value comes from consistency and transparency, not decimal-level accuracy. Budget holders respond better to a model they can trace than to a number that sounds impressively precise. Another detail beginners miss is the difference between TCO and CAPEX versus OPEX treatment. IT Financial Management requires you to classify spend correctly from the start. A server you buy outright is capital expenditure. The same server leased through a cloud provider is operational expenditure. The total cost of ownership looks very different depending on which bucket the spend falls into, and those classifications change how finance teams evaluate proposals. If you are building a cost model, make sure your classification rules are documented before anyone starts entering data. I have seen two people in the same team classify the same vendor invoice differently because nobody wrote down the rule.
Get the Full Details
How to Build a Working IT Financial Model
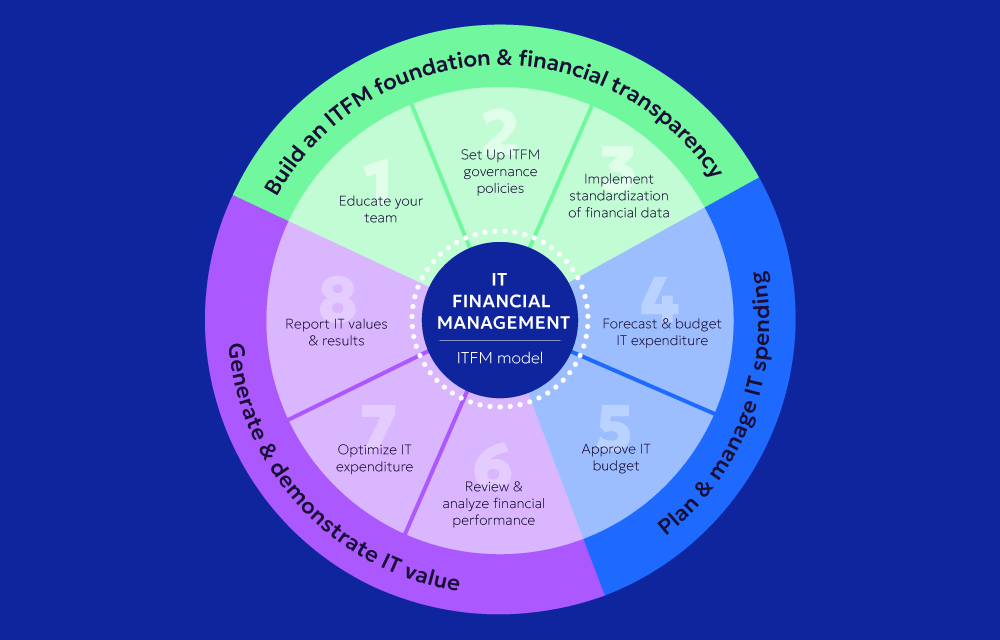
Start with the list of IT services, not the list of cost categories. Most teams begin backwards by pulling general ledger accounts and trying to assign them to services. This produces a messy report where a single electricity line item gets split across twelve services with no clear logic. Services first. Costs follow. Define what each service is, who consumes it, and how it is measured. A service might be email hosting, a development environment, or a customer-facing web platform. The definition should be stable enough that it does not change every quarter. Once the services are defined, identify the cost pools that feed into them. Direct costs are straightforward. Software licenses for a specific application belong to that application. A dedicated server in a virtualization cluster belongs to the workloads running on it. Indirect costs are where the work happens. These include shared infrastructure, management labor, and facility overhead. You need allocation drivers for each pool. The driver should correlate with consumption, even loosely. Network bandwidth costs correlate with data transfer volume. Security tooling costs correlate with endpoint count. Management overhead correlates with the number of services or the headcount supporting them. Build the model in a tool that can handle changes without breaking. Excel works for small environments with maybe fifteen to twenty services. Beyond that, the spreadsheet becomes fragile. A single formula error can shift allocations across dozens of rows. Dedicated ITFM tools or even a properly structured database give you audit trails and version control. The migration from spreadsheet to a structured system usually takes a dedicated person about six to eight weeks if you are pulling data from an asset management system and a general ledger. Do not underestimate the time required for data reconciliation. You will find discrepancies between the asset register and the finance system that have been sitting unresolved for months.
Chargeback and showback require separate decisions. Chargeback means a business unit actually pays for the IT services it consumes. This drives accountability but creates political friction. Departments that were subsidized by others in the past will push back hard when they start seeing real charges. Showback means you report the costs without billing. It achieves the same transparency goal with less organizational resistance. Most large organizations start with showback, move to partial chargeback after a year or two, and then transition to full chargeback only after the model has been validated against actual spend patterns. The biggest bottleneck in IT Financial Management is data quality from the CMDB. If your configuration management database has stale or incomplete records, every allocation you build on top of it is suspect. I have seen organizations try to run a full cost model with a CMDB that was three years out of date. The result was allocations that made surface-level sense but fell apart under any scrutiny. Fixing the CMDB took longer than building the financial model itself. Prioritize asset discovery and relationship mapping before you invest heavily in cost accounting. A clean CMDB with correct service relationships saves roughly forty percent of the time normally spent on data cleaning during model builds.
Where the Model Breaks and What to Do About It
IT Financial Management does not scale well in organizations that frequently restructure. Mergers, acquisitions, and department reorganization invalidate allocation models almost immediately. The financial data stops reflecting the organizational reality, and reconciliation takes days or weeks. The workaround is to build the model with organizational boundaries as optional dimensions rather than fixed values. That way, when a team moves from one division to another, you are changing a parameter, not rebuilding the entire allocation logic. Cloud spending adds another layer of complication. Native cloud cost tools like AWS Cost Explorer or Azure Cost Management provide excellent visibility into consumption, but they do not align neatly with ITIL service definitions. A single AWS account might run a development sandbox, a staging environment, and a production payment system. The cost tags exist but are often incomplete or applied inconsistently. Tagging governance is a separate project that should run in parallel with ITFM implementation. Expect to spend two to three months cleaning up cloud cost allocation tags before your model produces reliable results. Multi-year contracts and amortized costs distort monthly reporting. A software license purchased for three years upfront shows a large cost in the first month if you are not amortizing it. IT Financial Management requires you to spread those costs over the contract period to produce meaningful monthly figures. This is standard accounting practice, but it is easy to skip when you are building a quick model in a spreadsheet. The fix is to treat contract start dates, durations, and total values as first-class data elements in your model, not as footnotes.

The framework also assumes that every IT cost can be traced to a service. In practice, some costs are unallocatable. Corporate strategy work, executive support, and experimental projects often fall outside defined service catalogs. Ignoring them completely distorts the picture. Allocating them proportionally across all services spreads the cost but reduces accuracy. The pragmatic approach is to track unallocatable costs separately and report them as overhead. Business leaders understand this distinction if you label it clearly in the report.
Reporting Without Losing Your Audience
Most ITFM reports fail because they are written for accountants instead of for the people making budget decisions. A table showing fifty line items with eight decimal places is not informative. It is noise. Effective ITFM reporting groups costs into meaningful categories, shows trends over time, and highlights variances that matter. A good format compares actual spend against budget, explains the top three variances, and projects the year-end figure based on current burn rate. That three-page summary is what gets read. The detailed allocation tables belong in an appendix for anyone who wants to dig deeper. Quarterly reviews with business unit leaders are more effective than monthly automated reports. The quarterly meetings give you time to investigate anomalies, validate assumptions with operations teams, and adjust the model before presenting updated numbers. The relationship matters as much as the methodology. Business unit leaders who trust your process accept allocations that are slightly off. Leaders who do not trust the process will challenge every number, regardless of accuracy. IT Financial Management is not a tool you install. It is a discipline that requires ongoing data maintenance, regular model validation, and organizational buy-in. The implementations that last are the ones where IT and finance treat the cost model as a living document rather than a periodic reporting exercise. The ones that fail treat it as a project with an end date. Budget cycles come and go. The model needs to keep updating regardless of whether there is a formal review scheduled.