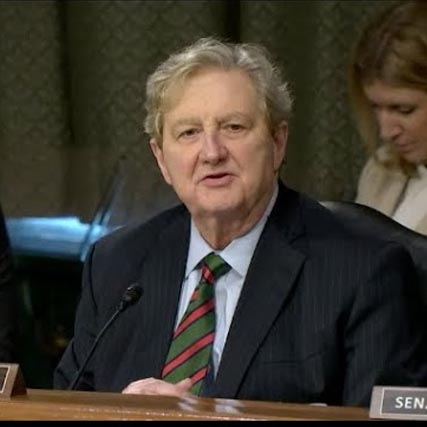
Understanding the Educational Background of John Neely Kennedy
The public often glances at a politician's resume without really examining what their academic training means for their policy positions. John Neely Kennedy's educational path gives you a pretty clear picture of why he approaches economic and regulatory issues the way he does. He went to Tulane for both his undergrad and his MBA, which is a pretty standard route for someone from the Gulf South region aiming for finance and banking. The specific schools he attended shaped his career trajectory in ways that are directly visible in his legislative record. Kennedy earned his Bachelor of Arts degree from Tulane University in 1973. Then he returned to Tulane for graduate study, completing his Master of Business Administration from the A.B. Freeman School of Business in 1976. He also attended Tulane University School of Law but did not complete a Juris Doctor degree. For anyone following John Neely Kennedy Education, the MBA is the centerpiece because that's where his professional identity formed. The law school attendance is often mentioned but less consequential — he left before finishing, which tells you something about how his interests were already pulling him toward banking rather than legal practice. A Tulane MBA in the mid-1970s came out of a program that was heavily grounded in corporate finance and quantitative analysis. The curriculum back then was different from what you see now — less emphasis on the behavioral finance side and more on structural financial modeling. I remember going through a similar program at a Southern business school and the faculty's attitude toward regulation was pretty blunt. They taught us that regulations created friction costs, and that the job of a finance professional was to navigate around them efficiently. That mindset doesn't just disappear when you become a legislator.
When Kennedy votes on banking deregulation or pushes for lighter oversight of community banks, you're seeing that Tulane business school framework in action. It's not some grand ideology he picked up along the way. It's the default position of someone who was trained to view regulation as a cost to be minimized rather than a public good to be optimized.
The Practical Side: What His Background Translated Into
After finishing his MBA, Kennedy went straight into commercial real estate and banking. He worked at several financial institutions in Louisiana and Texas over the next couple of decades before eventually running for office. The transition from banker to senator isn't as smooth as the campaign materials suggest, but his educational foundation gave him a vocabulary and a set of assumptions that carried over pretty seamlessly. One thing people miss when they look at his record is how consistent it is. He's been voting along the same lines on financial issues since the early 2010s. That's not because he never changed his mind — it's because his education gave him a pretty stable analytical framework. When a new financial regulation comes up, he already knows how to evaluate it through the lens he learned at Freeman. You don't need to revisit the fundamentals every time a new bill drops.
Get the Full Details

Common Misconceptions About His Academic Background
There's a persistent narrative online that Kennedy lacks the academic credentials to meaningfully engage with complex economic policy. That's not really accurate. An MBA from a solid regional business school is a professional degree, and it covers the quantitative and analytical material you need for most financial legislation. Where he falls short is in having a formal legal or economics doctorate, but most members of Congress don't have those either. The real gap is more about depth in public policy theory than about basic numeracy or understanding of financial systems. Another misconception is that his law school attendance makes him a legal expert. He attended for roughly two years and left. That's enough to give him literacy in legal reasoning, but it doesn't qualify him to draft legislation from scratch. In practice, this showed up during debates over financial regulatory reform when Kennedy would propose amendments that had the right intent but the wrong statutory language. His staff had to redo the technical sections pretty frequently. It's a minor thing but it's worth noting if you're trying to evaluate how much weight to give his specific policy proposals versus his general ideological positioning.
What This Means for Evaluating His Record
If you're looking at Kennedy's education and trying to predict how he'll vote on future financial legislation, the Tulane MBA is your best single data point. It tells you he'll default toward deregulatory positions, prefer market-based solutions over direct government intervention, and be skeptical of new compliance frameworks — especially ones that affect regional banks. Those tendencies are baked in at this point and unlikely to shift significantly regardless of what happens in the broader political environment. The law school gap matters more than most people realize when it comes to understanding his limitations. He's competent at talking about financial policy but not particularly skilled at the technical craftsmanship that goes into writing effective legislation. That's the honest assessment, and it's the one you should carry with you whenever you see him proposing a new financial reform initiative.