Why A SWOT Analysis On Johnson And Johnson Actually Matters Right Now
You can run a SWOT on any publicly traded company, but Johnson And Johnson Swot Analysis is genuinely useful at this moment because the company is sitting in a weird transitional phase. Their prescription drug division hit a major wall with the Qdawn trial failure for opdivo, which knocked billions off their valuation. At the same time, the consumer health spinoff (Kenvue) is fully operational, and the talc litigation overhang is still draining legal reserves. Running a clean SWOT right now forces you to look at the company as two different businesses instead of one monolith, which most quick analyses miss. Here is how I actually build one from scratch rather than just pulling data from a Bloomberg terminal. First, you separate the segments. J&J operates through three distinct pillars: Pharmaceutical, MedTech, and Consumer (post-Kenvue spinoff, the Consumer segment is significantly smaller). Most published SWOTs lump these together and produce garbage conclusions. You need to assess strengths and weaknesses by segment first, then synthesize. I start by pulling the latest 10-K and 10-Q, specifically the MD&A section and the legal contingencies footnote. The legal footnote at J&J runs about forty pages and contains more actionable intelligence than the stock price movement. I track the total litigation reserve against annual revenue to get a sense of exposure. As of their most recent filings, the talc-related reserves sit around 10 to 12 billion dollars, which matters when you're evaluating their cash flow strength as a "strength" item.
Strengths
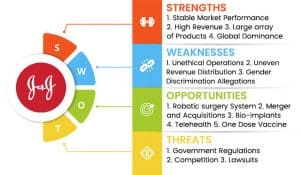
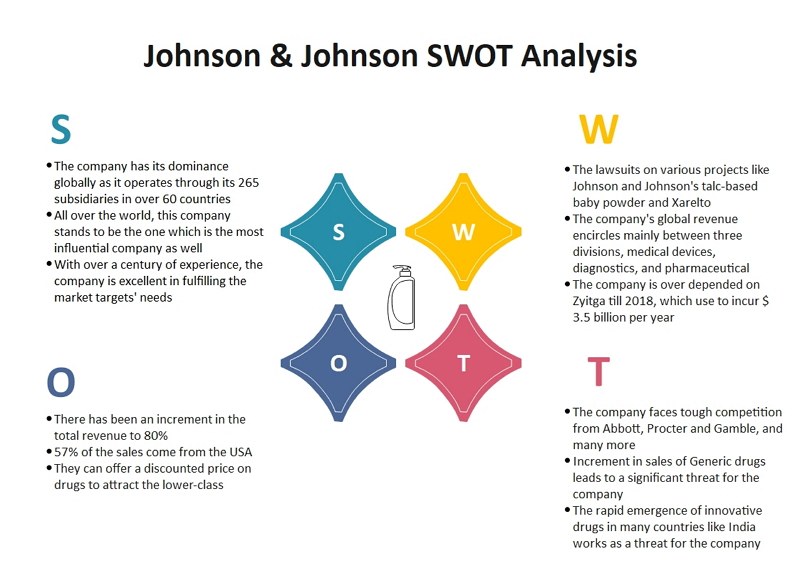
The Pharmaceutical pipeline remains the core strength. Key products like Darzalex, Stelara, and Imbruvica generate consistent revenue. Stelara alone has been their cash cow for years, even with biosimilar competition approaching. Their R&D spend typically runs between 13 and 14 billion annually, which is meaningful relative to peers. The brand equity is also not trivial. A hospital system trusts the J&J name on surgical devices and pharmaceuticals, which creates pricing power that doesn't show up in simple margin analysis. Their balance sheet carries an AAA rating, which means borrowing costs stay low even during periods of market turbulence. This matters more than analysts usually credit because it lets J&J maintain dividends through downturns. They have raised their dividend for sixty-one consecutive years, placing them in the dividend aristocrat category. For income-focused institutional investors, that streak is a genuine moat.
Weaknesses
The patent cliffs are real and they are accelerating. Stelara faces biosimilar erosion starting in late 2023 and ramping through 2025. Darzalex follows a similar trajectory into 2026. When multiple blockbusters approach expiry within a narrow window, revenue management becomes extremely difficult, and J&J is currently in that window. Their top-line growth has been flat to mildly negative over the past two years, which is unusual for a company of this scale. Another structural weakness is pipeline concentration risk. While the overall portfolio is broad, the pharmaceutical revenue relies heavily on a small number of oncology and immunology products. Losing exclusivity on even one of those creates a measurable hole. The MedTech division, while large, has faced margin pressure from supply chain disruptions and pricing concessions in Europe. These are not catastrophic weaknesses but they are persistent ones.
Get the Full Details

Opportunities
The acquisition strategy is the most tangible opportunity. J&J's purchase of Informai Sciences for roughly 16.3 billion dollars signals a deliberate pivot toward oncology-focused digital health and AI-driven drug discovery. If that integration works over a five-year horizon, it could meaningfully improve clinical trial efficiency. Whether it works is an open question, but the strategic direction is clear. The Kenvue spinoff itself created optionality. J&J can now focus capital allocation on higher-margin pharmaceutical and MedTech businesses without managing low-growth consumer brands. This also opens the door to more aggressive M&A in the pharma space since the balance sheet is cleaner. The consumer health market remains massive, but competing in it requires a different operational model than J&J was built for. Emerging market expansion in oncology treatments presents another opportunity. India, Southeast Asia, and Latin America represent growing markets for their cancer therapies, and J&J's existing distribution network gives them an advantage over smaller biotech firms trying to enter those regions.
Threats
Regulatory and litigation risk is the dominant threat. The talc cases continue to produce adverse verdicts, and while settlements are structured to manage cash outflow, the precedent effect matters. New plaintiffs' firms are testing whether J&J's safety disclosures were adequate, which could expand the liability universe beyond current estimates. The DOJ has also shown increased interest in pharmaceutical pricing practices, which adds another layer of regulatory exposure. Generic and biosimilar competition is intensifying across their entire oncology portfolio. The UK's NICE guidelines have become stricter on cost-effectiveness thresholds, which directly impacts J&J's pricing power in Europe. Their drug pricing models are calibrated for the US market, where reimbursement frameworks are more favorable, so international headwinds are real. Macroeconomic factors also create threat. Healthcare spending growth has decelerated in several key markets. Hospital budgets are tighter post-COVID, and procurement organizations are pushing harder on device pricing. This compresses MedTech margins independently of any J&J-specific operational issues.
How I Actually Use This Analysis In Practice
I built a SWOT template for J&J that I revisit quarterly rather than annually. The standard academic approach treats SWOT as a static document, which is useless for a company this size. Every quarter, I update the litigation reserve figures, check the latest pipeline trial results from ClinicalTrials.gov, and note any executive changes. The MedTech segment reports separately now, so I track their revenue and margin independently from Pharma. One specific problem I encountered last year was trying to value the impact of the Kenvue spinoff on J&J's credit profile. The credit rating agencies took different approaches. Moody's was more conservative about treating the spinoff as net-positive for leverage metrics, while S&P initially discounted it. I resolved this by building a scenario model that compared J&J's debt-to-EBITDA at three different assumptions for Kenvue's ongoing cash contribution, and the range was wider than either rating agency published. That gap turned out to be the real signal, not the headline ratings themselves. Another practical consideration is that SWOT analysis does not tell you when to buy or sell a stock. I have seen too many reports that present a SWOT as an investment recommendation. It is a framing tool. The strengths and opportunities are only actionable if you understand the timeline. Stelara's biosimilar erosion will take approximately eighteen months to significantly impact revenue. The Informai Sciences integration could deliver results in three to five years or it could fail entirely. A SWOT helps you organize that uncertainty, but it does not eliminate it.
If you want to replicate this, the best data sources are the quarterly earnings calls, the SEC filings, and the pipeline tracker on J&J's investor relations page. The litigation reserve schedule in the annual report is the single most underutilized data point in public SWOT analyses. Reading just that footnote will give you a clearer picture of the company's actual risk profile than any analyst summary.