Most people try to treat journaling like a productivity hack. It isn't one. It's a tracking method, nothing more, and the people who get value from it are the ones who stop expecting inspiration and start expecting data.
Journal Monthly is essentially a periodic review system where you track your income, expenses, savings, and debt payments in a structured layout once per month. The format can be a spreadsheet, a notebook, a dedicated app, whatever. The mechanism is what matters. You commit to sitting down at the end of each month and forcing yourself to account for every dollar that moved.
I started doing this around 2018 because my personal finances were a mess I refused to acknowledge. I had no idea where my money went each month. Bank statements showed the end balance but not the pattern. A friend at work was using a monthly spreadsheet template and I borrowed the basic structure. That was five years ago. I still do it, though I've changed the format twice since then.
Getting Started With Journal Monthly
You need a few sections at minimum. Income, fixed expenses, variable expenses, debt payments, savings contributions, and a category for anything that doesn't fit neatly elsewhere. Some people add rows for yearly subscriptions split monthly. Others separate discretionary spending from essentials. Start simple and expand later.
Here's the practical workflow. At month end, pull your bank and credit card statements. Log every transaction into the relevant section. Do not skip the coffee purchases or the small subscriptions. Those are the ones that hide budget leaks. Once everything is recorded, calculate your net position: total income minus total outflows. Compare it to last month. Note what changed and why.
The whole process usually takes me about twenty minutes if my accounts are organized, maybe forty-five if I'm behind on reconciling a credit card. I've seen people spend two hours doing this. That's a sign they're not capturing transactions in real time and trying to reconstruct a month of data from memory. Do not do that.
I use a Google Sheets template I built myself. Each month gets its own tab. Columns for date, description, amount, category, and notes. The notes column is where I flag anomalies — a one-time repair, a bill I forgot about, a refund that came in late. Without that column, the data looks clean but you lose context.
A specific problem I ran into: I noticed my "groceries" category kept creeping up by about sixty dollars each month even though I wasn't eating any different. I traced it through the notes column and found a single recurring $22 charge I'd forgotten about — a meal kit delivery I signed up for on a trial and never cancelled. It appeared in my grocery category because the merchant name didn't trigger my auto-categorization rule. Moving that transaction to its own line item dropped my grocery spend back to normal. This kind of thing is invisible unless you actually look at the granular data.
Where Journal Monthly Falls Apart
The method has real limitations and people rarely talk about them honestly.
First, it only captures what happened last month. You'll never see trends until they've already unfolded. If you need early warning signals, you should supplement this with weekly check-ins, not just monthly reviews. Monthly is for big-picture accounting. Weekly is for course correction.
Second, the accuracy depends entirely on your discipline. I've had months where I missed three or four transactions because I was lazy about pulling receipts or checking my phone banking app. The resulting journal entry was wrong by a few hundred dollars. It didn't break the system but it made the comparison to the prior month misleading. The fix is setting a standing calendar reminder for the last working day of each month and treating it like a non-negotiable appointment.
Third, journaling by hand or in a disconnected document creates friction. Every time you switch context to remember where you saved your notes, you're more likely to skip the session entirely. I learned this the hard way after missing two consecutive months because my paper journal ended up buried under a pile of bills. Switching to a cloud spreadsheet eliminated that failure mode.
A counter-intuitive point that most beginner guides miss: the act of recording the transactions is less valuable than the comparison step. Writing everything down is routine data entry. The insight comes when you force yourself to explain the delta between this month and last month. Why did utilities spike? Did savings drop because of something predictable or random? What assumptions from the previous month turned out to be wrong? That analysis is where Journal Monthly earns its keep. Without it, you're just maintaining a ledger.
Tools and Templates
You don't need software to do this. A notebook works. A PDF printout works. But spreadsheets give you formulas that catch calculation errors before you submit your review. Excel and Google Sheets both handle this fine. Numbers on a Mac works too if you're in that ecosystem.
There are also purpose-built apps likeYNAB, Simplifi, and Monarch Money that automate much of this work. They pull transaction data directly from your accounts and categorize it automatically. If you want full automation, those are worth looking at. Journal Monthly as a standalone concept is most useful when you want manual control over categorization and commentary. Automation strips away the granular notes and forces everything into preset buckets that may not match your actual spending behavior.
For a free starting point, search for "Journal Monthly template spreadsheet" and you'll find dozens of community-shared versions. Pick one that matches your financial situation rather than the one with the most features. A minimalist template you actually use beats a complex one you abandon after two months.
Common Mistakes People Make
Overcomplicating the category structure on day one. When I first set this up I had twenty-three categories. I spent more time maintaining the system than learning from it. I cut it down to ten and everything clicked.
Ignoring negative numbers. Income minus expenses should sometimes be negative. That's a valid data point. I've seen people reclassify expenses to make the number look better. Don't do that. The whole point is honesty.
Failing to close out the previous month before starting a new one. I used to roll unreviewed transactions forward into the new month to save time. That created a compounding error effect that took three months to catch. Always reconcile the full month before moving on.
The method isn't elegant. It's repetitive and occasionally tedious. It also catches problems early enough that you can fix them before they become emergencies. I'd rather spend twenty minutes a month on this than discover a four-thousand-dollar shortfall in April.
Gallery Journal Monthly
Templates | Bullet journal monthly layout template
Monthly Bullet Journal Spread Ideas – PBZD
Bullet journal ideas templates | Monthly planning bullet journal, Bullet journal monthly planner ...
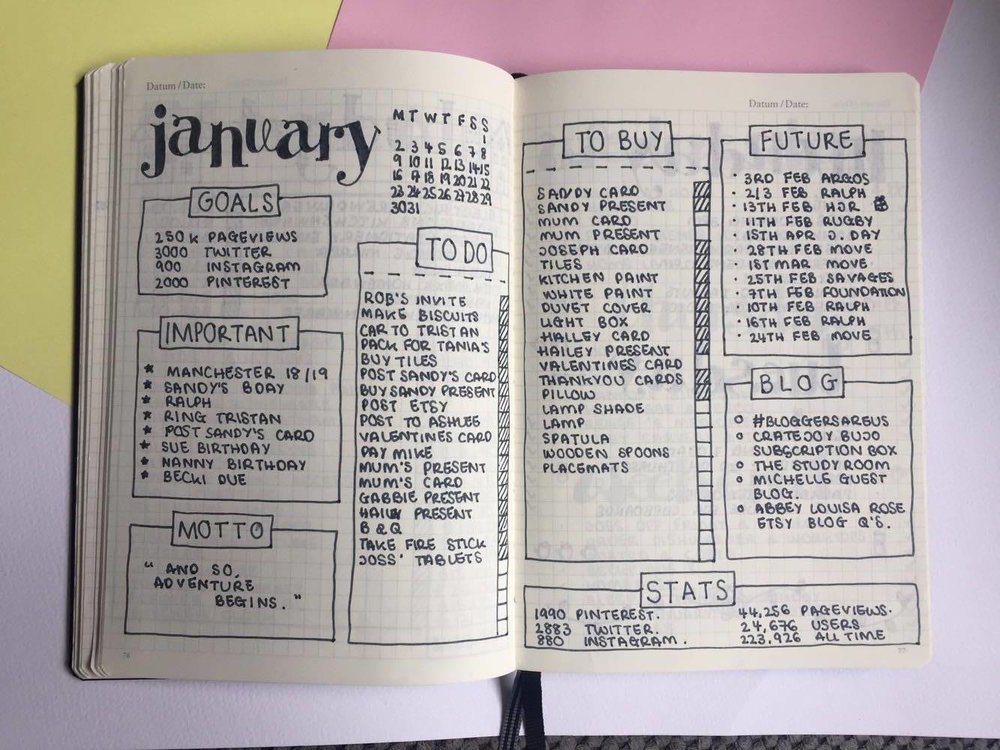
Bullet Journal Monthly Spreads - The Ultimate Guide to Rock Your Month!
Beautiful Journal Monthly Spread Spiritual Bullet Ideas Best Size For