Why Chapter 1 of Key Wiley Accounting Principles Keeps People From Finishing It
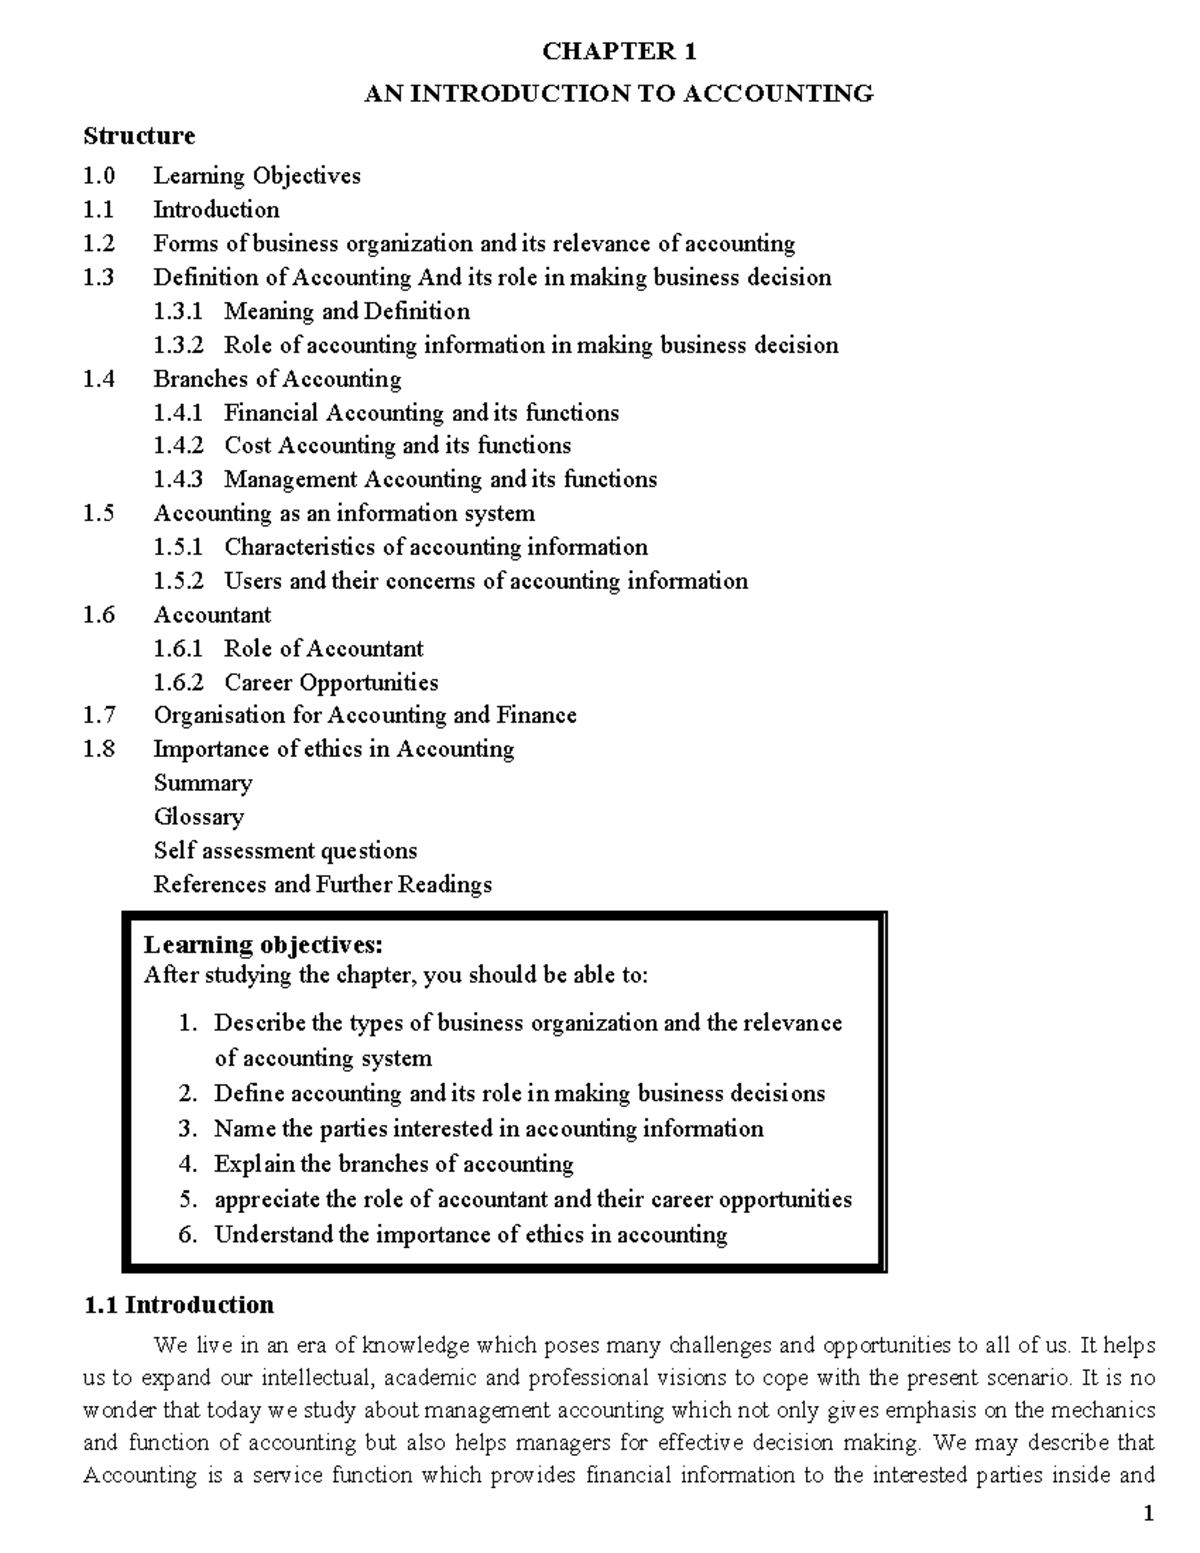
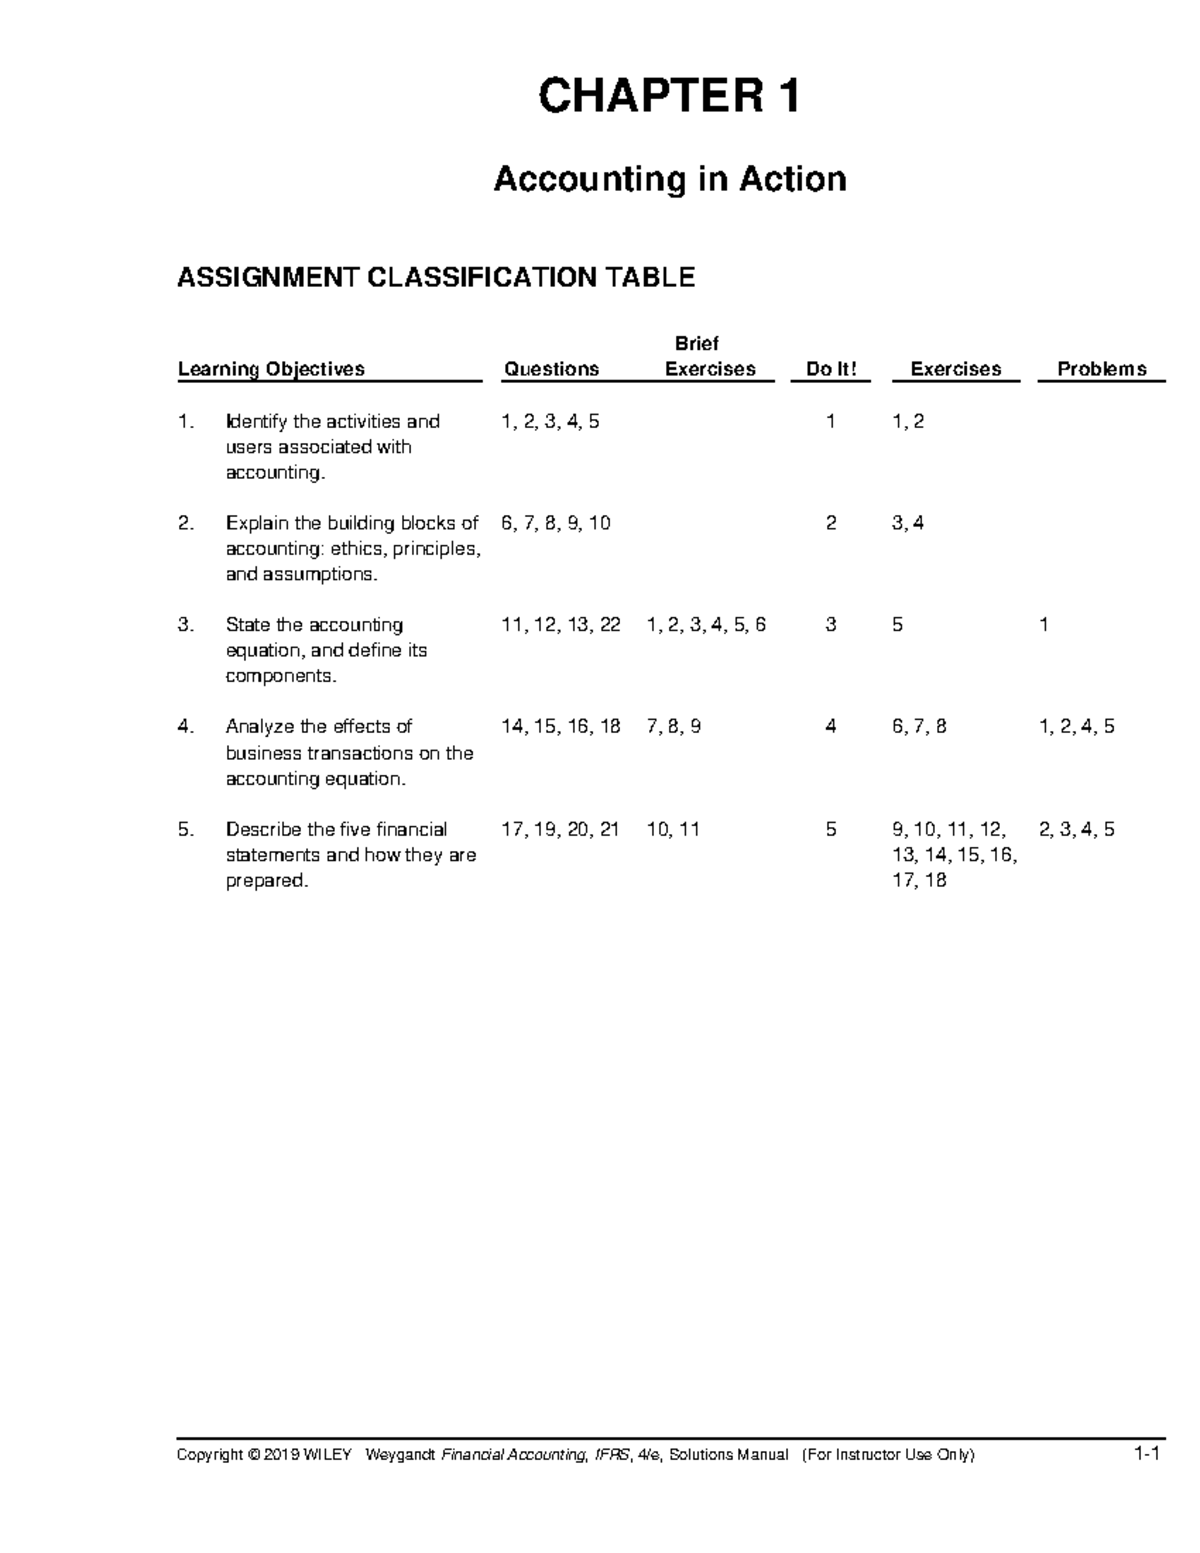
I've been tutoring students through this book for years, and honestly, the first chapter is where most people quietly give up. Not because it's hard. Because nobody explains why they need to read it before touching any journal entry. Chapter 1 doesn't teach you to debit or credit anything. It teaches you what the whole system is even trying to do. Skip it and you'll spend the rest of the semester memorizing rules that make no sense. The textbook sits at the intersection of introductory accounting and everything that comes after. Chapter 1 alone takes roughly two to three hours to read properly, including the end-of-chapter problems. You can rush through it in forty-five minutes, but then the later chapters hit you with assumptions you never actually absorbed. The material covers the accounting environment, the role of financial reporting, the standard-setting bodies (FASB, IASB, SEC), and the conceptual framework that underpins every single entry you'll make from here on out. That last part is the one students gloss over, and it costs them later.
Key Wiley Accounting Principles Chapter 1: What It Actually Tests You On
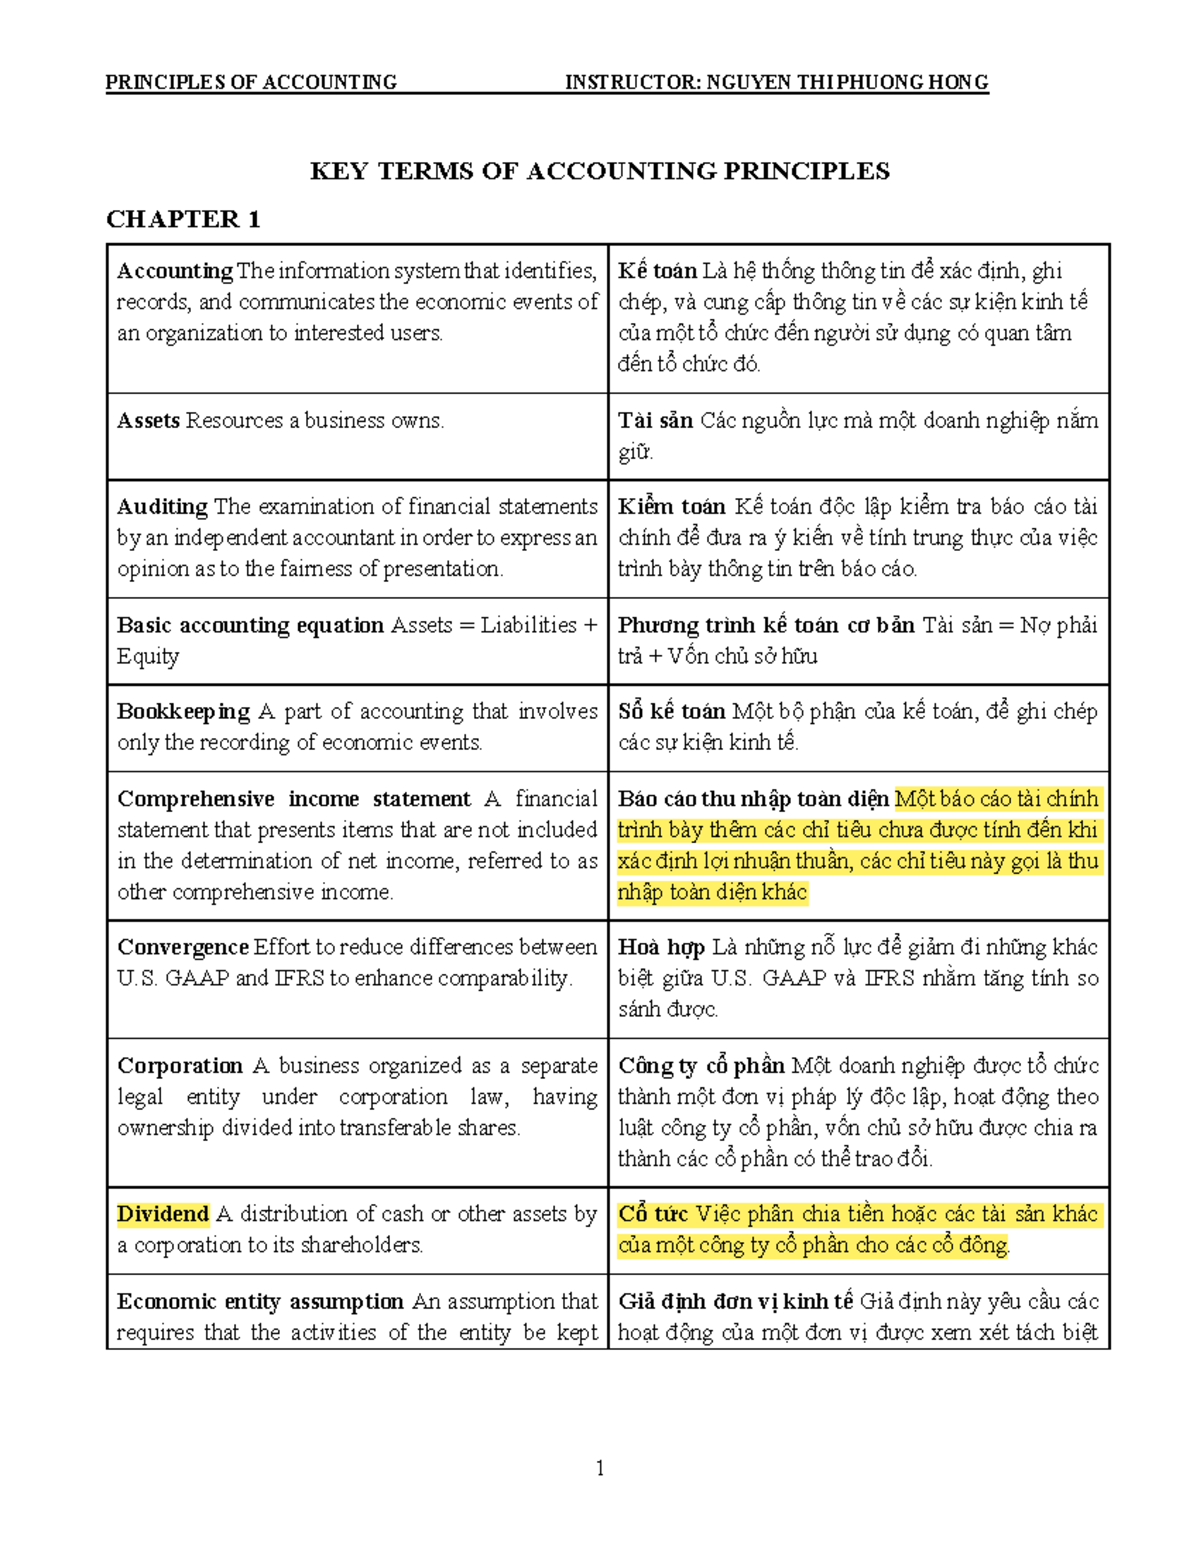
When instructors build exams around this chapter, they don't ask "what does FASB stand for." They ask questions that seem simple but require you to understand the hierarchy of authoritative guidance. Here's what I see trip people up repeatedly. The conceptual framework section isn't decorative. It defines what an asset actually is, what liabilities are, and what equity means in a way that matters when you're facing a transaction you've never seen before. Revenue recognition, matching principle, going concern assumption — these aren't just vocabulary terms. They're the decisions you'll be making when the textbook stops giving you clear instructions. I had a student last semester who couldn't figure out why a prepaid insurance entry wasn't being recorded as an expense right away. The answer was in Chapter 1, buried in the discussion of the matching principle and the accrual basis of accounting. She'd skimmed past it because it looked like filler. Here's the thing nobody tells you about this chapter: the qualitative characteristics of useful financial information — relevance and faithful representation — are the filter you should run every accounting decision through. When you're stuck on whether to record something a certain way, ask yourself whether the treatment makes the information more relevant and whether it faithfully represents the economic event. It sounds abstract until you're on an exam and the question is deliberately ambiguous. Then it becomes your only tool.
Another counter-intuitive point is how the textbook treats GAAP versus IFRS early on. Many students assume this is just a side note. It's not. Chapter 1 lays out the convergence effort and the current state of differences. If you're planning to work internationally or even in a large US firm, understanding that the framework isn't identical matters. The SEC enforces US GAAP. Public companies outside the US use IFRS or their own national standards. When Wiley gets to chapter four and beyond, those distinctions start showing up in problem sets. You'll wish you'd paid attention now.
Get the Full Details
How to Actually Study This Chapter Without Wasting Time
Read the chapter once straight through without highlighting anything. Most people start marking text immediately, which fractures their comprehension. Get the narrative first. The accounting cycle, the financial statements overview, the standard-setting process — read it like a story. Then go back and work the examples in the textbook. Don't skip them. Wiley builds its problems around the examples. If the example shows how income statements flow from trial balances, do every single one. The problems at the end are where the real testing happens, and they assume you've internalized the flow. Here's a specific edge case I ran into with a student working through the chapter problems. There's a question about classifying a warranty liability. The textbook's example treats it straightforwardly, but the practice problem introduces a scenario where the warranty period extends beyond the current fiscal year and the estimation method changes mid-year. Standard introductory coverage barely touches this. The workaround is to go back to the matching principle section and trace how the liability is derived — estimated cost of future repairs matched against the revenue from the sale. Once you see it that way, the entry isn't a mystery. It's just applying the principle to a slightly messier situation. I've seen this exact variation show up on midterm exams at three different universities.
Another area where students lose points involves the hierarchy of accounting literature. Chapter 1 introduces FASB Statements, Accounting Standards Updates, and CAP opinions. The testable detail is knowing which source carries the most weight. ASUs supersede older FASB Statements. CAP opinions are grandfathered only if they haven't been explicitly superseded. I recommend making a one-page reference sheet that maps each source to its authority level. It takes ten minutes and saves you from second-guessing yourself during exams.
Common Pitfalls and Where This Material Falls Short
The biggest limitation of Chapter 1 in Key Wiley Accounting Principles is that it presents the conceptual framework as clean and settled. It isn't. The definitions of assets and liabilities have been contested for decades. The revenue recognition standard was completely overhauled with ASC 606, and while Chapter 1 touches on it, the depth is minimal for an introductory text. If you want a fuller picture, you'll need supplemental reading. The textbook gives you the framework, not the ongoing debates. Another downside is the pacing. The section on standard-setting bodies reads like a government textbook. It's accurate but dense, and students often zone out. You don't need to memorize the procedural history of how FASB was formed. You need to know that FASB sets US GAAP, the IASB sets IFRS, and the SEC enforces reporting for public companies. Everything else is background noise for a first course. The end-of-chapter problems vary in quality. Some are solid and directly reinforce the material. Others feel generated to fill space. I've noticed a pattern where the multiple-choice questions are more reliable than the short-answer or computational problems in this particular chapter. When the computational problems get weird — like combining multiple concept checks into one question — it's usually a sign the author was trying to force comprehensiveness over clarity. Skip the overly complex ones on a first pass and come back to them later.
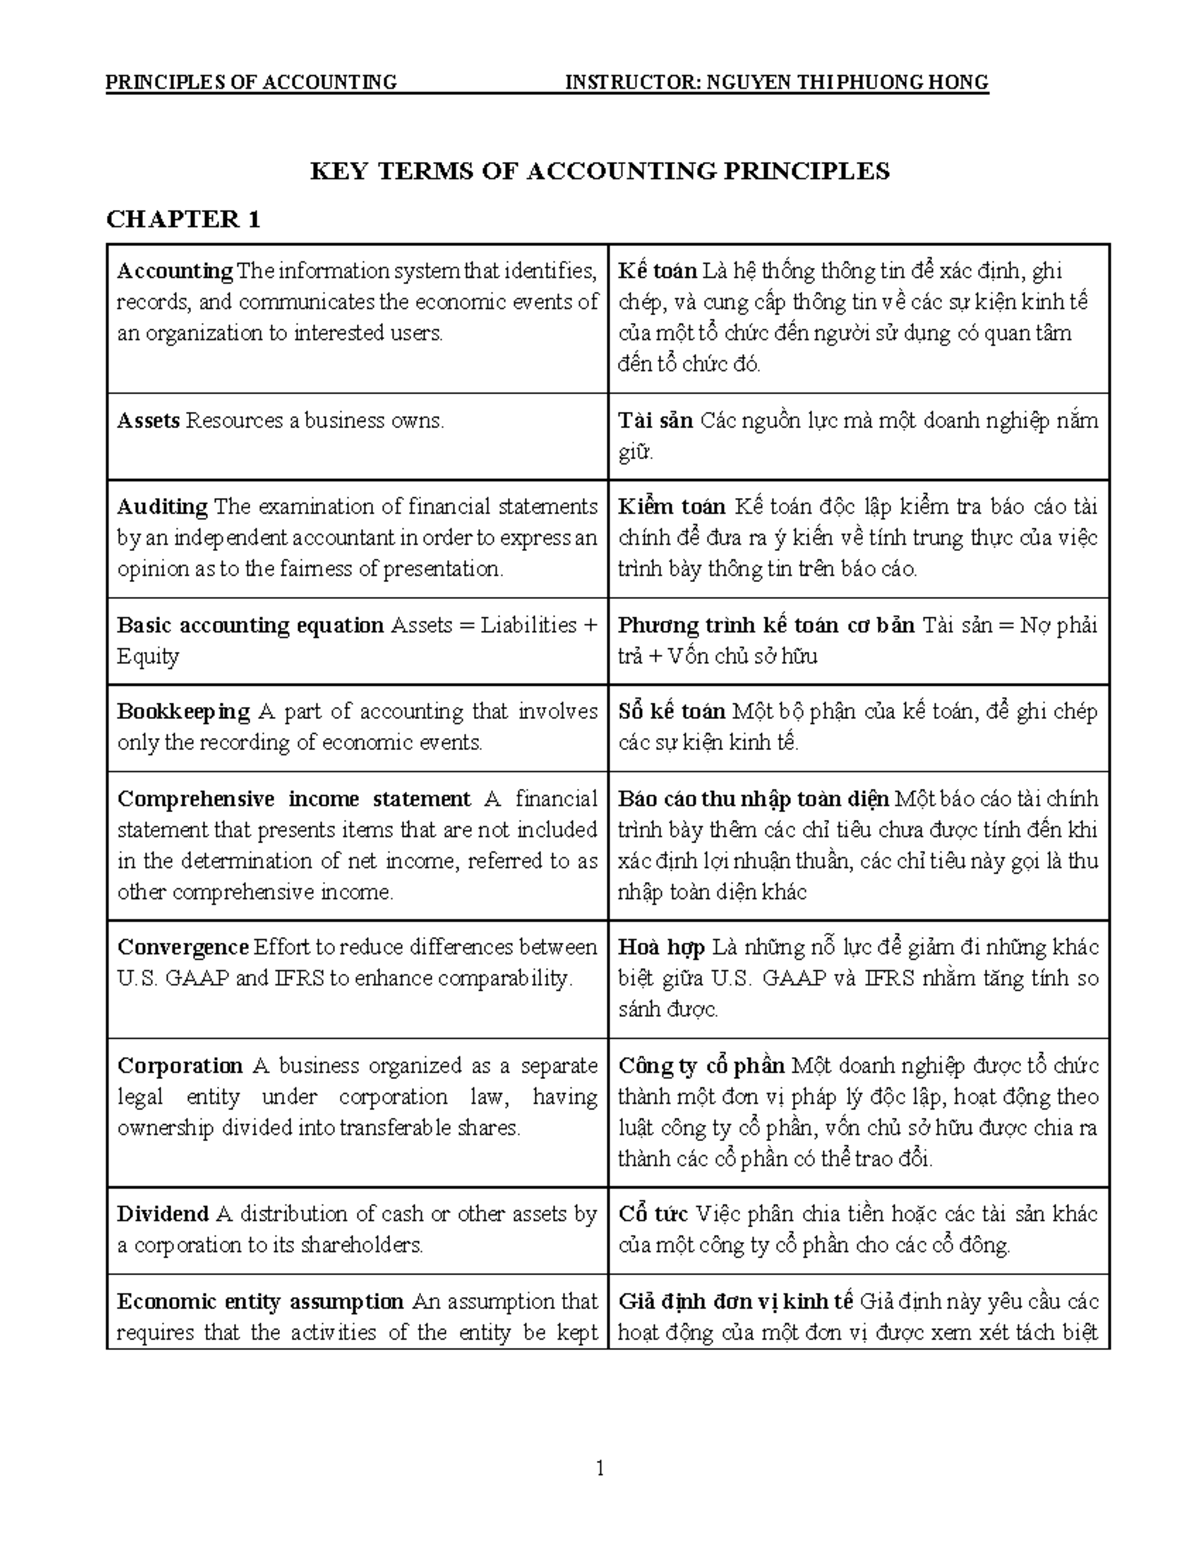
If you're looking for a download or full text of Key Wiley Accounting Principles Chapter 1, I can't help with that. The textbook is copyrighted material. What I can say is that your campus library almost certainly has a copy, and the online version through WileyPlus often includes the chapters as part of your course access. If you're using the book for a class, check your syllabus or ask your instructor about digital access. Most of them have it set up already. The practical takeaway is this: Chapter 1 is foundational, not filler. It establishes the vocabulary and the logic structure you'll use for the entire course. Read it slowly the first time. Work through the examples. Pay attention to the conceptual framework section more than any other part. And don't treat the standard-setting discussion as something to power through — know the players and their roles, and move on.