The whole process starts with identifying your reporting units. That is the step most people rush through and then spend weeks untangling later. A reporting unit is either an operating segment or one level below it, depending on how your business is structured. If you have three business divisions and each division has separate management tracking discrete financials, that is three reporting units. If the divisions are managed as a single block with no sub-segment visibility, it is one. Getting this wrong early makes the rest of the exercise far more complicated than it needs to be.
Once you have your reporting units locked in, the first step is the quantitative assessment. You compare fair value against carrying amount, including goodwill. Fair value is not book value. It is what a market participant would pay, usually estimated through discounted cash flow analysis or comparable transaction multiples. The guidance itself lays out both approaches and explains when each is appropriate. Most companies default to DCF because it gives more control over the assumptions, but market-based approaches can be faster when you have active comparable companies in the same space.
I spent a fiscal year dealing with a situation where we had twelve reporting units from a series of acquisitions over five years. Eight of them showed healthy fair value margins above carrying amount on paper, but two had margins under 8 percent. The obvious answer would have been to write something down, but what actually matters is the gap. When fair value is that close to carrying amount, small changes in your discount rate assumption or your terminal growth rate flip the result entirely. I ran the numbers three ways — one, two, and three percent variation in the WACC — and the fair value swung by roughly twenty percent either direction. In the end, we documented the sensitivity analysis thoroughly and concluded no impairment was required because even the downside scenario kept us above the threshold. That documentation turned out to be critical during the audit.
The second step, which only triggers if fair value is below carrying amount, is the implied fair value calculation. You allocate the reporting unit's fair value to all its assets and liabilities as if it were a purchase price allocation, then compare the resulting goodwill to the recorded goodwill. The difference is your impairment loss. Most people mess this up by skipping the step-by-step allocation or by using rough estimates instead of actual balance sheet data. It is not optional to do it properly. The standard requires you to treat the reporting unit as if it were being acquired, and that means mapping every identifiable intangible, every liability, and every asset to its fair value.
What the Guide Covers Well
The Kpmg Goodwill Impairment Guide walks through the ASC 350 framework systematically. It covers the qualitative assessment option, which allows companies to skip the quantitative test entirely if they determine it is more likely than not that fair value exceeds carrying amount. It explains when a qualitative assessment is reasonable and when you should move straight to the numbers. The guide also addresses interim testing requirements — events that trigger a reassessment between annual tests, like a significant decline in market conditions, a material change in the business environment, or a sustained decrease in share price.
One thing beginners consistently get wrong is the annual testing date. You pick a date and stick with it year over year unless there is a legitimate reason to change it. Changing the date mid-cycle can raise eyebrows with auditors, and if you have multiple reporting units, you can test them on different dates within the same fiscal year. I have seen companies save weeks of work simply by staggering their testing schedule rather than trying to complete everything in a single concentrated period.
Where It Gets Messy
The guide assumes a relatively straightforward corporate structure. It does not always address how to handle share-based compensation allocations across reporting units, or how to deal with intercompany transactions that blur the lines between segments. In my experience, the trickiest part is allocating corporate-level assets and liabilities to reporting units. If your headquarters building is carried on the balance sheet at the parent level and not allocated down, your carrying amount comparison becomes unreliable. Some companies allocate a portion of corporate assets to each reporting unit based on revenue or headcount, while others do not allocate at all and accept the risk that auditors will challenge the approach. There is no universally correct answer here, which is exactly why the guidance can feel incomplete in practice.
Another issue is the discount rate. The guide recommends using a weighted average cost of capital derived from market data, but choosing the right beta, the right risk-free rate, and the right market risk premium can shift your fair value estimate by a large margin. I have used industry-specific betas from Bloomberg, but I have also seen situations where using a comparable company average produced a materially different WACC than using the target company's own capital structure. The guide acknowledges both approaches but does not tell you which one to prefer when they disagree. You just have to pick one and defend it consistently.
Common Mistakes
Using last year's discount rate without updating it for current market conditions is the most frequent error I encounter. Interest rates have moved significantly since 2021, and companies that carried forward a 9 percent WACC into a 2024 test without recalibration were producing fair value estimates that were wildly overstated. Another mistake is assuming that a positive fair value in one year guarantees no impairment next year. Impairment testing is not cumulative in that way. Even if you passed last year, you still have to test again this year, and market conditions can deteriorate fast enough to erase a previously comfortable margin.
The guide also does not spend much time on the interaction between goodwill impairment and tax considerations. If your goodwill carries a tax basis, the deductible amount affects your net carrying value differently than non-deductible goodwill. Some companies forget to adjust their carrying amount calculations for tax benefits, which can lead to an understated impairment or an overstatement of remaining goodwill on the balance sheet.
Practical Workflow
Start with your financial statements and extract the carrying amount for each reporting unit, including any allocated goodwill. Pull your latest audited financials and any interim balance sheet updates. Build or update your DCF models for each unit, making sure the discount rate reflects current conditions. Run sensitivity analysis on at least two key assumptions — typically the WACC and the terminal growth rate. Compare fair value to carrying amount for each unit. Document everything in a format your auditors will accept, with clear citations to the assumptions behind each number. If any unit fails the first step, proceed to the implied fair value calculation before recording any impairment charge.
The process typically takes between two and six weeks for a mid-sized company with four to six reporting units, depending on how clean the underlying data is and whether your DCF models are already built from prior years. Companies that maintain a rolling impairment template throughout the year often cut that down to one to two weeks at test time. Building the model from scratch every year is inefficient and introduces unnecessary error risk.
Gallery Kpmg Goodwill Impairment Guide
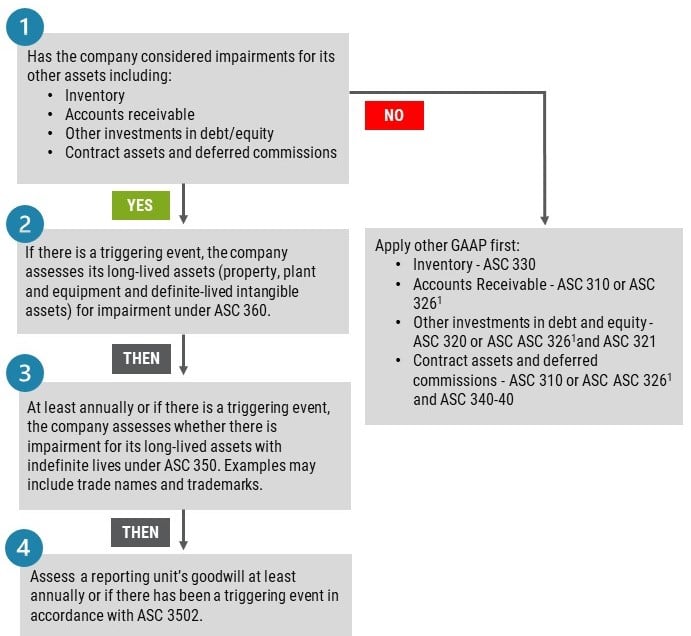
Goodwill Impairment Testing Guide, Examples, & Accounting Tips
Understanding Asset Impairment Guidelines | PDF | Book Value | Goodwill (Accounting)
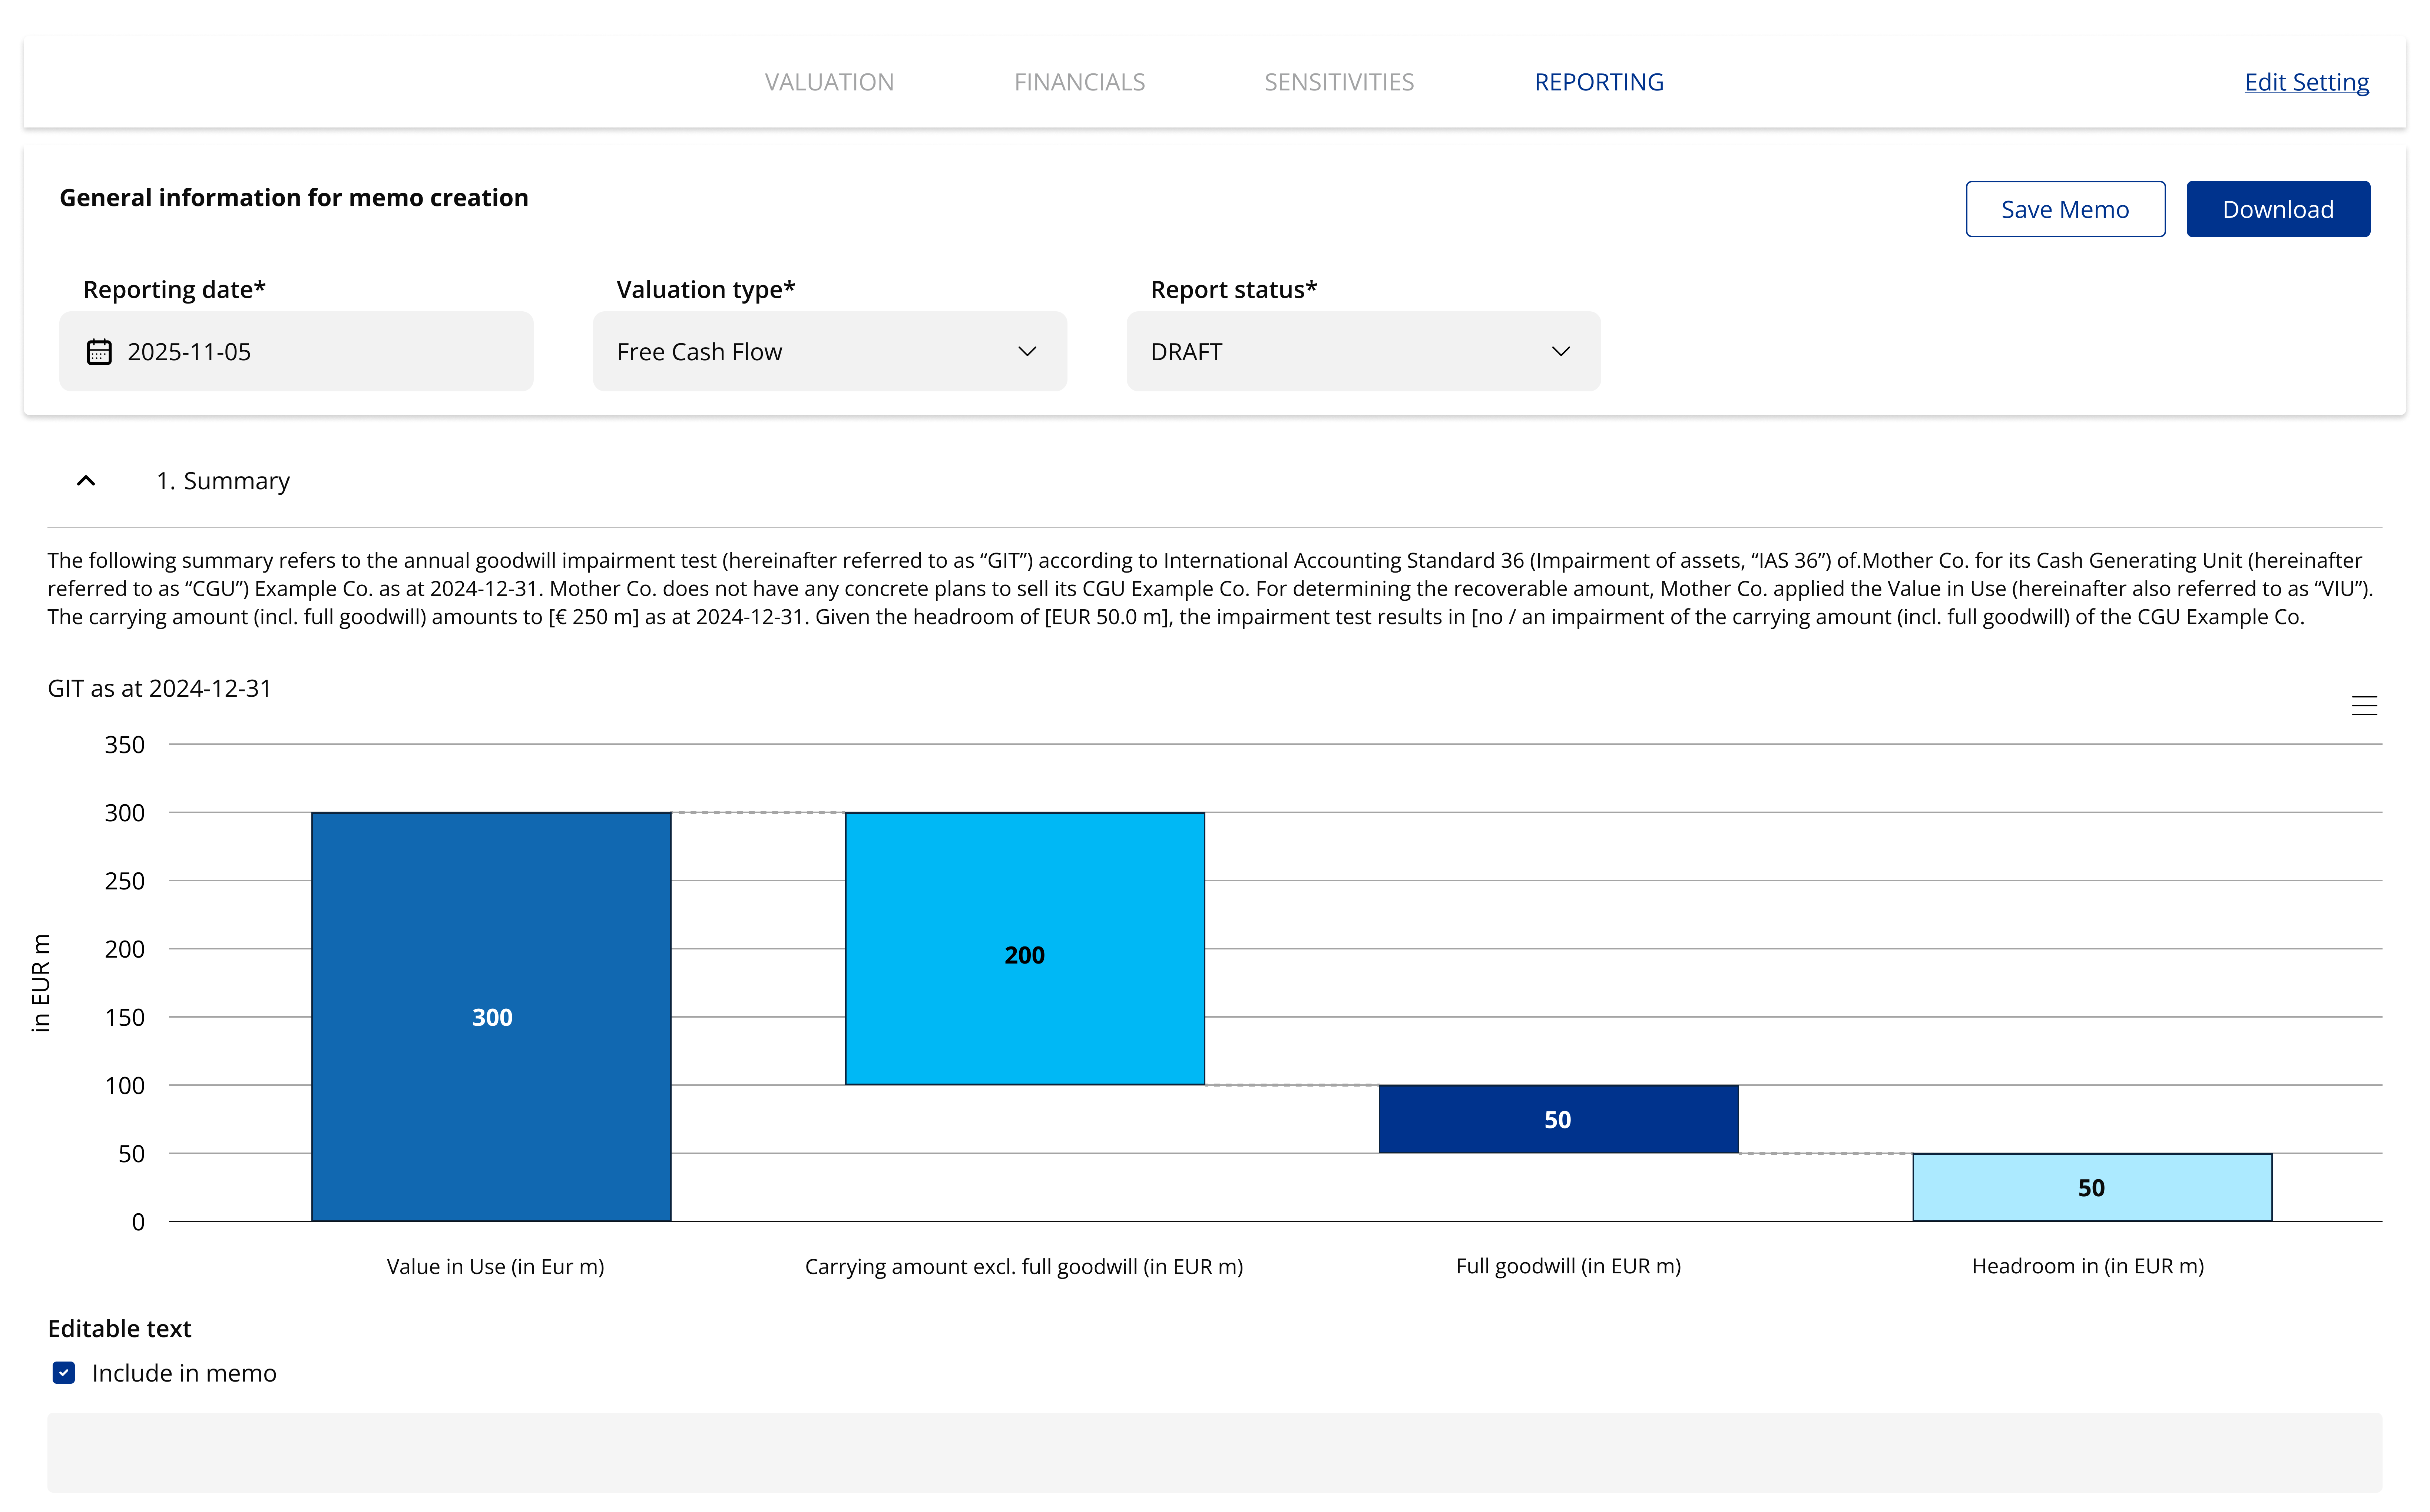
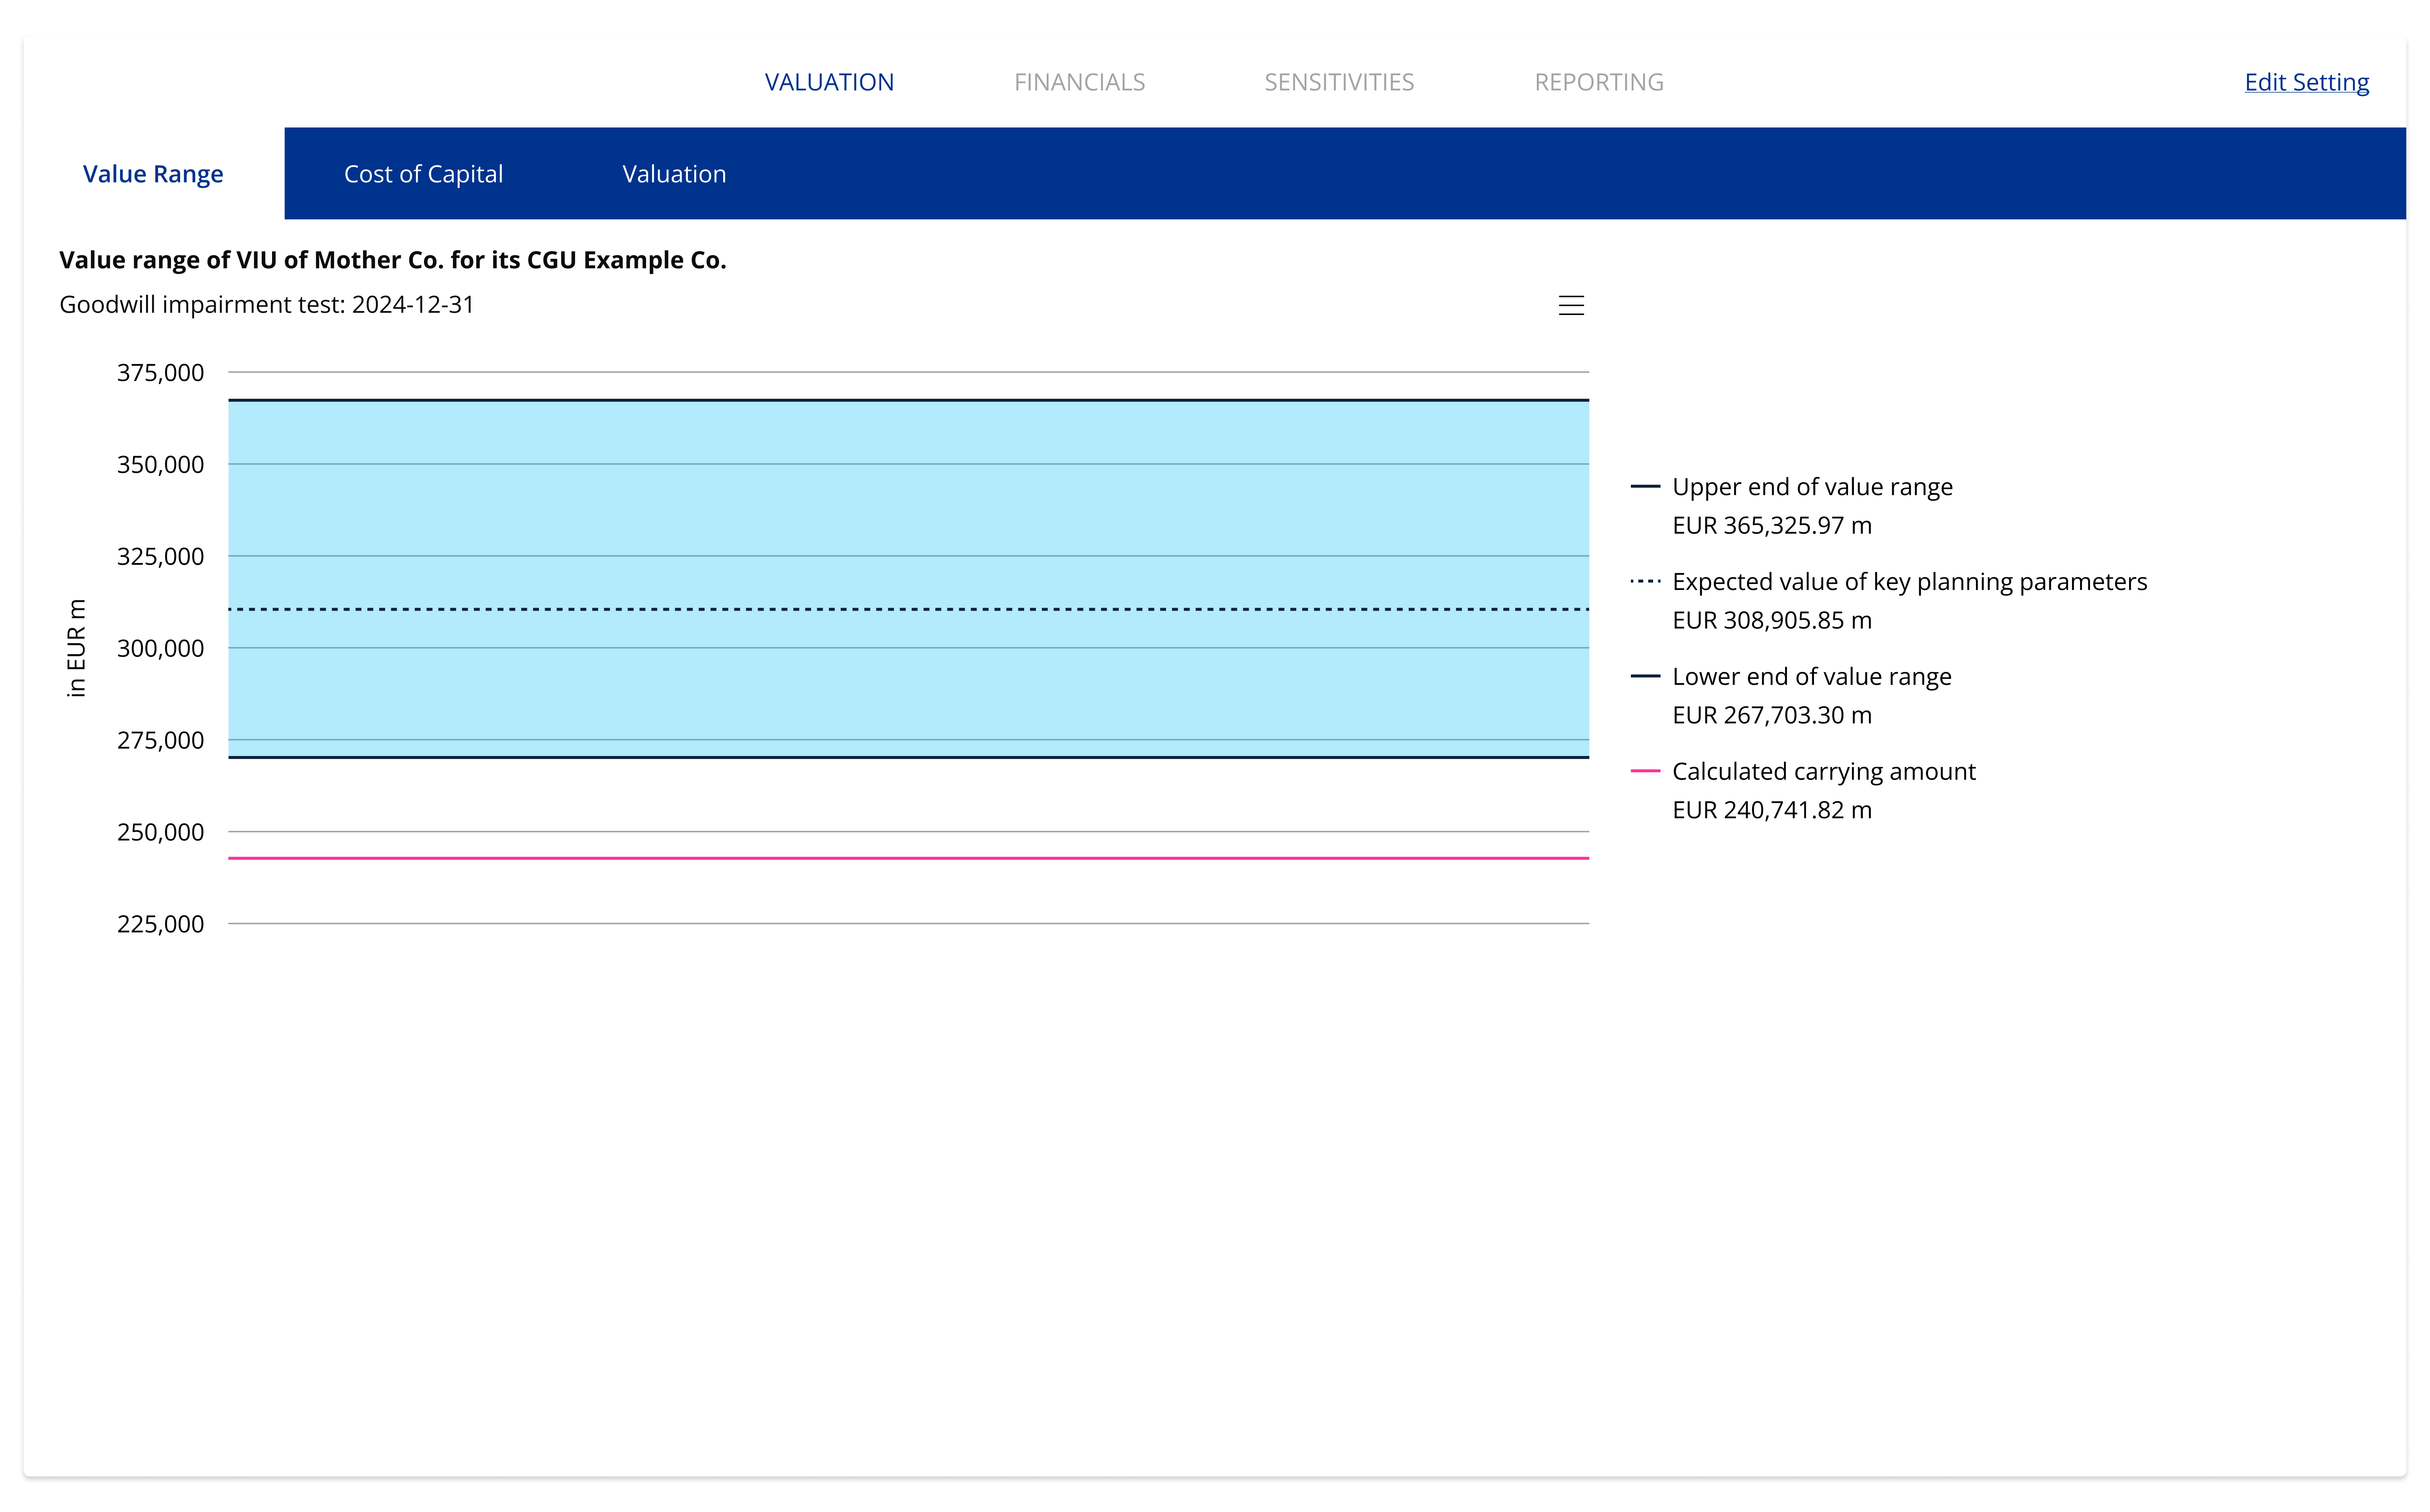
Impairment Test | Atlas KPMG
Impairment Test | Atlas KPMG
Goodwill & Impairment

.jpg?width=995&name=GoodwillImpairmentTestingTables-04 (1).jpg "Goodwill Impairment Testing Guide, Examples, & Accounting Tips")