Understanding the Bolivian Economic Landscape
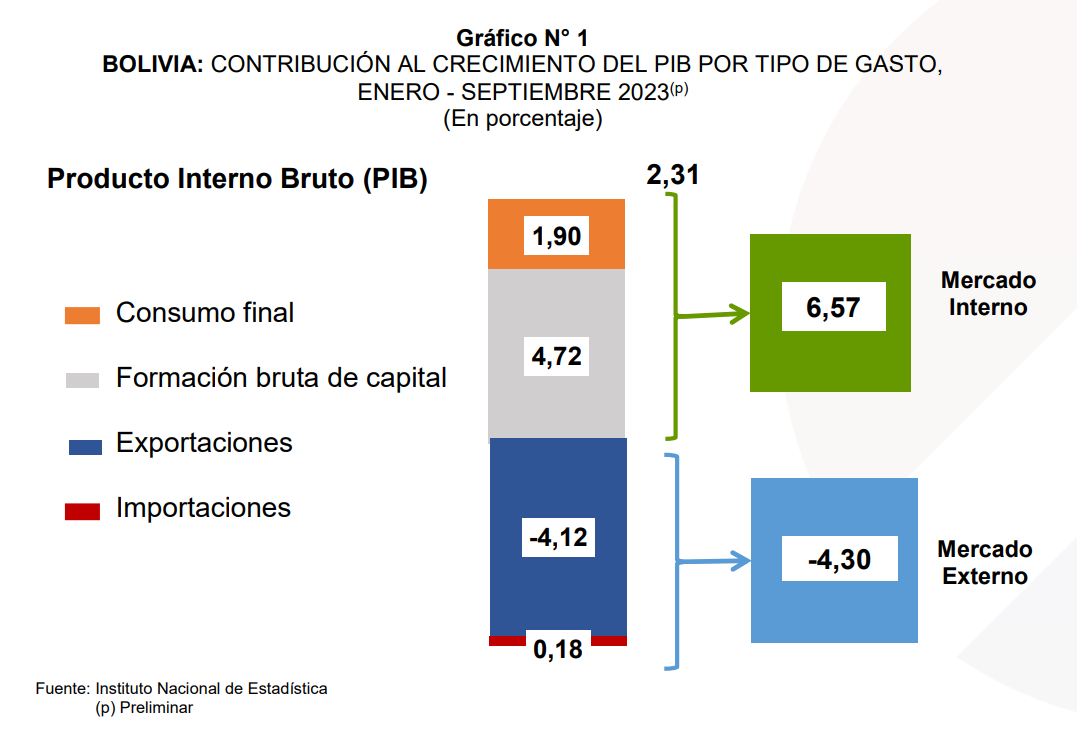
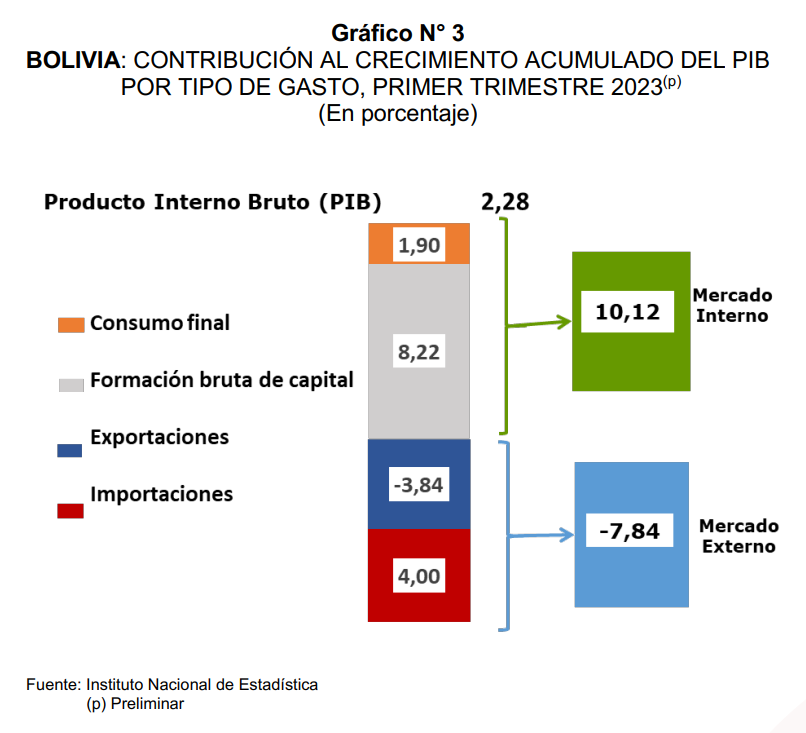
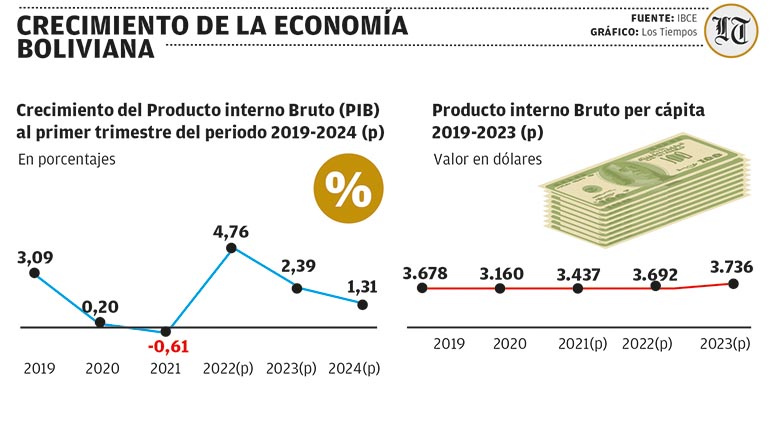
Bolivia's economy is smaller than most people think. The GDP sits around $45 billion USD with a per capita income that puts it firmly in the lower-middle income bracket for South America. The currency is the boliviano, and it's pegged within a narrow band to the US dollar, which matters more than you'd initially realize when you're dealing with cross-border transactions. The heavy lifting comes from three sectors: hydrocarbons (natural gas and oil), mining, and agriculture. Natural gas alone has historically contributed something like 30% of export revenue and roughly 10-12% of GDP. That dependency creates a structural vulnerability that became brutally obvious around 2019-2020 when production started declining faster than anyone anticipated. The government had been running modest fiscal surpluses during the commodity boom years, but those turned into deficits pretty quickly once gas revenues dropped and the political crisis hit.
What You Need to Know About La Economa En Bolivia
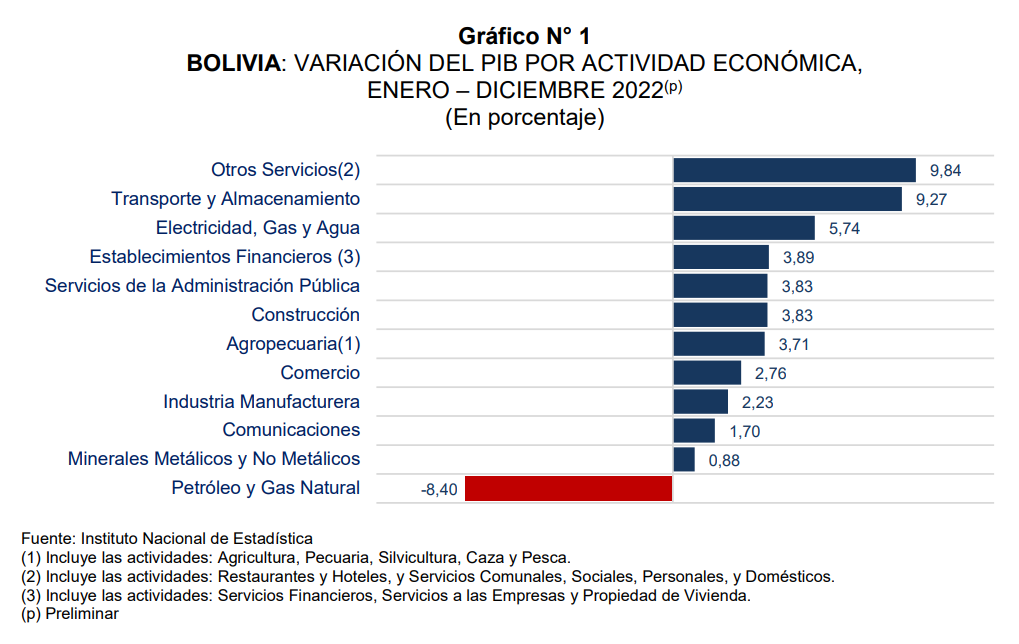
If you're researching or working within La Economa En Bolivia, the first thing to understand is that data transparency is not great. The Instituto Nacional de Estadística (INE) publishes reports, but there's often a lag of several months, and revision cycles can shift historical figures significantly. When I was compiling sectoral growth estimates for a client back in 2022, the official figures for Q1 and Q2 turned out to be off by nearly 2 percentage points after the INE released their annual revision. Not catastrophic, but enough to change your conclusions if you're building a model on quarterly data. Another thing that trips people up is the informal economy. It's estimated to absorb between 60-70% of non-agricultural employment. That means any employment or GDP figure you pull from official sources is capturing maybe half the actual economic activity. For practical purposes, this makes fiscal policy modeling quite challenging, since tax revenue forecasts are always going to be optimistic unless you account for the gap between formal GDP and total economic output.
How the Exchange Rate System Actually Works
Bolivia operates a managed float within a trading band. The central bank, Banco Central de Bolivia (BCB), intervenes frequently to keep the boliviano stable. The official rate has hovered remarkably close to 6.96 bolivianos per US dollar for many years. This stability sounds like a good thing, and in some ways it is — it reduces uncertainty for importers and Makes budgeting far more predictable than it would be under a freely floating currency. The catch is that this stability creates a parallel market. There is a black market for dollars that has existed for years, with exchange rates sometimes trading 10-20% above the official rate during periods of tension. I ran into this directly in late 2023 when I was helping a small import business in Santa Cruz navigate a shortage of foreign currency at authorized banks. The BCB had allocated dollars based on import licenses, but the queue was months long. The workaround that actually worked was using a nearby Argentine border crossing to source dollars through established trade channels, which shaved three weeks off what would have been a two-month wait through the formal system. It's not something you want to rely on routinely, but when the formal channel dries up, it's an option that exists.
Get the Full Details
The Fiscal Framework and Its Constraints
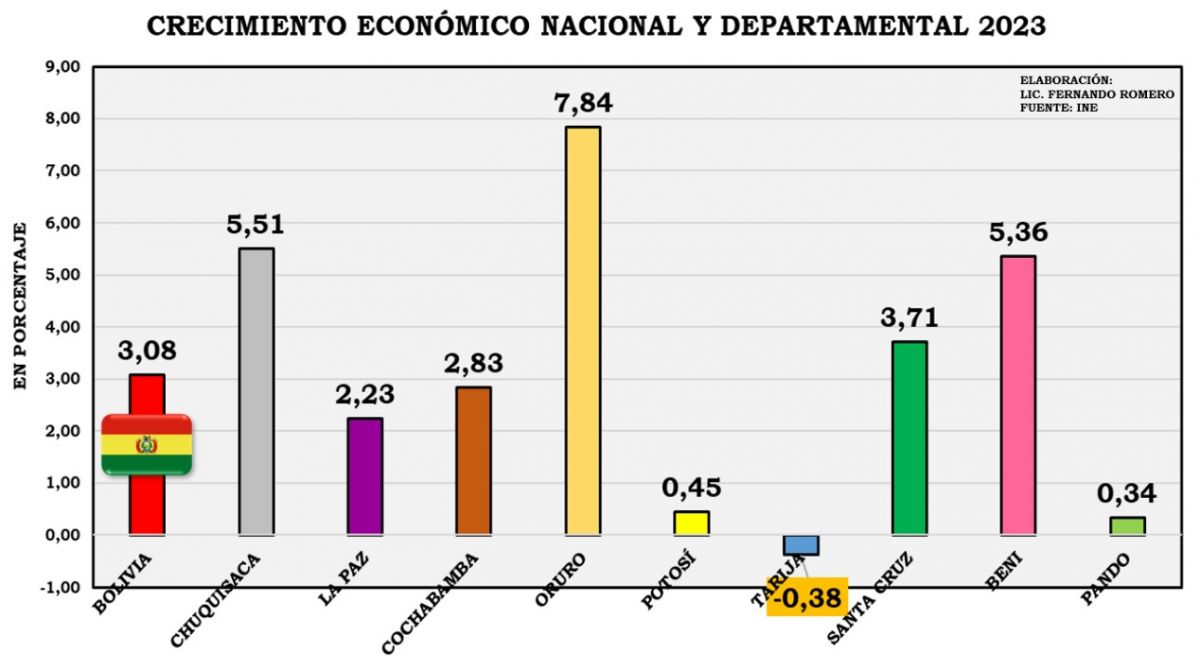
The government runs on a system where hydrocarbon revenues flow through the National Fund for Economic and Social Development (Fondsos). This is essentially a sovereign wealth mechanism, though it functions more as a spending buffer than an investment fund in practice. During the gas boom years, it accumulated significant reserves. When revenues fell, those reserves were drawn down, and by 2021 they were substantially depleted. A counter-intuitive point that most casual analyses miss: Bolivia's fiscal deficit is less dangerous than it looks in isolation because the country has minimal external debt by regional standards. Government debt to GDP is around 35-40%, which is moderate. The real risk isn't a debt crisis, it's a balance of payments crisis. If gas exports continue to decline and no replacement export sector emerges, the country faces a chronic external deficit that the central bank can only paper over by running down reserves or tightening import access. The agricultural sector, particularly soy and beef production in the eastern lowlands (the so-called "crescent" of departamentos like Santa Cruz, Beni, and Pando), is where most realistic growth potential lives. Santa Cruz department alone contributes over 30% of GDP. But this region also has a distinct political culture, and the tension between the highlands-centric federal government and the eastern departments is a recurring structural feature rather than a temporary disagreement.
Practical Considerations for Working with Bolivian Economic Data
If you're building models or doing research that involves Bolivia, here are the practical steps that actually matter: Use multiple data sources and cross-reference them. The BCB publishes monthly monetary and financial indicators. The INE handles price indices and national accounts. The Superintendencia de Bancos has banking sector data. The World Bank and IMF have their own estimates, which sometimes diverge from official figures in meaningful ways. Don't trust any single source without checking against at least one other. Expect revisions. Bolivia's GDP figures are compiled using a base year that hasn't been updated frequently enough, which means the weightings in the index can drift from reality. I've seen sectors that clearly grew substantially get surprisingly low weights in the official calculation simply because the base year was too old.
The inflation picture is especially tricky. The official CPI tends to understates true inflation, particularly in food and housing. When I tracked consumer prices in Cochabamba for a couple of years, the INE figure came in around 3-4% annually while my own spot-checks of staple goods suggested closer to 6-8% depending on the item. This isn't necessarily deliberate manipulation, it's more about the basket not being updated frequently enough and the methodology giving too much weight to regulated prices. There's no single download or dataset that gives you a complete picture. You'll need to compile from BCB reports, INE publications, ministry budgets, and sometimes municipal-level data if you're doing subnational analysis. The BCB's statistical portal at bcb.gob.bo is the closest thing to a starting point, but even that requires manual compilation across multiple publication series. The economy is holding together in a way that surprises some observers who expected collapse after the gas decline. Social programs funded during the boom years created a floor of demand that continues to support consumption. But the gaps are real and they're widening. Understanding those gaps — the informal sector, the dual exchange rate, the data problems — is more useful than any headline GDP number.