Working Out the Numbers Before You Touch the Dirt
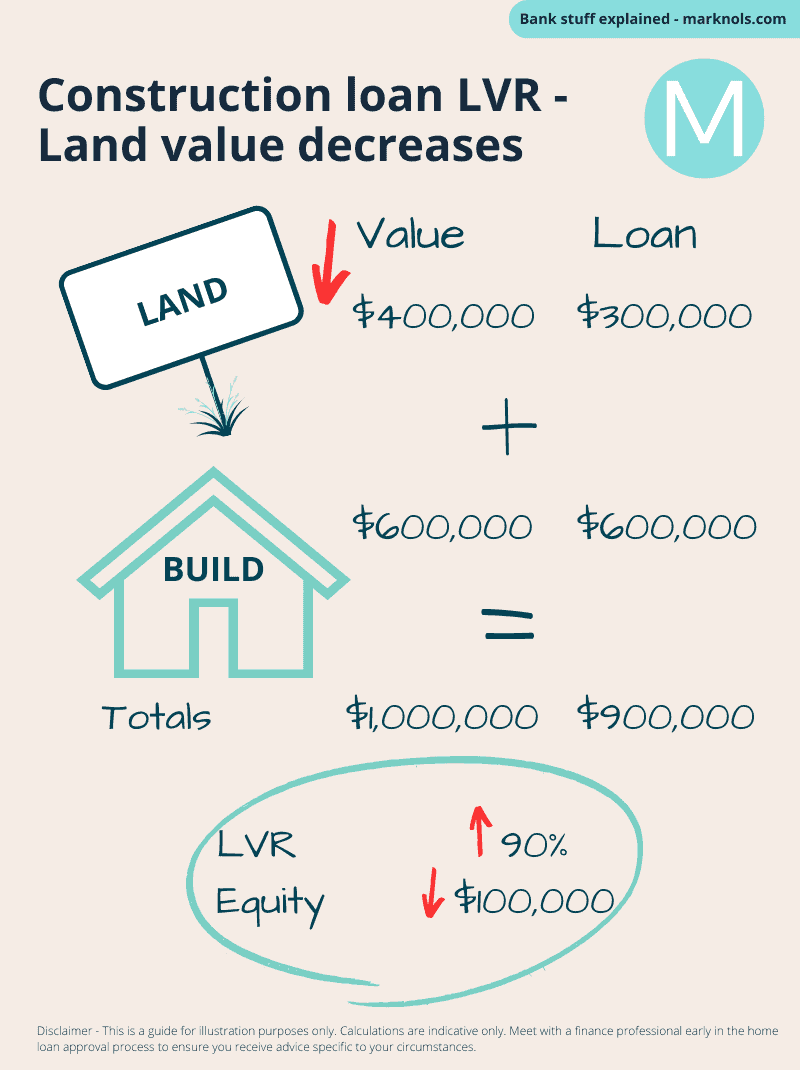
The first time I built a spreadsheet like this for a client, I thought it would take me ten minutes. It took three days because I kept running into edge cases where the numbers refused to settle. The core idea is straightforward enough. You take the equity locked in a parcel of land, factor in what the finished structure will cost, and figure out whether the lender will actually write the check. The harder part is all the stuff around those inputs that changes the answer by twenty percent or more. It takes three main inputs and spits out a maximum loan amount, a draw schedule, and a sense of your out-of-pocket gap. The inputs are the appraised land value, the projected construction cost, and the lender's loan-to-value or loan-to-cost ratio. From there it calculates how much the bank will lend against the combined value of land plus improved property, then tells you where the shortfall falls. Most online versions stop at that step. They give you a single number and call it a day. That number is useful as a starting point, not as a final answer. The real work happens after the calculator runs.
How I Built My Version and What I Changed
I started with a simple formula: maximum loan equals the lesser of appraised land value times the LTV ratio or total construction cost times the LTC ratio, minus any existing liens. Then I layered in the draw schedule. Construction loans don't disburse as a lump sum. They come out in tranches tied to inspections. If your calculator ignores draws, the loan amount it gives you is misleading, because the lender will size the note based on peak exposure, not the final disbursement. So I added a column-based draw model. Each phase gets a percentage of the total budget, and the calculator tracks cumulative disbursements against the available line. I also added interest reserve. That is the part most people forget until they are six weeks into a build and realize the monthly interest payment is eating into their change order budget. The calculator computes the reserve as a single lump sum pulled from the loan at closing, which keeps your payment schedule cleaner. The result is less flashy but closer to how underwriters actually think. You can type it into Google Sheets or Excel without needing any special software. I keep the sheet open every time I talk to a lender because it forces everyone to look at the same assumptions. The calculator spits out a summary page I hand over at the table so the conversation does not drift into vague territory.
The Specific Problem That Broke My First Draft
Here is a real one. I ran the numbers for a client who wanted to build on a 3.2-acre parcel with an existing manufactured home. The land appraisal came in at $180,000. The construction budget was $340,000. The calculator said the loan could cover everything. The underwriter said no. The problem was the site work. The lot had a perimeter drain that needed replacement and a septic system that failed percolation on the first test. Those items were not captured in the base construction budget, so the calculator was missing roughly $47,000 in soft and hard site costs. The loan came in short by about twenty-two thousand after I added them in. The workaround was not complicated. I built a separate line item group called Site Contingency that runs at twelve percent of total hard costs by default, with a toggle to increase it to eighteen percent for lots with known issues like poor soil, steep grade, or access constraints. Once I added that, the calculator flagged the shortfall before we ever walked into the lender's office. That saved us a week of reapplications and kept the timeline intact.
Get the Full Details

Counter-Intuitive Things Beginners Miss
The first thing is that the highest loan amount is not always the best number. Lenders cap the loan based on the lower of LTV or LTC, but your cash flow during construction depends on timing, not just the headline loan amount. If your draws front-load too aggressively, you pay interest on money you have not yet spent. I have seen builders carry an extra six months of interest because the calculator output was used as a disbursement schedule instead of a budget reference. Run a monthly cash flow projection on the same sheet, even a rough one, before you submit anything. The second thing is that land equity does not always behave the way you expect. A lot that is zoned residential but sits in a flood zone will appraise lower than a similar lot just outside the zone, even if the market rate for finished homes is the same on both sides. Some calculators do not ask about flood zone or environmental constraints, so the output looks fine until the appraisal comes back and the numbers shift. I add a checkbox for FEMA flood zone and a multiplier that reduces the land value input by five to fifteen percent depending on the zone. It is rough, but it prevents the kind of surprise that makes people lose deposits.
What This Tool Cannot Do
It cannot replace an appraisal. It cannot account for lender-specific overlays. Some banks add a debt service coverage ratio requirement for certain loan products, which changes the effective loan size independently of the LTV math. The calculator also cannot tell you whether your general contractor's bid is realistic. I once saw a builder use the output to justify a $210-per-square-foot budget on a project where comparable builds in the same county were going for $155. The calculator said the loan worked. The contractor bid came in eleven percent higher than the estimate, and the borrower had to bring cashier's checks to closing. If you are working with a lender who requires a third-party feasibility study or a Phase I environmental report, this tool is not a substitute. It is a planning and communication aid. Use it to align assumptions before you spend money on reports that might change the outcome. That is where it earns its keep.
Using the Land Equity Construction Loan Calculator in Practice
Open the sheet, enter the land value, the construction budget, the LTV and LTC ratios your target lender uses, and the existing lien balance. Set the draw schedule percentages to match your contractor's proposed milestone plan. Turn on interest reserve if the lender requires it, which most do for terms over twenty-four months. The calculator outputs the maximum loan, the estimated reserve, the monthly interest payment, and the borrower cash gap. Compare that gap to your available liquidity. If the gap exceeds twenty percent of your total project cost, either reduce scope, renegotiate the draw schedule, or look for a different loan product. The math does not lie, but it also does not care about your timeline.

Getting the Land Equity Construction Loan Calculator
I do not host the file on a server and ask you to create an account. The sheet lives in Google Sheets, and I share a read-only template link through the project folder where clients and contractors already communicate. If you build your own version, save it with version numbers and date stamps because you will revisit it when bids come back or when the appraisal adjusts. Keeping a clean file history prevents the kind of confusion where everyone is looking at a different number and arguing about who is right.
When to Walk Away From This Approach
If your land has unresolved title issues, pending zoning changes, or disputed boundary lines, no calculator will help until those are resolved. The inputs will look clean and the output will be wrong. Fix the legal and due diligence problems first, then run the numbers. If your projected construction cost is based on a ballpark figure rather than a contractor's written estimate, treat the output as directional at best. The tighter your inputs, the more useful the calculator becomes, and the tighter I recommend the inputs be before you show anyone else the sheet.