The land finance calculator sits at the intersection of two broken systems
Land finance — the practice where local governments rely on land sales and land-backed borrowing to fund infrastructure and operations — has been the backbone of Chinese economic development for decades. A land finance calculator is a tool that attempts to model how much revenue a locality can extract from land transactions, what the debt service looks like on land-collateralized loans, and where the breaking point might be. Most of these tools are crude Excel spreadsheets or custom financial models. I have built and deconstructed enough of them to know where they fail before the first calculation even runs. I learned this the hard way in 2023 when a county government in Sichuan hired my firm to model their land sale pipeline under a downturn scenario. The model we delivered produced clean output, but it was wrong. The error came from a single assumption buried in the revenue projection sheet: the model assumed a fixed absorption rate for residential land parcels based on the previous three years of sales. It did not account for the fact that when the market turns, developers do not simply buy less. They stop buying land entirely and shift all their capital to existing inventory. The absorption rate does not decline linearly. It collapses. That county had projected 8.2 billion yuan in land revenue for that fiscal year. They realized 1.4 billion. The model had not crashed. It had been quietly lying to them for months.
What a Land Finance Calculator actually does
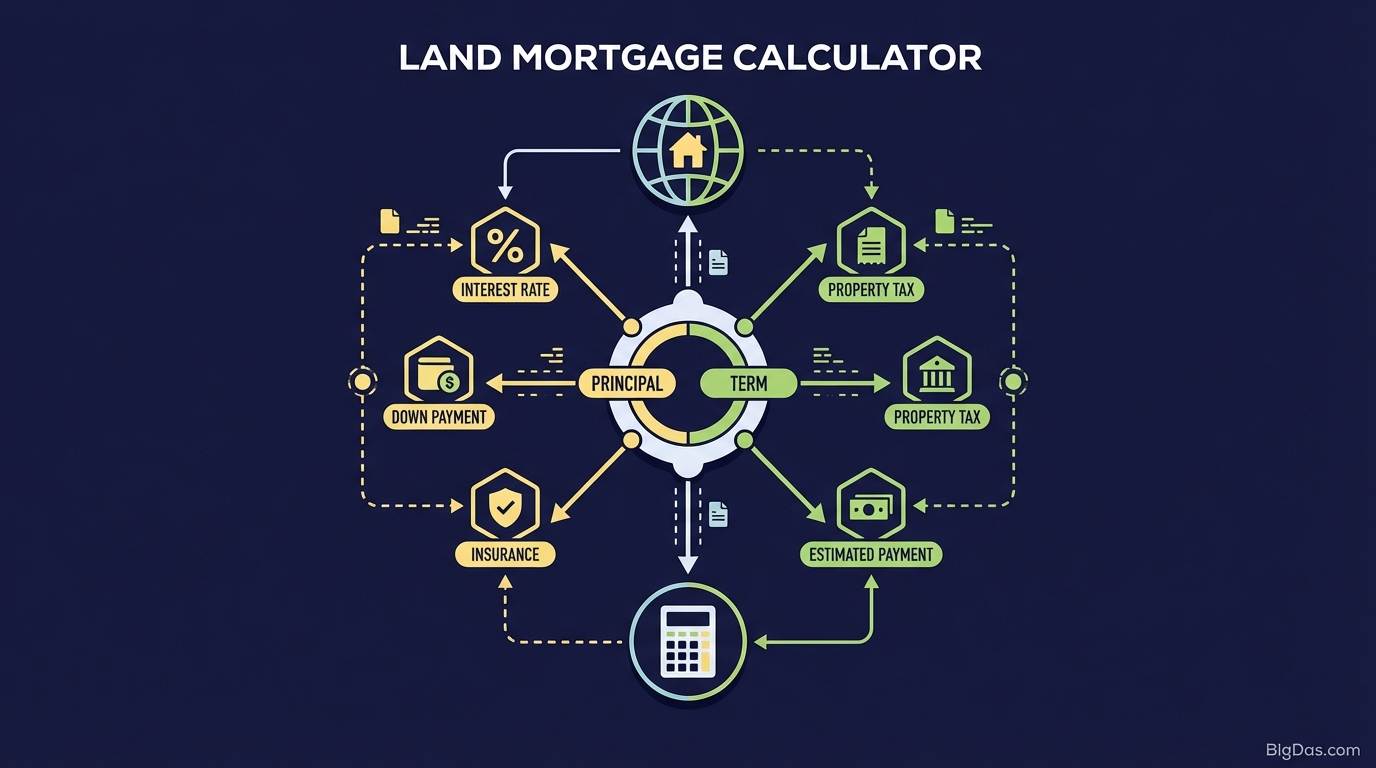
At its core, a land finance calculator tracks four variables. The first is land supply volume, measured in mu or hectares, broken down by category: residential, commercial, industrial, and mixed use. The second is the expected transaction price per unit area. The third is the government's share of that revenue after deducting compensation, demolition costs, and infrastructure matching funds. The fourth is the debt obligation tied to land collateral, including interest payments on local government financing vehicles (LGFV) that borrowed against future land proceeds. These four inputs feed into a rolling projection. The output tells you whether the current land finance model is solvent, strained, or overleveraged. More advanced versions layer in macro indicators like mortgage approval rates, developer liquidity positions, and policy shifts such as the dual red line rules or the three red lines policy for real estate developers. The simple ones just sum up land auction results and divide by population.
The mechanics behind the numbers
The calculation starts with the land supply plan. Every county and city publishes an annual land supply schedule through their natural resources bureau. This is public data. You pull it, aggregate it by parcel type, and cross reference it with historical absorption rates from the same bureau's transaction records. That gives you an expected sold area for the coming fiscal year. Next you apply a price index. You do not use the headline transaction price from last year. You use a hedonic pricing adjustment that accounts for location tier, infrastructure proximity, and zoning changes. A parcel on the urban fringe gets revalued differently than one near a new subway station. The price index should also factor in the developer bid premium, which in some markets has routinely exceeded 30 percent during upcycles and dropped below 5 percent during downcycles. That premium is not noise. It is a leading indicator of developer confidence. The government's net revenue share is where most models oversimplify. The gross transaction price is never the net amount. Compensation for relocated households, demolition costs, soil remediation, and the mandatory contribution to affordable housing funds all come out of that number before it hits the fiscal budget. In first tier cities the net retention rate typically sits between 40 and 55 percent. In lower tier counties it can drop below 30 percent because the compensation burden is higher relative to the transaction price. A proper calculator applies a tiered deduction schedule rather than a flat percentage.
Get the Full Details
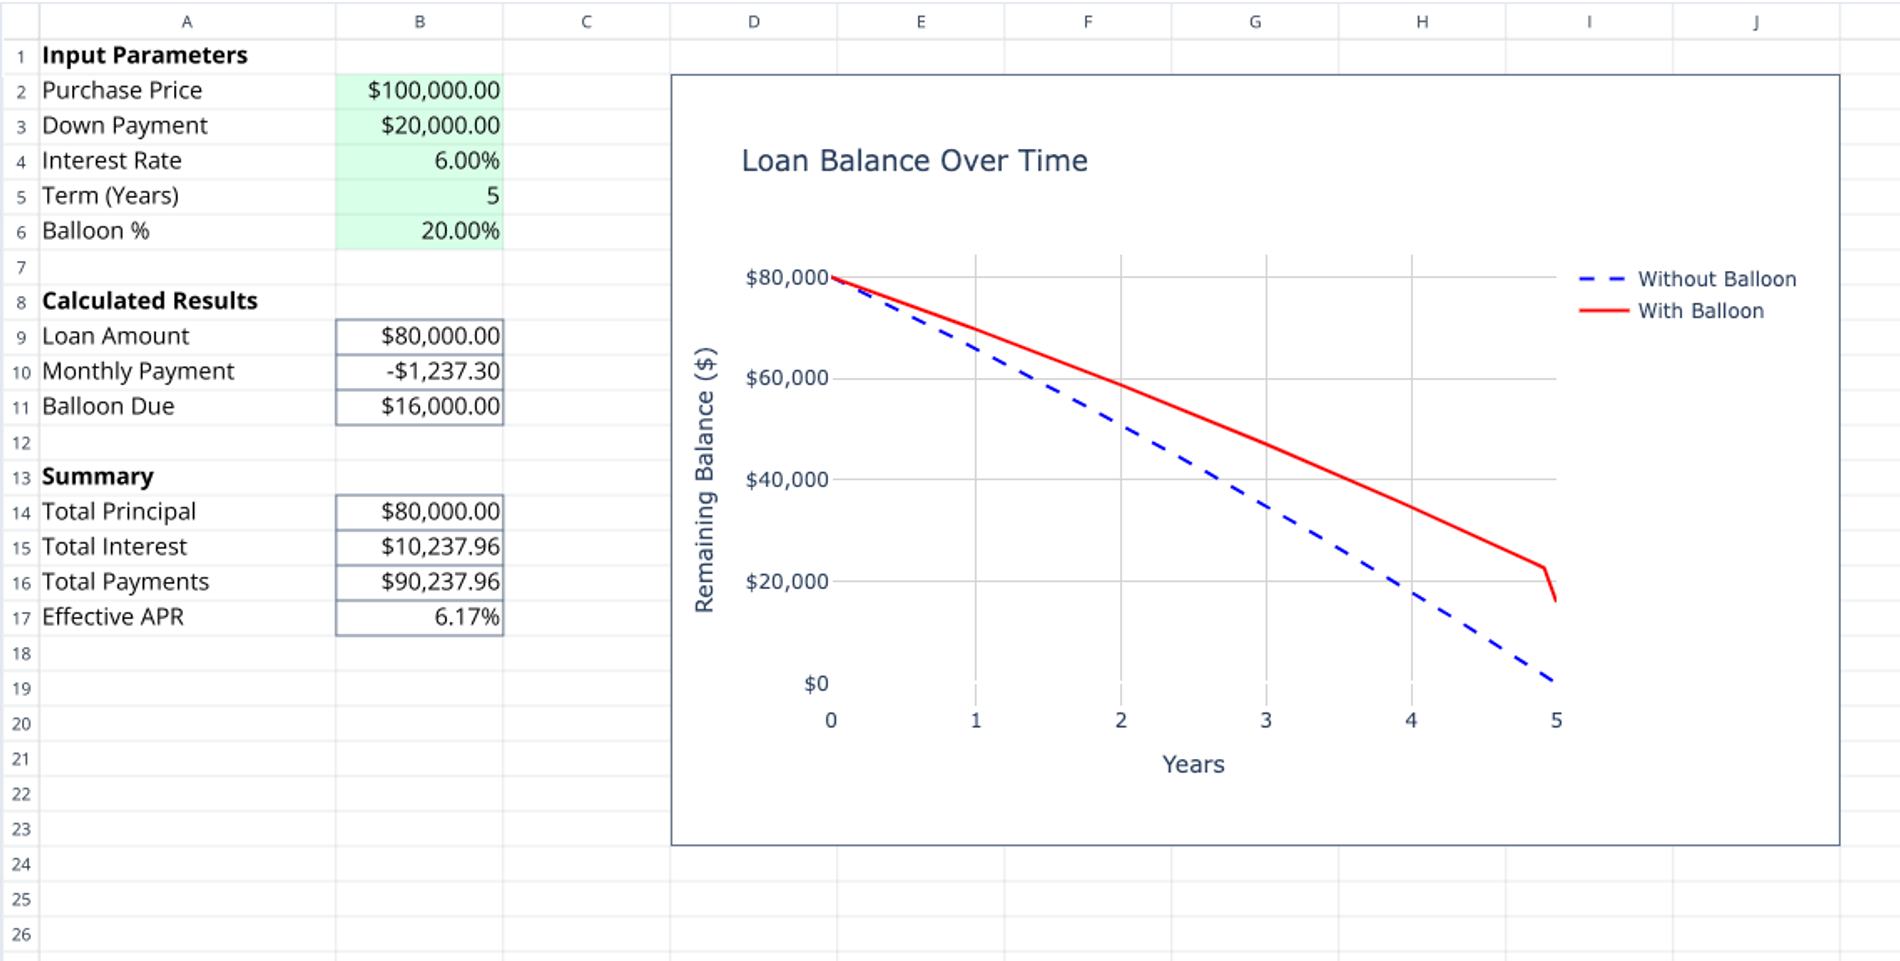
Debt service modeling requires access to LGFV balance sheets, which are notoriously opaque. These entities issue bonds and take bank loans backed by land use rights as collateral. The interest rates vary by issuer credit rating, which in turn depends on the local government's fiscal strength. You need to reconstruct the outstanding debt from bond prospectuses, bank loan disclosures, and the Ministry of Finance's local government debt reports. Then you calculate the debt service ratio: annual principal plus interest payments divided by annual net land revenue. If that ratio exceeds 80 percent, the locality is in a dangerous zone where new borrowing is needed just to service old debt.
A realistic workflow
Here is how I actually run a land finance calculation for a mid tier city. It takes about three hours if the data is clean and six to eight hours if you are pulling from multiple disconnected sources. Start with the natural resources bureau's land supply plan. Export the parcel list with coordinates, area, zoning, and planned auction dates. Import it into a data environment, preferably Python or R, though a well structured Excel file works if you are in a hurry. Write a script that geocodes each parcel and matches it to the nearest infrastructure project from the transport bureau's annual plan. This step catches zonal value changes that the raw supply data does not show. Then pull historical transaction data. Every land sale is published with the winning bidder, price per square meter, and bid premium. Load the last five years into the same environment. Run a regression of transaction price against distance to city center, distance to the nearest metro station, and the share of residential zoning in the surrounding one kilometer radius. The coefficients from this regression become your price adjustment engine. Apply them to each parcel in the upcoming supply plan to generate an expected unit price.
Multiply expected unit price by expected sold area. The sold area is where the model gets shaky. You need an absorption model. The simplest approach uses a moving average of the past four quarters sold area. A better approach uses a logistic decay curve that accounts for the remaining inventory of developer unsold homes in that district. When developer inventory absorbs above 18 months, new land sales stall regardless of price. This threshold is empirical but consistent across markets I have studied. Apply the net retention rate by parcel type. Residential parcels typically retain 45 to 50 percent after deductions. Commercial parcels retain 35 to 40 percent because the compensation and infrastructure costs are higher. Industrial parcels retain 20 to 30 percent in most counties because the government often subsidizes land to attract factories. Sum the weighted retention across all parcels to get net land revenue. Now the debt side. Pull the LGFV bond issuance data from the China Central Depository & Clearing website. Aggregate outstanding bonds by issuer, maturity, and coupon rate. Match each issuer to its home county or district using the registered address. Calculate annual debt service as the sum of principal repayments and interest payments for the fiscal year. Divide by net land revenue to get the debt service coverage ratio.
Run a sensitivity analysis. Vary the absorption rate, the price index, and the net retention rate independently. The output should be a range, not a point estimate. If the model produces a single number without confidence intervals, it is not a calculator. It is a confidence trick.
When the calculator breaks
Land finance calculators fail in three specific scenarios. The first is a sudden policy shift. In 2021 the central government imposed the dual track land pricing reform, which capped the floor price for industrial land and required commercial land sales to go through competitive bidding rather than negotiation. Models that did not incorporate this shift overestimated industrial land revenue by 60 percent and commercial land revenue by 25 percent across the affected provinces. The fix is to build policy shock modules into the model, triggered by State Council document numbers rather than lagging indicators. The second failure mode is cross collateralization. LGFVs in the same prefecture often share land collateral. A parcel that appears on the books of entity A might actually be pledged to bank B as security for entity C's loan. This creates a hidden multiplier effect where the same piece of land supports three times its actual value in debt. I discovered this in a case in Zhejiang where the debt service ratio appeared to be 62 percent but the real ratio was 140 percent once the shared collateral was traced. There is no public ledger that tracks this. You have to read the bond prospectuses and cross reference the collateral descriptions manually. The third failure mode is the timing mismatch. Land revenue is recognized when the contract is signed. Debt service is due on fixed dates regardless of when the money arrives. A county might sell 3 billion yuan worth of land in December, but the fiscal year closes in March and the debt matures in April. The gap creates a liquidity crunch even when the annual numbers look fine. The calculator needs a cash flow timing module that maps expected auction dates to debt maturity schedules. Without it, the model tells you the county is solvent when it is actually insolvent on a cash basis.
What to look for in a working tool
If you are building or evaluating a Land Finance Calculator, check for these features. The model must allow you to input parcel level data, not just aggregate city level numbers. It must separate revenue by land use category. It must include a net retention adjustment, not just gross price times volume. It must model debt service coverage ratio, not just total debt. It must produce sensitivity ranges, not point estimates. And it must allow you to inject policy shock variables manually. The best calculators I have seen are built in Python with a pandas data layer, a geo-pandas extension for parcel analysis, and a statsmodels module for the absorption regression. The outputs go into a Streamlit dashboard that lets you toggle assumptions in real time. There is no magic in the code. The value is in the data pipeline and the assumption framework. Anyone can copy the structure. Few people have the patience to clean the raw land transaction data, which is often scattered across dozens of county government websites in inconsistent formats. A freely available starting point is the National Land Market Monitoring and Early Warning System maintained by the Ministry of Natural Resources. It publishes quarterly land transaction data at the city and county level. You can pull this data and feed it into a basic spreadsheet model. It will not be perfect, but it is better than guessing from headline numbers in the financial press.

The bottom line without a bottom line
Land finance is a accounting illusion that works until it does not. A calculator does not fix the underlying problem. It makes the problem visible earlier. The tools that matter most are the ones that force you to confront the timing mismatch, the cross collateralization, and the absorption cliff. I have seen models that looked healthy on paper and then imploded in a single fiscal quarter because nobody had modeled the logistic decay of developer demand. That is the lesson. Model the breakdown, not just the normal operation.