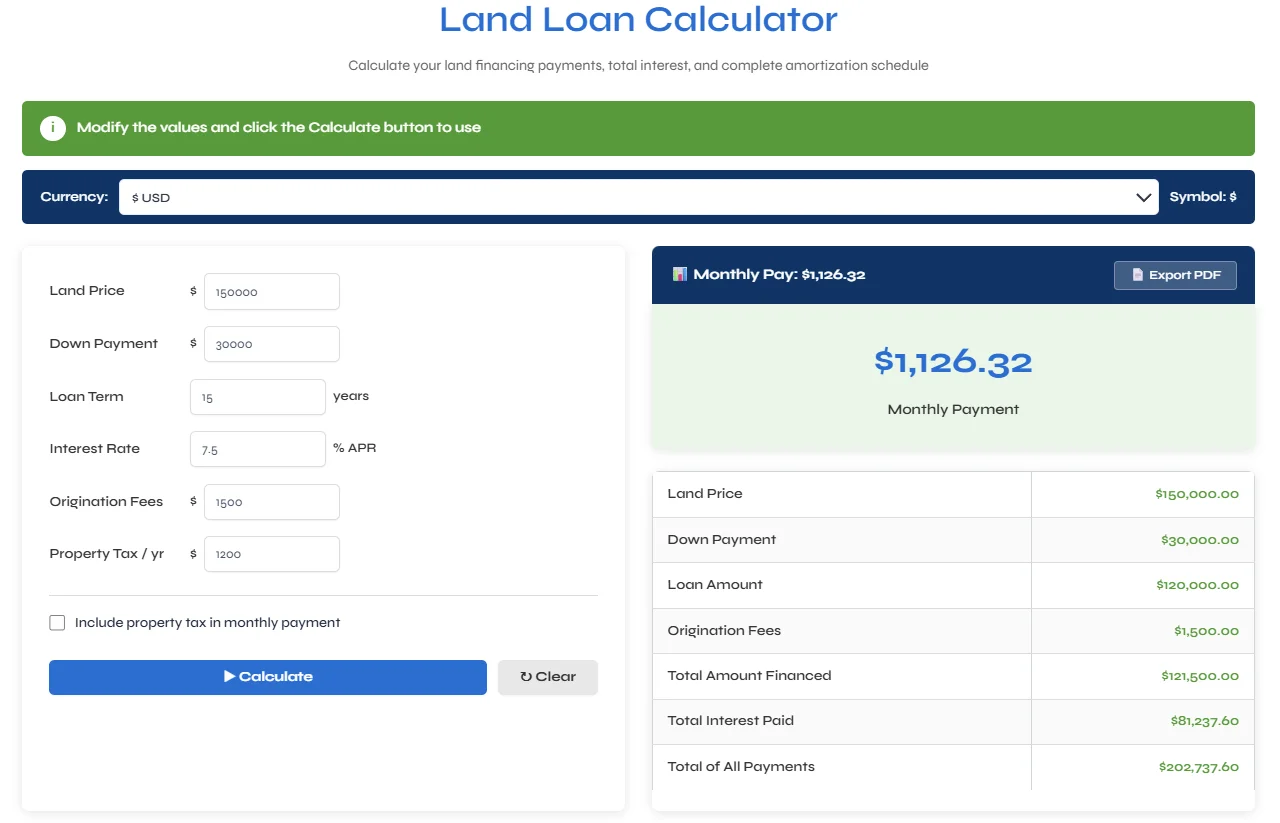
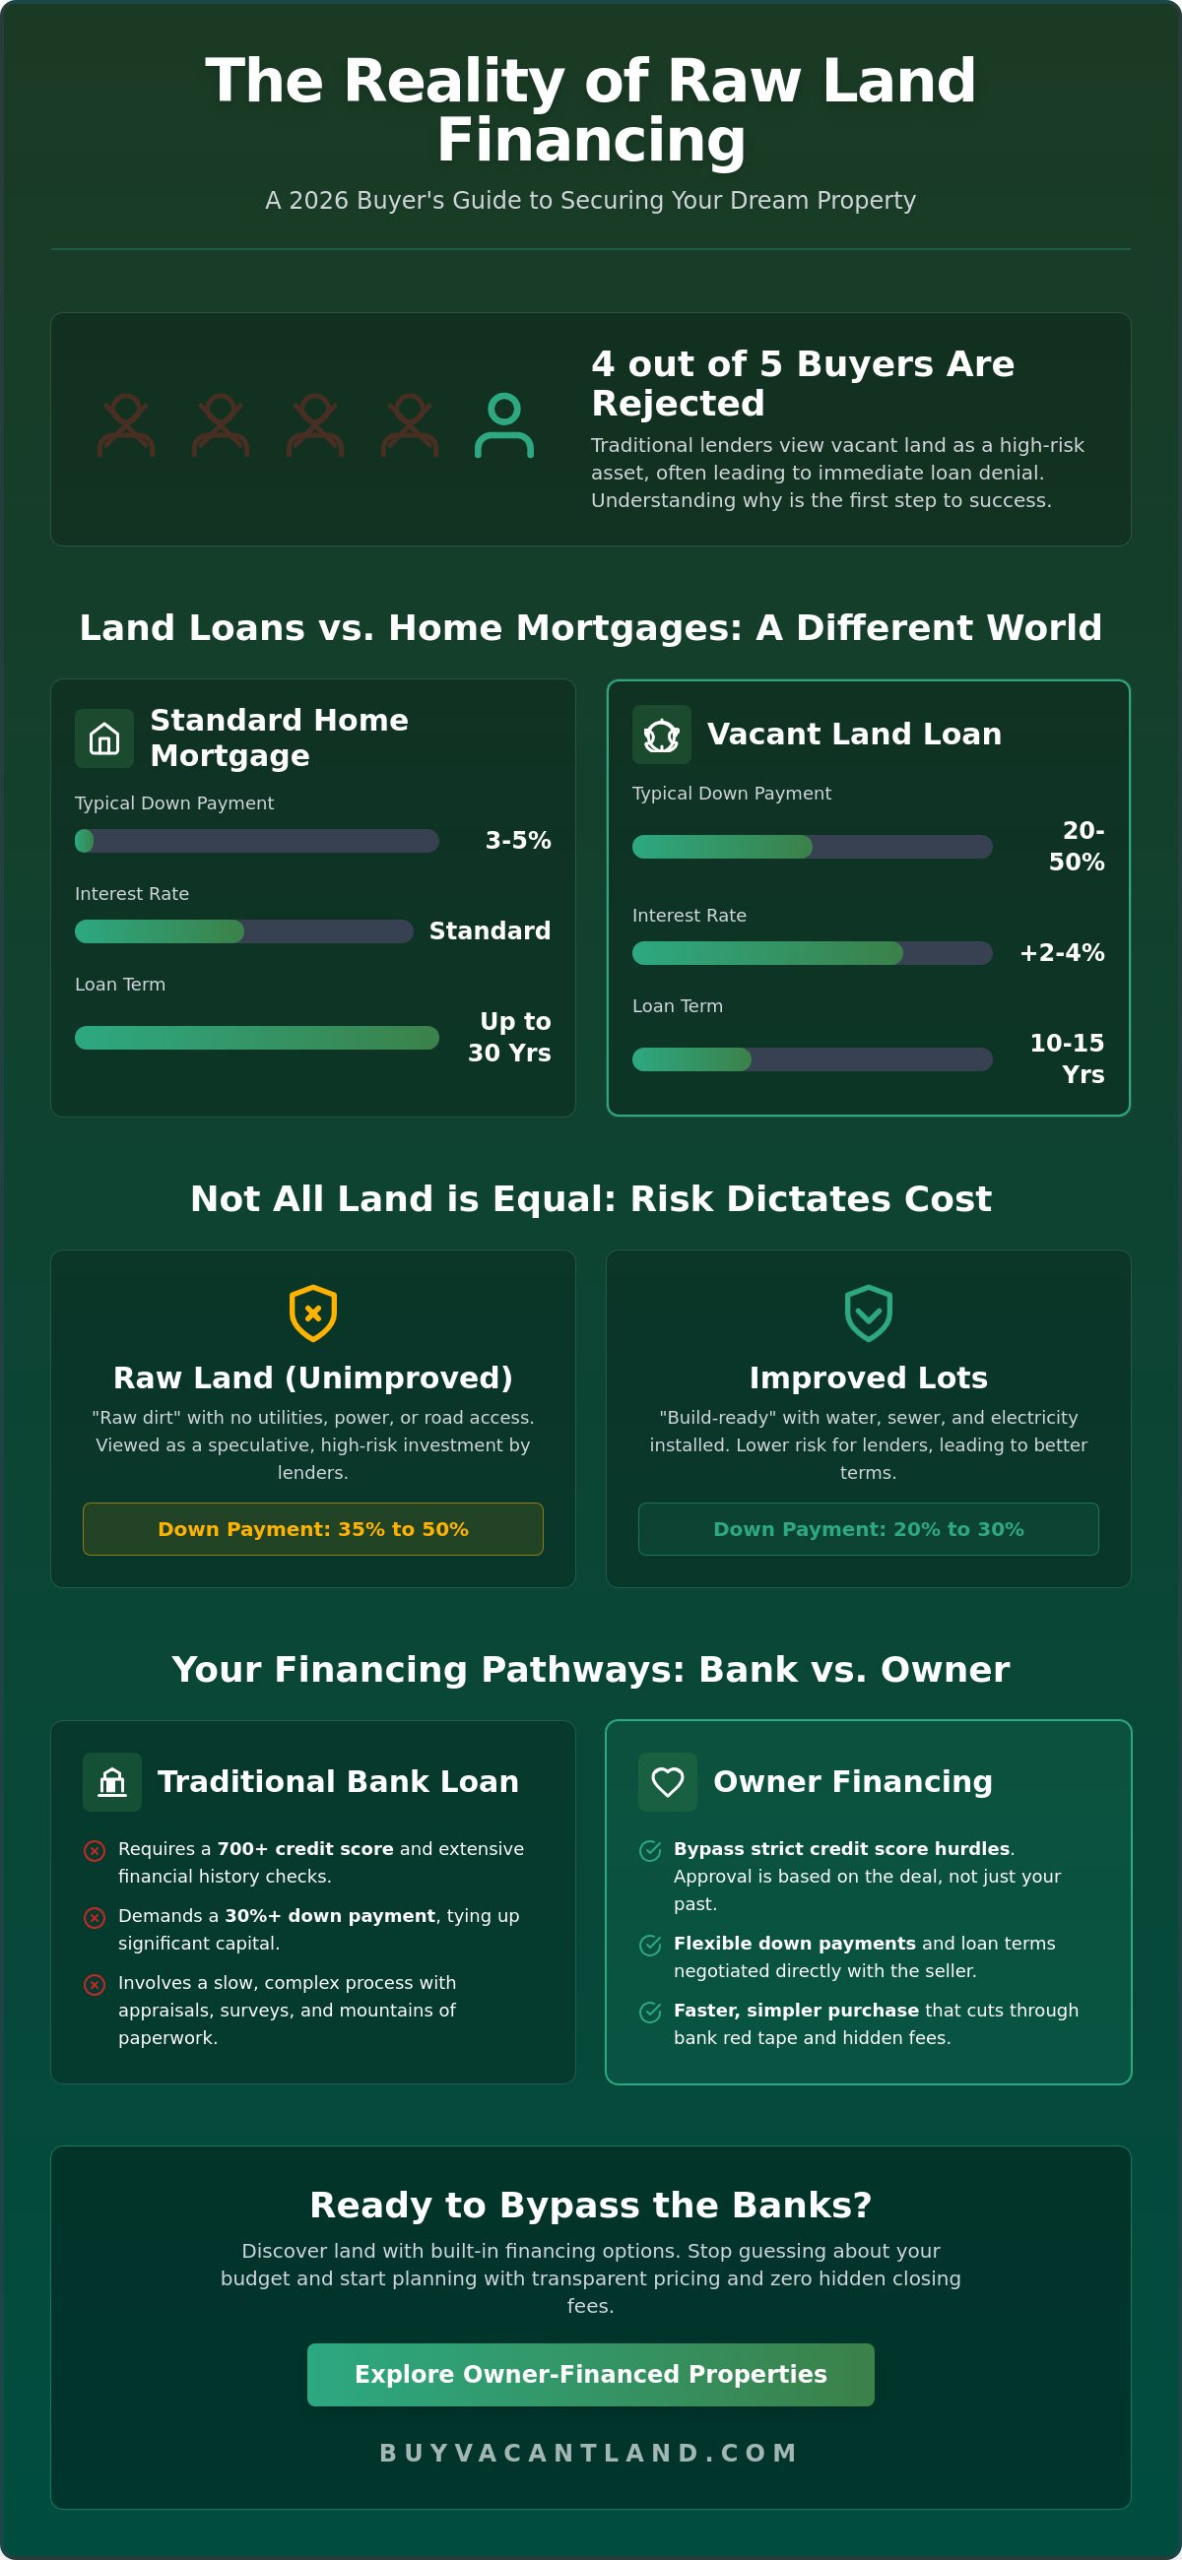
A land loan calculator is a straightforward tool that estimates your monthly payment on a loan used specifically to purchase vacant land. The inputs are similar to a standard mortgage calculator—loan amount, interest rate, and term—but the outputs can look quite different because the financing terms for raw land are not the same as home loans. I have seen people bring spreadsheets from conventional mortgage calculators and wonder why the numbers looked wrong. That happens because land loans carry higher rates, larger down payments, and sometimes shorter amortization periods, and a basic mortgage calc won't account for those differences unless you tweak the inputs manually.
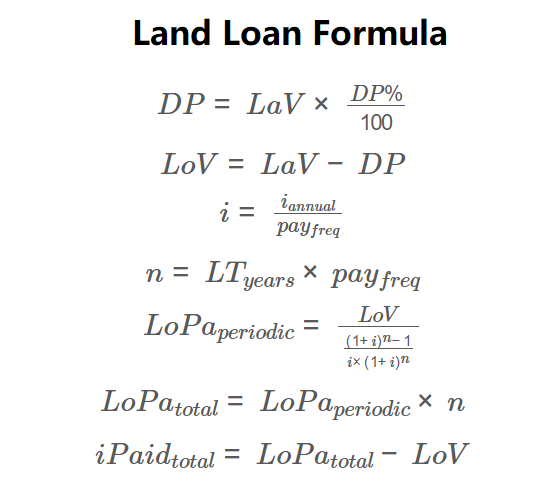
The standard amortization formula is what you will find behind most of these tools: M = P * [r(1+r)^n] / [(1+r)^n - 1], where P is the principal, r is the monthly interest rate, and n is the number of payments. It looks the same as a house loan formula, but the variables shift in practice. Lenders typically charge between 6 and 9 percent for raw land, sometimes more if the parcel is unconventional or the borrower lacks strong collateral elsewhere. Down payments often run 20 to 50 percent depending on how usable the land is.
Using a Land Loan Calc Correctly
The most common mistake I see is entering the full purchase price as the loan amount. With land loans, you usually need a substantial down payment, so the loan amount is purchase price minus down payment. I ran into this repeatedly when helping clients compare quotes. One borrower entered $180,000 as the loan amount when they actually had $72,000 coming out of pocket, and the monthly payment estimate was wildly off. They had to redo the entire comparison after that.
Another issue is the loan term. Conventional home loans often stretch to 30 years. Land loans are more commonly structured at 10 to 20 years, and some are interest-only for the first few years before switching to principal and interest. If you pick a 30-year term in the calculator without noting that your actual loan may only be 15 years, you will underestimate your payment significantly.
Here is what you should do step by step. First, find out the actual interest rate and term from your lender before you plug anything in. Second, calculate your down payment amount and subtract it from the purchase price to get the principal. Third, enter those numbers into the Land Loan Calc along with the loan term in years. Fourth, double-check whether the calculator assumes full amortization or interest-only payments. Most free calculators online default to full amortization, which will make your payment look lower than what the lender actually requires in the early years.
I learned this the hard way with a commercial lot in North Carolina. The lender quoted an interest-only period of three years, then switched to a 15-year amortizing schedule. The calculator I had been using showed one consistent monthly number, but the real payment jumped by about 40 percent after year three. I worked around it by building a custom Excel schedule that split the loan into two phases: interest-only for the first 36 months, then principal and interest for the remaining 144. That took me about twenty minutes to set up, and it saved me from walking into refinancing unexpectedly.
What the Calculator Does Not Tell You
A Land Loan Calc will not include property taxes, homeowners insurance, or any impact fees your local jurisdiction might charge. Those costs are separate and can add hundreds of dollars per month depending on where the land is located. I worked with a client who was surprised by a $3,200 road impact fee from the county. It was not disclosed until closing, and it effectively increased the project cost by nearly 8 percent. No calculator would have shown that, because impact fees vary by municipality and are rarely standardized.
You also need to consider loan type. Raw land, improved land, and lot loans each carry different risk profiles and therefore different terms. A calculator treating all three identically will give you a number that is close enough for rough planning but misleading if you are comparing actual offers. Improved land with utilities at the lot line gets better rates than raw land with no access. A lot within an approved subdivision gets even better terms. Know which category your property falls into before you trust the output too much.
One counter-intuitive thing worth noting: sometimes a shorter loan term produces a higher monthly payment but a dramatically lower total cost over the life of the loan, and that matters more with land loans than with traditional mortgages. Because land loan rates are already high, the interest portion of every payment eats into equity slowly. A 10-year loan at 7 percent might have a monthly payment that looks steep compared to a 15-year at the same rate, but the total interest paid over 10 years can be less than half of what you would pay over 15. I have seen borrowers lock into longer terms thinking it was safer, then realize they were paying nearly twice as much in interest for a payment reduction of only 15 or 20 percent.
Another pitfall is prepayment penalties. Some land lenders include them, and they can be structured as a percentage of the remaining balance for the first three to five years. A calculator will never factor that in. You have to read the loan documents carefully and budget for the possibility that paying off the loan early is expensive during the penalty window.
When a Standard Calculator Falls Short
If your situation involves a government-backed loan like an SBA 504 or a USDA rural development loan, standard land loan calculators are not going to give you accurate numbers. Those programs have special requirements, capped interest rates, and different amortization structures. I encountered this when a client asked about a USDA loan for a small parcel outside a designated rural area. The calculator spit out a payment that looked reasonable, but the property was just outside the eligibility zone, and the loan program itself had a different rate structure than what the calculator assumed. I ended up using the USDA's own payment estimator instead, which took about five minutes to navigate, but it was the only way to get a number that matched actual lender quotes.
For most conventional raw land loans, a decent Land Loan Calc will get you in the right neighborhood. The real value comes from understanding what the tool is hiding and running a second pass through a spreadsheet or lender-specific calculator to catch the gaps. That second pass usually takes me less than ten minutes, and it prevents the kind of surprise that costs people thousands.
Gallery Land Loan Calc
Land Loan Calculator USA - Calculate Monthly Land Payments,
Land Loan Calculator - Land Loan Estimator
Land Loan Rates Calculator – Plot Loan EMI, Interest & Tenure Calculator
Land Loan Payment Calculator
Land Loan Calculator: Estimate Your Payments & Financing Costs in 2026