Working with Land Loans in Texas Is Different Than Buying a House
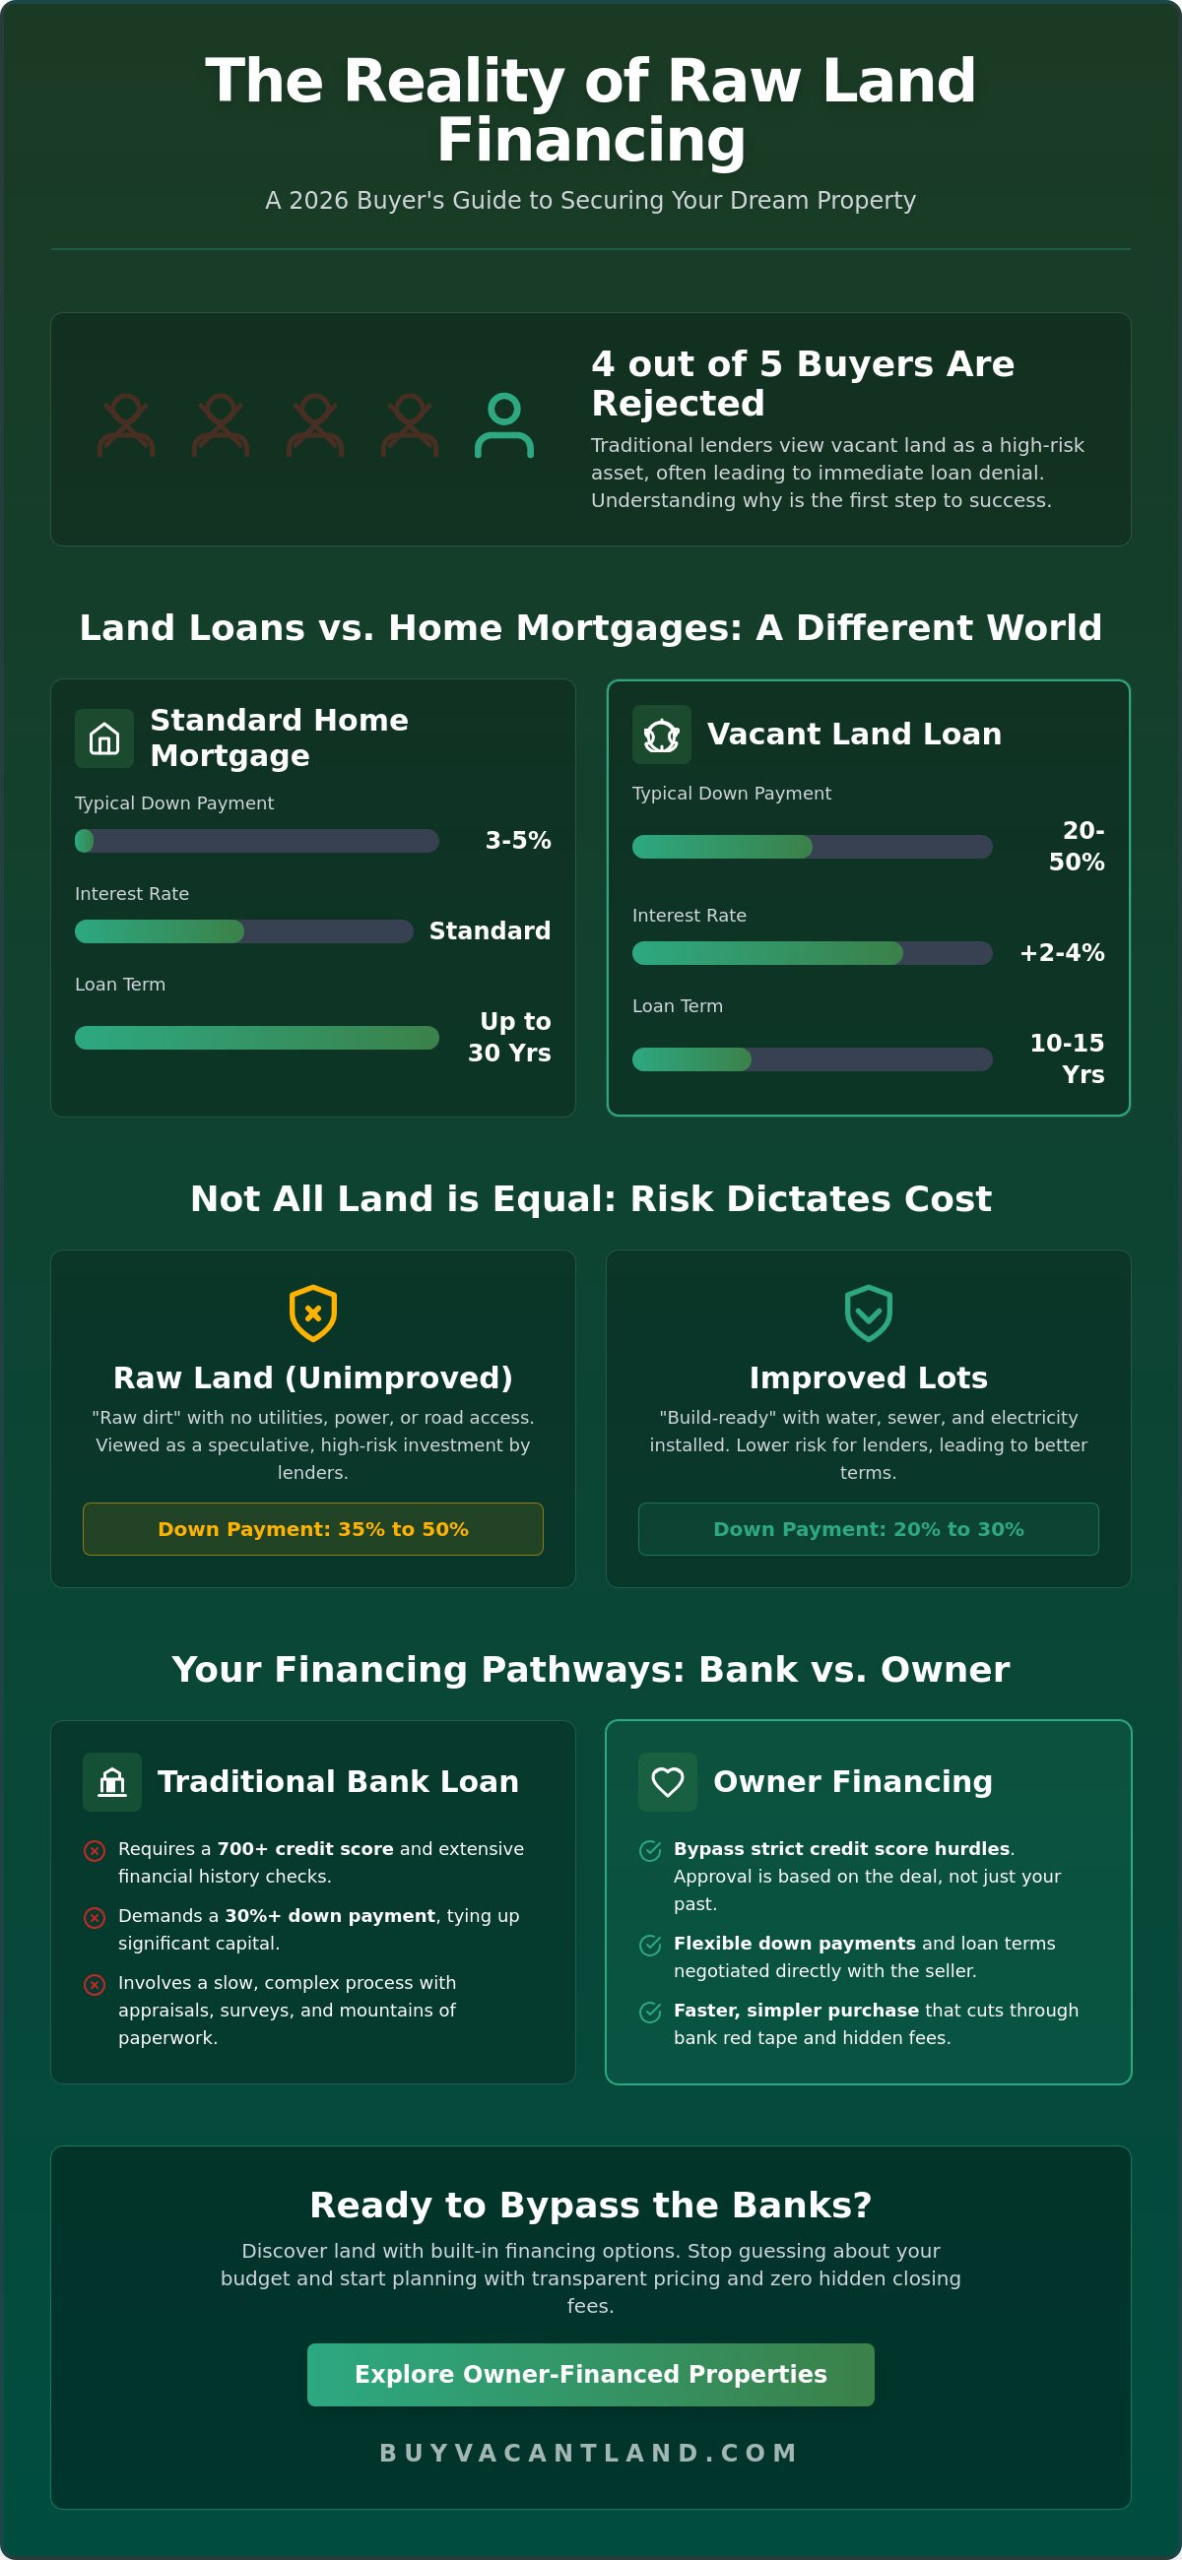
You can't just throw a property address into a generic mortgage calculator and get a reliable answer. Texas land loans operate under different rules, different rates, and different expectations than standard residential financing. I spent about six years working loan files out of a Dallas office before moving to consulting, and I can tell you that the biggest mistake people make is treating raw land financing like it's a conventional purchase. It isn't. A proper land loan calculator for Texas has to factor in several variables that most consumer calculators ignore entirely. Loan-to-value ratios on raw land typically max out around 50 to 65 percent depending on the county and whether the land has utilities. That means you're bringing significantly more cash to the table than you would with a house purchase. Interest rates run higher too—often two to four percentage points above what you'd see on a conventional 30-year fixed. I've seen rates hit 9.5 percent on unimproved acreage in East Texas counties where the bank perceived the location as secondary market at best. The calculator also needs to handle different loan structures. Are you looking at a construction loan where the land gets rolled into the build? A standalone land loan with a balloon payment? A line of credit secured by raw acreage? Each one calculates differently. A typical standalone land loan might be structured as a 5-year term with monthly payments but a balloon payment due at maturity, which completely changes your monthly carry cost versus a fully amortizing loan.
How the Calculation Actually Works
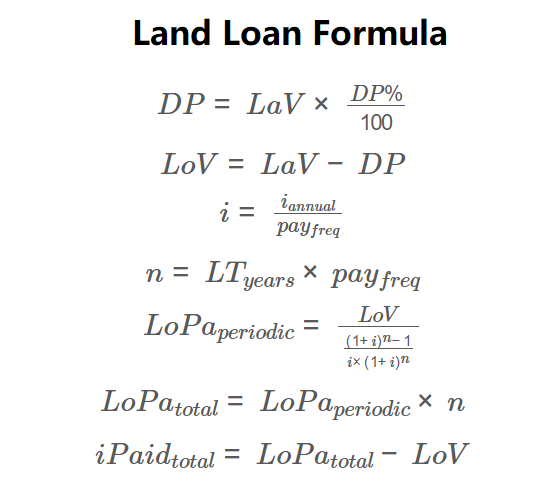
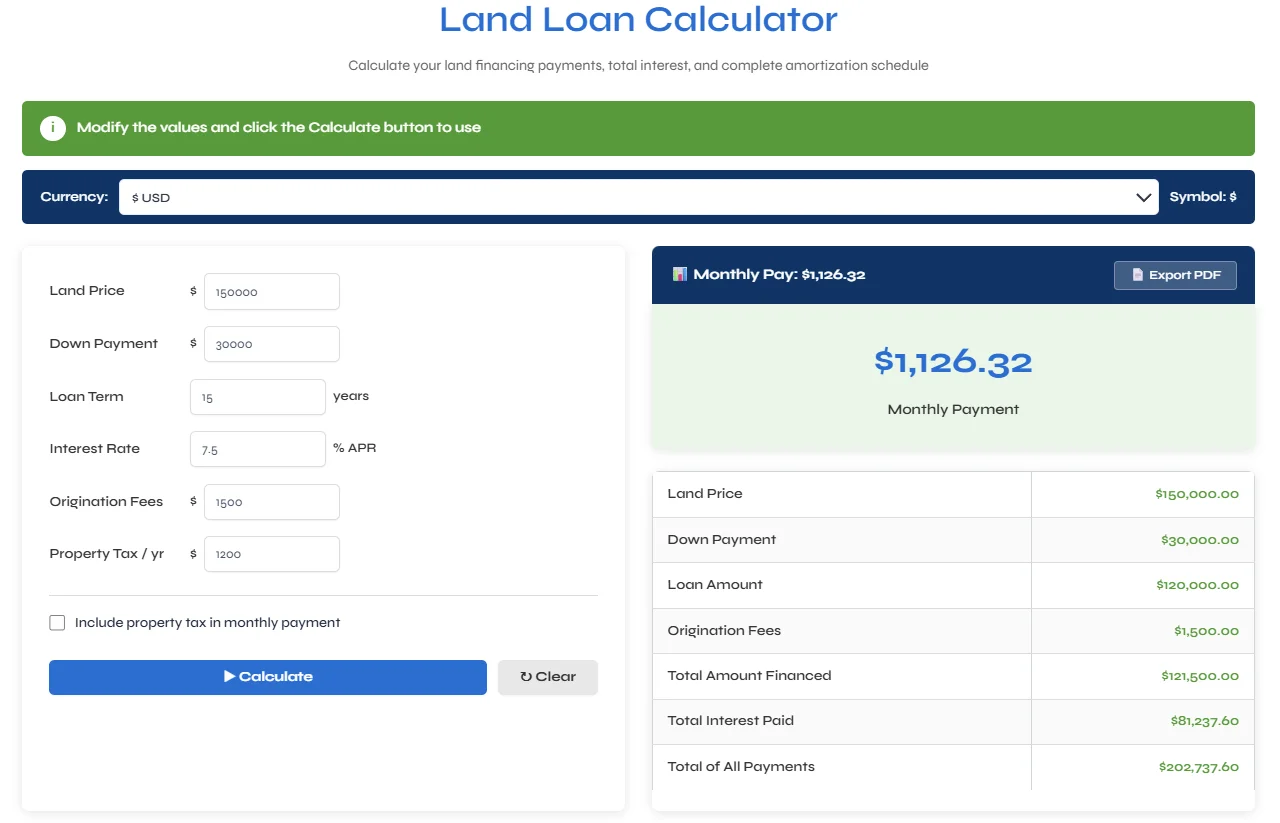
Here's the practical math. Let's say you're looking at a 20-acre parcel in Bell County priced at $150,000. Your lender might approve a 60 percent LTV, which gives you a $90,000 loan. At 8.75 percent interest over a 5-year term with a balloon, your monthly payment works out to roughly $1,477. But that payment only covers interest and a small sliver of principal. At the end of five years, you still owe about $84,000 as a balloon payment. Most people using a basic online calculator never see that balloon coming because the tool assumes full amortization over 15 or 20 years. The payment looks manageable when it's actually not. Down payment is the other big factor. You need at least 35 to 50 percent down on raw land in most Texas markets. If you found that same $150,000 parcel and only had 20 percent down, you're probably looking at private lender options or seller financing, which carry their own complications. Private rates on land in Texas ran between 10 and 14 percent during the last tightening cycle I was tracking. A useful Land Loan Calculator Texas should let you adjust the LTV percentage manually, toggle between balloon and fully amortizing terms, and show you the payoff balance at the end of the term. Without those features, you're just getting a rough estimate that could be off by thousands.
Where I Got Burned and What I Do Now
I once had a client who used a standard mortgage calculator for a parcel near Tyler. The calculator showed a payment of $890 per month, which sounded reasonable on paper. What it didn't show was that the lender required a 45 percent down payment because the property was in a county with no municipal water and the bank classified it as recreational use rather than agricultural. The actual loan came to $270,000 instead of the $180,000 my client planned for. That $90,000 gap meant he had to wait seven months and renegotiate with a different lender who understood rural land valuation in Smith County better. Now I always run two calculations before presenting anything to a client. One using conservative LTV assumptions based on the specific county's typical land loan parameters, and another using the most favorable scenario they're likely to qualify for. If those numbers don't align within about 10 percent of each other, I dig deeper into the property details before proceeding.
Get the Full Details
Counter-Intuitive Things About Texas Land Loans
One thing most people don't expect: agricultural exemption status can actually improve your loan terms in some cases. If the land qualifies for a 1-d-1 agricultural appraisal, lenders sometimes view it more favorably because the lower property tax burden improves your debt service coverage ratio. A parcel appraised at agricultural value might show significantly lower annual taxes than its market value would suggest, which changes the calculation on monthly carrying costs. That said, you can't just claim agricultural use on vacant land you have no intention of farming. The comptroller's office scrutinizes this, and misclassification can trigger penalties that wreck your finances. Another overlooked detail is the difference between improved and unimproved land in the calculator output. Improved land—that's parcels with road access, utility connections, and at minimum a building permit path—commands better LTV ratios and lower rates. Unimproved land is where the rates jump. In some West Texas counties, I've seen unimproved land loans sit at 10 percent or higher while improved parcels in the same area qualified for rates in the 7 to 8 percent range. The gap exists because unimproved land is harder to collateralize if you default. The bank can't sell it easily.
Limitations You Should Know About
No calculator, including a decent Land Loan Calculator Texas option, can accurately predict your exact rate without a full credit review. The numbers I've given you are illustrative ranges based on market conditions from the last few years. Your actual rate depends on credit score, debt-to-income ratio, reserve requirements, and the lender's internal risk appetite for that specific county. Two banks in the same city might quote you completely different terms on the same parcel. Calculators also struggle with the appraisal process. Texas land appraisals are inherently subjective. A parcel might appraise for $7,500 per acre in one county and $12,000 per acre five counties over, depending on comparable sales that aren't always public. The calculator gives you a payment estimate, but the appraisal determines your actual loan amount, and that's where things frequently fall apart. I've seen deals die because the appraisal came in 20 percent below the purchase price and the buyer didn't have the cash to cover the gap. If you're working with raw land and a straightforward financing scenario, a calculator is useful for initial screening. If you're dealing with unusual zoning, environmental restrictions, water rights questions, or fractional ownership, you're better off talking to a Texas-specific land loan broker who understands the local lender landscape. The calculator won't help you with those complications, and relying on it in those situations could put you on a false timeline for closing.