How Land Loans Actually Work When You Put Money Down
Most people treat land loans like home mortgages, and that is where things go wrong immediately. Raw land is considered higher risk by lenders because there is no structure generating income to service the debt. If you default, the bank cannot evict tenants and sell a occupied property. They simply own an empty lot, which depreciates while taxes pile up. The down payment requirement reflects that risk, not some arbitrary number pulled from a spreadsheet. A typical conventional land loan asks for 20 to 50 percent down depending on the type of parcel. Improved land with utilities and road access might get away with 20 percent. Unimproved raw land in a rural area can easily require 35 to 50 percent. You will see some specialized programs like USDA loans that advertise low or zero down payment options for eligible rural parcels, but those come with income limits, geographic restrictions, and longer approval timelines. Most people do not qualify without realizing it until three weeks into the process.
Using a Land Loan Calculator With Down Payment Correctly
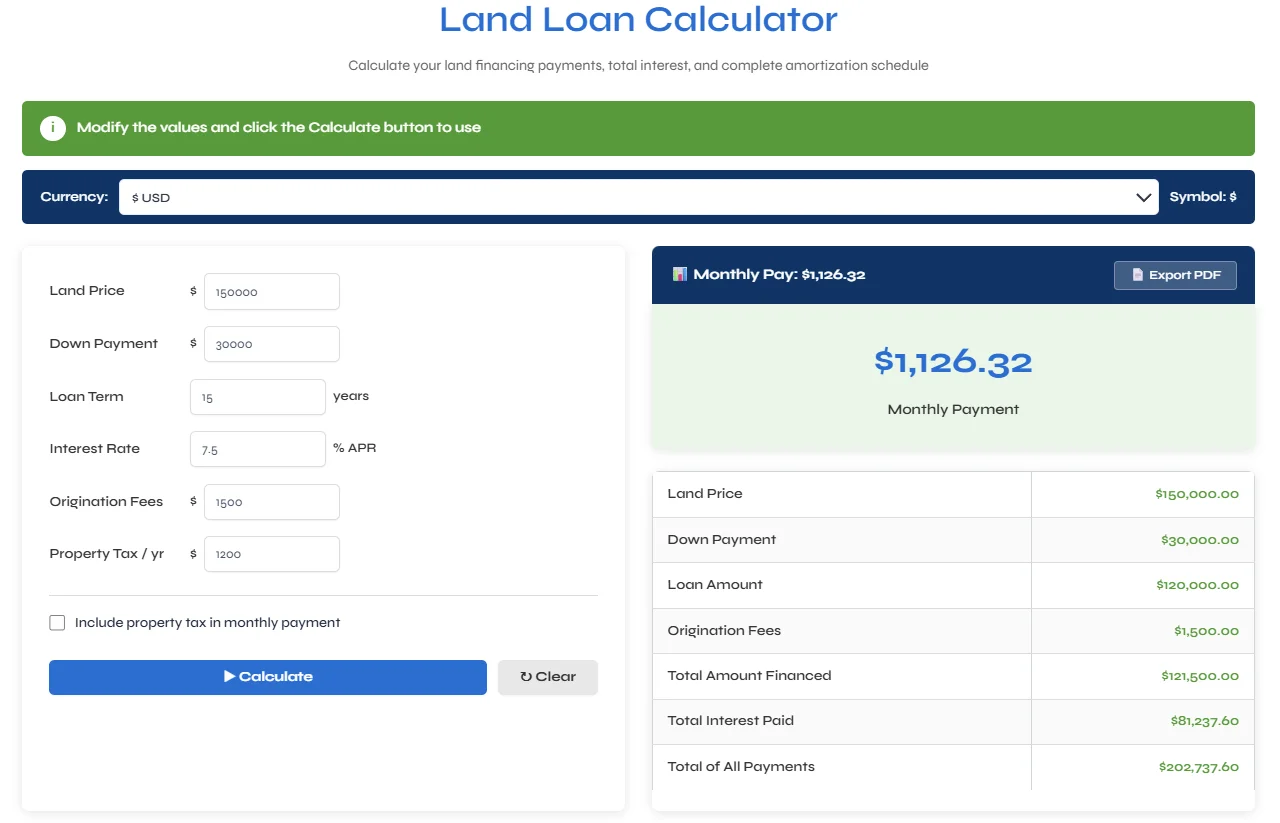
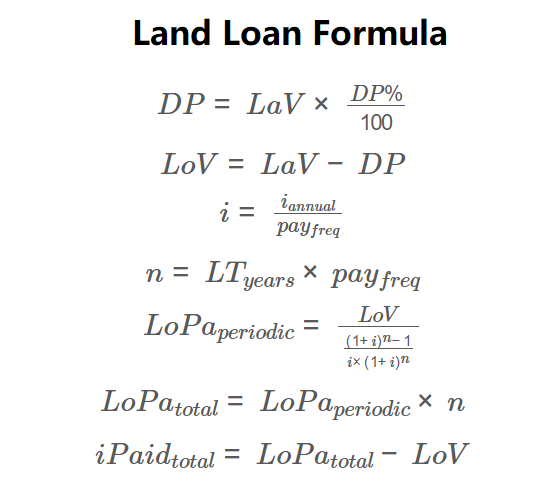
The calculator itself is straightforward. You enter the purchase price, your down payment amount or percentage, the interest rate, and the loan term. It spits out a monthly payment. The problem is that almost nobody factors in the extra costs that make or break a land loan deal. Property taxes on vacant land are assessed the same way as developed land but without rental income to offset them. HOA fees. Survey costs.perc permits. Impact fees. These are not included in any standard calculator output. I ran into this concretely last year with a client who was working with a basic online calculator. He found a parcel listed at $185,000, put 30 percent down, locked in at 8.75 percent over 20 years, and the calculator showed a monthly payment of roughly $2,100. He was comfortable with that number. The actual closing costs ran another $12,400 because the county required a new perc test for the septic system and a boundary survey due to a disputed fence line from 1998. His cash reserves were tapped before he even broke ground. The calculator did not account for either of those expenses. You have to add them manually. When you use a Land Loan Calculator With Down Payment, treat the output as a floor, not a ceiling. Budget at least 10 to 15 percent above whatever monthly payment the tool shows once you layer in closing costs, ongoing taxes, insurance, and any site development you plan to undertake. I usually tell people to run the calculator twice, once with the advertised terms and once with a 2 percent higher interest rate and a 30 percent larger down payment scenario. That second pass tells you what your risk buffer looks like if rates move against you.
There is a technical detail that trips people up regularly. Some lenders structure land loans as amortized mortgages while others use balloon payment terms. A balloon loan might show a lower monthly payment in the calculator because it is only calculating principal and interest over a short term, usually five to seven years, with the full remaining balance due at the end. The monthly payment looks attractive until the balloon date arrives and you need to refinance into a traditional mortgage or sell the land. If the market has softened or your credit has shifted, you are in a difficult position. Always verify whether the loan is fully amortizing or balloon structured before you get emotionally attached to a monthly payment figure. Another counter-intuitive thing worth noting. A larger down payment does not always secure you a better interest rate on land loans. Lenders care more about your debt-to-income ratio, your credit score, and the loan-to-value ratio than they do about the sheer size of your down payment once you pass the minimum threshold. I have seen borrowers put 40 percent down and receive a rate higher than someone who put 25 percent down, simply because the second borrower had stronger income documentation and a cleaner credit profile. Do not assume throwing more money at the down payment is a shortcut to better terms. It is one factor among many, and often not the most important one. The interest rates on land loans are also typically 2 to 4 percentage points above comparable construction or mortgage rates. Right now in mid-2026, you are looking at roughly 8 to 11 percent for a conventional land loan depending on your qualifications and the parcel type. That is not a temporary spike. Lenders price land loans this way structurally because the collateral is less liquid. Even with a solid down payment, the bank is holding an asset that is harder to sell quickly if things go south.
Get the Full Details
If you are set on minimizing the down payment, look into seller financing or lease-to-own arrangements. Some sellers, especially those who inherited vacant land or hold it as a long-term investment, are willing to carry the note at a reasonable rate. This bypasses the traditional lender down payment requirements entirely and often comes with more flexible terms. The trade-off is that you usually need a smaller pool of eligible sellers, and the interest rate may be higher than what a bank offers. You should also ensure there is a clear path to securing traditional financing later if you want to refinance the seller note away. Quick reference for down payment expectations Improved residential lot with utilities: 20 to 30 percent down, amortized over 15 to 20 years, rate around 8 to 9.5 percent.
Raw unimproved rural land: 35 to 50 percent down, amortized over 15 to 20 years, rate around 9 to 11 percent. Farm or agricultural land: 25 to 35 percent down possible through USDA or specialized agricultural lenders, longer terms up to 30 years, competitive rates if you qualify. Land contract or seller carry: down payment varies widely, sometimes 5 to 10 percent, rates negotiated directly, balloon structures common.
The honest limitation here is that land loans are not designed for people who are cash-constrained. The high down payment requirement exists because the lender needs skin in the game from both sides. If you find yourself repeatedly falling short on the down payment requirement, the product you actually need may not be a conventional land loan. It might be a home renovation loan for a fixer-upper with existing structure, a construction-to-permanent loan if you plan to build immediately, or a portfolio loan from a regional bank that evaluates the deal holistically rather than through a standardized calculator output. None of those options are better or worse in an absolute sense. They are just different tools for different situations, and using the wrong one will cost you money whether the calculator says otherwise or not.