Raw land loans don't work like house loans, and most online calculators will lie to you about it.
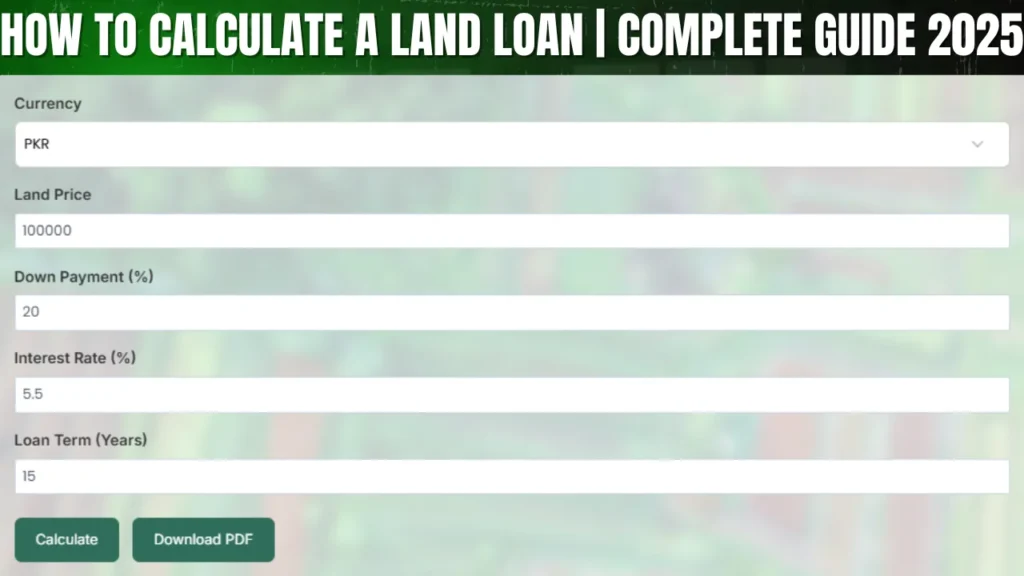
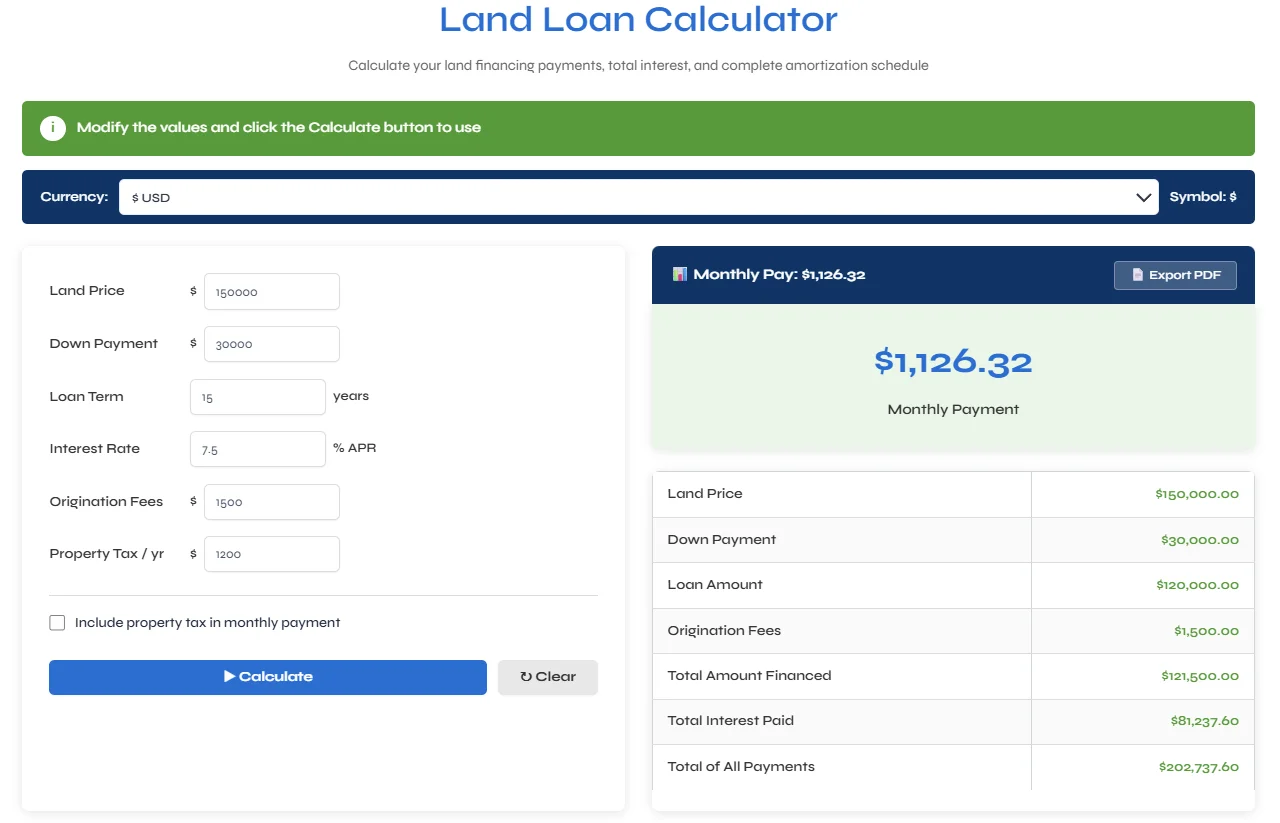
I built a Land Loan Estimator after spending three years watching people get blindsided by land loan terms they didn't expect. The standard mortgage calculator on every bank's website doesn't apply here. Vacant land is treated as a higher-risk collateral by every lender I've worked with, which means the numbers you'll see in practice are significantly steeper than what a home purchase would look like. The core function is straightforward: you input the loan amount, interest rate, and term, and it produces a monthly payment estimate using the standard amortization formula. But the part that trips people up is figuring out what those inputs actually should be for raw land. Down payments typically run 20 to 50 percent depending on whether the lot is improved or raw, and interest rates sit somewhere between 7 and 13 percent. A $100,000 land loan with 30 percent down at 9 percent over 15 years comes out to roughly $760 a month, but don't assume that's the total carrying cost.
How to use the Land Loan Estimator properly
Start with the purchase price, then subtract whatever down payment you're actually qualified for rather than the minimum. Lenders will approve you at the floor, but putting only 20 percent down on raw land often means private money rates instead of institutional rates. The difference between 9 percent and 12 percent on a 15-year note is about $85 per $10,000 borrowed each month. That compounds fast. Next, pick the term. Most land loans are 15 to 20 years. Some are structured as 10-year balloon payments where you refinance or sell before the term ends. If you're building immediately, a construction-to-permanent loan might be the better route, but those require you to have a builder contracted before closing. The estimator defaults to a standard amortizing loan because that's the baseline most people encounter. Enter the interest rate as an annual percentage rate, not a monthly rate. I've seen people enter 0.75 thinking it's monthly and end up with a payment that's roughly 9 percent too low. The calculator assumes monthly compounding, which matches how most lenders report land loan rates. If your quote is an APR that includes points and fees, it'll be slightly higher than the note rate, and the monthly payment will reflect that difference.
One thing the estimator doesn't automatically include is property taxes and insurance, which still accrue on raw land even if there's nothing built on it. In my experience, those run about 0.5 to 1.5 percent of the assessed value annually, depending on the county. On a $100,000 parcel, budget another $50 to $125 a month on top of the loan payment.
Get the Full Details
A problem I ran into that isn't obvious from the documentation
Last year I was working with a parcel that was legally sub-divided but the survey described it as a trapezoid, not a rectangle. The lender's internal appraisal model flagged it as "non-standard shape" and applied a 15 percent hair cut to the value, which effectively raised the loan-to-value ratio and pushed the borrower into a higher rate tier. The Land Loan Estimator doesn't account for shape adjustments because it only takes price, down payment, rate, and term as inputs. I had to manually adjust the effective loan amount upward by 15 percent and recalculate to give the borrower a realistic number. Most people wouldn't catch that unless they'd seen a lender's automated underwriting flag it first. Another issue is road access. If the parcel doesn't have frontage on a public road, some lenders classify it as inaccessible and require a 50 percent down payment or decline the loan entirely. The estimator can't predict this because it requires a parcel-level check against county records. Before you trust any calculated payment, confirm the lot has legal road access or a recorded easement. It's a two-minute check with the county assessor's office that saves you from wasting time on a loan you can't get approved for.
When the Land Loan Estimator gives you wrong answers
The tool breaks down in a few specific scenarios, and knowing those matters more than knowing how to use it correctly. First, it assumes the loan is fully amortizing. If your lender offers an interest-only period, the payment during that window is just the monthly interest, which is dramatically lower, then jumps once amortization kicks in. A $100,000 loan at 10 percent for five years interest-only followed by a 15-year amortization schedule would show a payment of about $833 during the IO period and roughly $1,075 afterward. The estimator will average these into a single incorrect figure if you're not careful about splitting the calculation. Second, it doesn't handle adjustable-rate land loans, which are common in the current market. Some lenders offer a 5/1 ARM on land where the rate starts lower but resets annually after year five. The initial payment might look attractive at 7 percent, but once it adjusts to 11 percent, the payment increases by about 22 percent. Planning for the initial rate alone is a mistake. I always run the estimator twice: once at the start rate and once at a conservative 3-percent adjustment ceiling. Third, land loans in certain counties carry special assessments or improvement district fees that get rolled into the monthly payment. These aren't part of the loan principal or interest, so the estimator has no way to factor them in. You need to contact the local municipal authority or check the title report for any MUD, SID, or improvement district obligations. Skipping this step once cost a borrower an extra $210 a month they hadn't budgeted for, and they nearly defaulted in year two when they couldn't cover the gap.
If you need something that accounts for shape adjustments, road access issues, and special assessments, a full underwriter evaluation is the only reliable path. The estimator is a planning tool, not a pre-approval substitute. Use it to scope whether a parcel is in your ballpark, then take the numbers to a lender who actually does land loans. Most community banks and credit unions handle them. National mortgage lenders largely don't anymore, which is why the options shrink fast once you move past the estimation phase.