What a Land Payment Calculator Actually Does
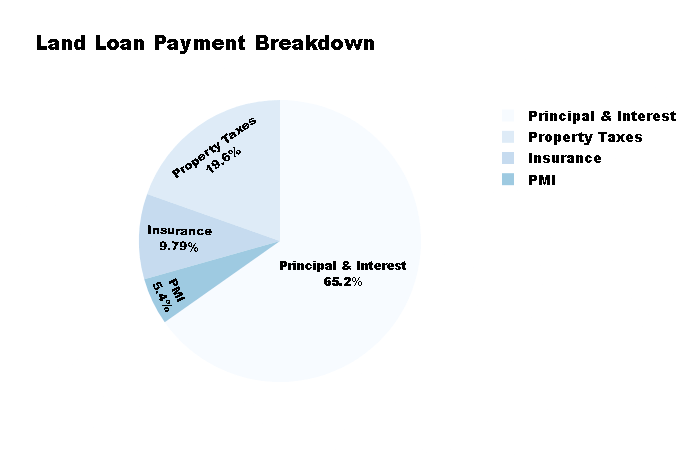
A Land Payment Calculator figures out what you'll pay each period when buying land, similar to how a mortgage calculator works but with some distinct differences. Land loans tend to have higher interest rates, shorter terms, and larger down payments than standard home mortgages, so the numbers come out differently. You put in the total purchase price, your down payment, the interest rate, and the loan term, then the tool spits out your monthly payment. It's not magic, just the standard amortization formula applied to a different set of inputs. Most online versions follow the same pattern. You enter the purchase price of the land, your down payment amount or percentage, the annual interest rate, and the loan term in years. The calculator then computes your monthly payment and can usually show you an amortization schedule too. Some tools let you adjust property taxes and insurance into the figure, which matters because land loans often don't include those in escrow the way home loans do. I found this out the hard way about three years ago when I was helping a client evaluate a parcel near Portland. The calculator they were using showed a clean $1,420 monthly payment on a $180,000 lot at 9.5% for 15 years. But when we added county property taxes at roughly $800 annually and the required hazard insurance, the real number jumped to about $1,530. The calculator didn't account for those because the tool was built for pure loan payment estimation. I had them run the tax and insurance figures through a separate spreadsheet and add it manually. Worked fine once we figured that out.
The actual formula behind these calculators uses the standard amortization equation: your monthly payment equals the principal times the monthly interest rate, divided by one minus one over one plus the monthly rate raised to the total number of payments. It's the same formula lenders use. The calculator just does the arithmetic so you don't have to. You can verify the result yourself in Excel with the PMT function if you want to double-check, which I'd recommend doing before signing anything.
Common Mistakes People Make
The biggest issue I see is people treating a Land Payment Calculator output as final without considering the actual loan terms available to them. Many online tools assume conventional financing rates around 6 to 7 percent, but land loans commonly sit between 8 and 12 percent depending on your credit score and whether the land is improved or raw. Using a standard mortgage rate in your calculator will make the payment look much lower than it actually will be. Another frequent problem is ignoring the down payment requirement. Most lenders want at least 20 to 50 percent down on land, compared to 3 to 5 percent for a house. If you input a 5 percent down payment into the calculator and then get quoted a 30 percent requirement by the actual lender, your monthly payment estimate is completely wrong. Run the calculation at multiple down payment scenarios to see how much it shifts the number. Seller financing and lease-to-own arrangements are another area where these calculators break down. A Land Payment Calculator assumes a traditional amortizing loan with a fixed rate and term. If you're dealing with owner carry or a land contract, the payment structure might be interest-only for several years, balloon payments might apply, or the rate might adjust. None of that shows up in a standard calculator output.
Get the Full Details
There's also the issue of lot size and zoning affecting your costs in ways the calculator can't predict. A calculator won't tell you that a 40-acre parcel might need a well and septic system instead of municipal connections, which adds significant carrying costs. Or that a parcel zoned agricultural might have different tax implications than residential. These aren't payment variables, but they affect whether you can actually afford the deal.
When a Land Payment Calculator Falls Short
Plainly stated, these tools are estimates. They give you a monthly payment figure based on ideal assumptions. Real land loans involve appraisal fees, survey costs, title insurance, environmental assessments, and sometimes impact fees that add thousands to your closing costs. The monthly payment might look manageable at $1,200, but you could need $15,000 in cash at closing. That gap between the calculator number and your actual cash requirement is where people get stuck. If you're looking at raw land with no utilities or road access, the payment calculator is barely useful. You need to factor in the cost of bringing services to the site, which can range from $10,000 to over $100,000 depending on terrain and distance to existing infrastructure. A better approach is to get actual quotes from contractors for site development, add those to your total project cost, and then use the calculator on the financing portion separately. For vacant land purchases, some buyers skip the calculator entirely and just call three lenders to get pre-qualification numbers. That gives you real rates and terms instead of hypothetical ones. The calculator is still useful for quick back-of-the-envelope math, but it shouldn't replace actual lender conversations. Rates change weekly, and your personal rate will depend on credit history, debt-to-income ratio, and how much equity you're putting down.
The tool also doesn't account for loan programs specific to agricultural or conservation land. USDA loans, for example, offer below-market rates for qualifying buyers on eligible rural property. A standard calculator won't reflect those favorable terms unless you manually adjust the interest rate input. If you think you might qualify for a government-backed program, research that first and then use the calculator with the actual program rate rather than a generic one.