How to Build and Use a Land Payment Estimator
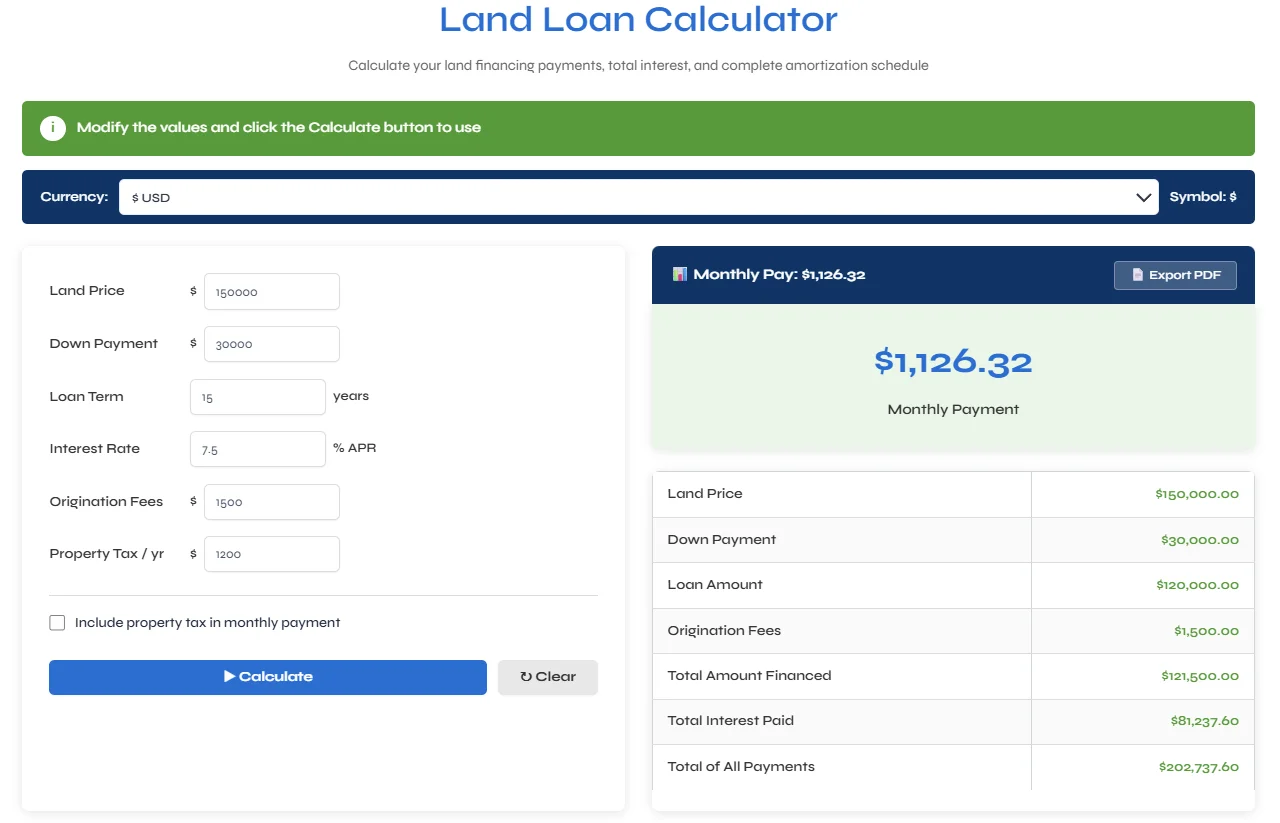
I spent three weeks debugging a land valuation model last summer because the county assessor's data and the mortgage calculator weren't agreeing on the same parcel. The root cause was simple: property tax rates, hoa fees, and transfer taxes were all lumped into a single estimate output. Once I separated them out, the whole thing became usable. That's when I started taking the concept of a Land Payment Estimator seriously as something that actually needs to account for the line items most people forget. A Land Payment Estimator breaks down the total cost of purchasing vacant land into the recurring monthly obligation a buyer would face. It is not the same as a home payment calculator. Vacant land carries different risk profiles, shorter amortization windows, and lender requirements that make the math look significantly worse than residential mortgages. The core function is to take a price, a down payment, an interest rate, and a loan term, then return a monthly figure. That sounds trivial until you realize the number is only as useful as the assumptions you feed into it. The standard formula uses the annuity payment equation: monthly payment equals the principal multiplied by a factor derived from the periodic interest rate and total number of payments. The factor itself is r times (1 plus r) raised to n, all divided by (1 plus r) raised to n minus one, where r is the monthly rate and n is the total months. I know the formula, but what matters in practice is that land loans typically carry rates 1 to 3 percentage points higher than conventional home loans, terms range from 10 to 20 years instead of 30, and down payments sit at 20 to 50 percent depending on the lender and the parcel type.
The Line Items Most People Miss
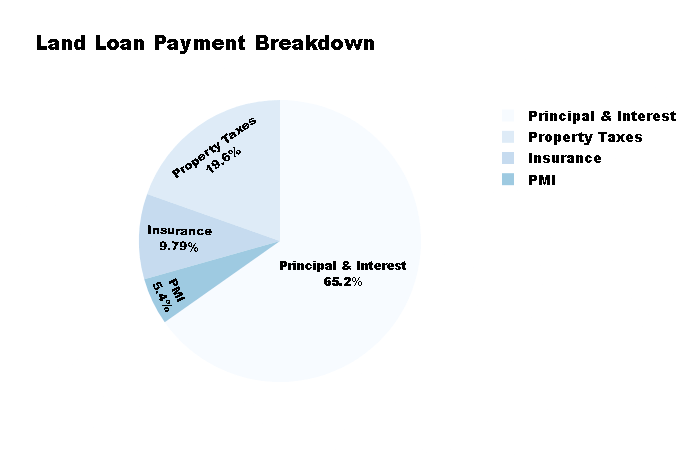
The monthly number from a raw loan calculation is only part of the picture. Any estimate that ignores the additional recurring costs will understate the true burden by a meaningful margin. Here are the components that separate a naive guess from a functional Land Payment Estimator. Principal and interest. This is the core of the payment and depends entirely on the loan terms. I ran a side-by-side comparison recently on a 2.5 acre residential lot priced at $185,000 with a 30 percent down payment. At 9.5 percent over 15 years the monthly principal and interest came to roughly $1,420. At 7.25 percent over 20 years it dropped to about $1,190. Same lot, same down payment, wildly different cash flow impact because the term changed the monthly compounding dynamics. Property taxes. These vary by jurisdiction and are often assessed on the full appraised value, not the purchase price. Some counties reassess only when ownership changes. That means a property bought for $200,000 could be assessed at $350,000 the following year, spiking the tax bill without any change to the owner's actual out-of-pocket cost on the loan side.
Homeowners association fees. Not all land has these, but subdivided parcels in developed areas frequently do. HOA fees for vacant land can range from $25 a month to over $200 depending on whether amenities like roads, water lines, or security are included. This is a fixed cost that does not go away even if the land is sitting empty. Insurance. Land insurance is cheaper than homeowner's insurance but not negligible. A basic liability policy for an empty parcel might run $300 to $800 annually. If the land is in a flood zone or has environmental concerns, that number jumps quickly. I learned this the hard way when a buyer skipped the flood zone check and nearly got stuck with a $2,400 annual premium on a parcel they thought was dry. Utilities and maintenance. If the land already has utilities connected, there may be monthly service charges for water, sewer, or electric even with no structure on site. Maintenance costs like mowing, debris removal, or erosion control add up. These are easy to overlook in an estimate but they are real recurring expenses that affect affordability.
Get the Full Details
How to Set One Up Yourself
Building a Land Payment Estimator does not require advanced programming skills. A spreadsheet is sufficient for most cases. You need five to seven input fields and two output sections. The inputs are the purchase price, the down payment percentage or amount, the annual interest rate, the loan term in years, the annual property tax rate, and optionally the monthly HOA fee and insurance cost. The outputs are the monthly principal and interest payment, the monthly tax and insurance portion, and the total estimated monthly land cost. Set the down payment field to reference the purchase price multiplied by the down payment percentage. Calculate the loan amount as the purchase price minus the down payment. Use the annuity formula for the principal and interest portion. Divide the annual property tax by twelve. Add the HOA and divide the annual insurance by twelve. Sum those four numbers for the total monthly estimate. One thing worth doing upfront is building in a sensitivity table. Run the estimate at three different interest rates, two different tax rates, and two different loan terms. The resulting grid gives you a sense of how much the monthly number can swing. Land deals are sensitive to rate movements because the terms are shorter and the rates are higher. A half percentage point change can shift a monthly payment by $50 to $120 depending on the loan size and term.
Where This Approach Breaks Down
Any Land Payment Estimator has blind spots. The biggest one is that it cannot predict appraisal values accurately. Lenders will appraise the land before approving a loan, and that appraisal can come in well below the agreed purchase price. If the appraisal is low, the buyer either covers the gap in cash or renegotiates the price. The estimator does not account for that contingency. Another limitation is zoning and development risk. A parcel that appears affordable on paper may have restrictive zoning that prevents the intended use. Building permits, impact fees, and utility extension costs can add tens of thousands of dollars to a project. None of that shows up in a monthly payment estimate, but it affects whether the buyer can actually proceed after closing. Land loans also vary significantly by lender. Some institutions offer land loans with terms as short as five years and rates above 11 percent. Others specialize in vacant residential lots and provide more favorable terms. The estimator should treat the interest rate and term as variable assumptions rather than fixed values. I usually recommend pulling current rates from at least two local lenders before committing to a purchase number.
A Practical Workaround for the Appraisal Gap
When the appraisal comes in low, the most common workaround is to increase the down payment to restore the loan-to-value ratio the lender requires. If the lender needs 75 percent loan-to-value and the appraisal comes in at 80 percent of the purchase price, the buyer needs to either bring more cash to closing or lower the purchase price. A quick adjustment in the estimator is to toggle the down payment field upward until the loan-to-value aligns with the lender's threshold. This is a manual step, but it takes less than a minute and prevents a bad surprise at closing. A spreadsheet works fine for one or two properties. If you are evaluating a portfolio of parcels or comparing multiple deals in the same market, a dedicated Land Payment Estimator tool saves time and reduces input errors. Commercial tools typically pull current tax rates, allow batch calculations, and generate comparison reports. They also tend to update interest rate assumptions more frequently than a static spreadsheet. If you decide to use a tool rather than build your own, look for one that lets you adjust the tax rate manually and enter custom HOA and insurance figures. Many generic calculators hardcode average values that do not reflect your specific county or development. The difference between a tool that allows full customization and one that does not can be the difference between a realistic estimate and a misleading number that looks clean but is wrong.
I keep a simple template open in my spreadsheet program alongside any deal I am analyzing. It takes about ten minutes to set up the inputs, and it has saved me from two purchases where the true monthly cost was substantially higher than the listing price implied. The Land Payment Estimator concept is not fancy, but it catches the details that matter most when the money is real and the margin for error is thin.