How to Calculate What You're Actually Paying for a Plot of Land
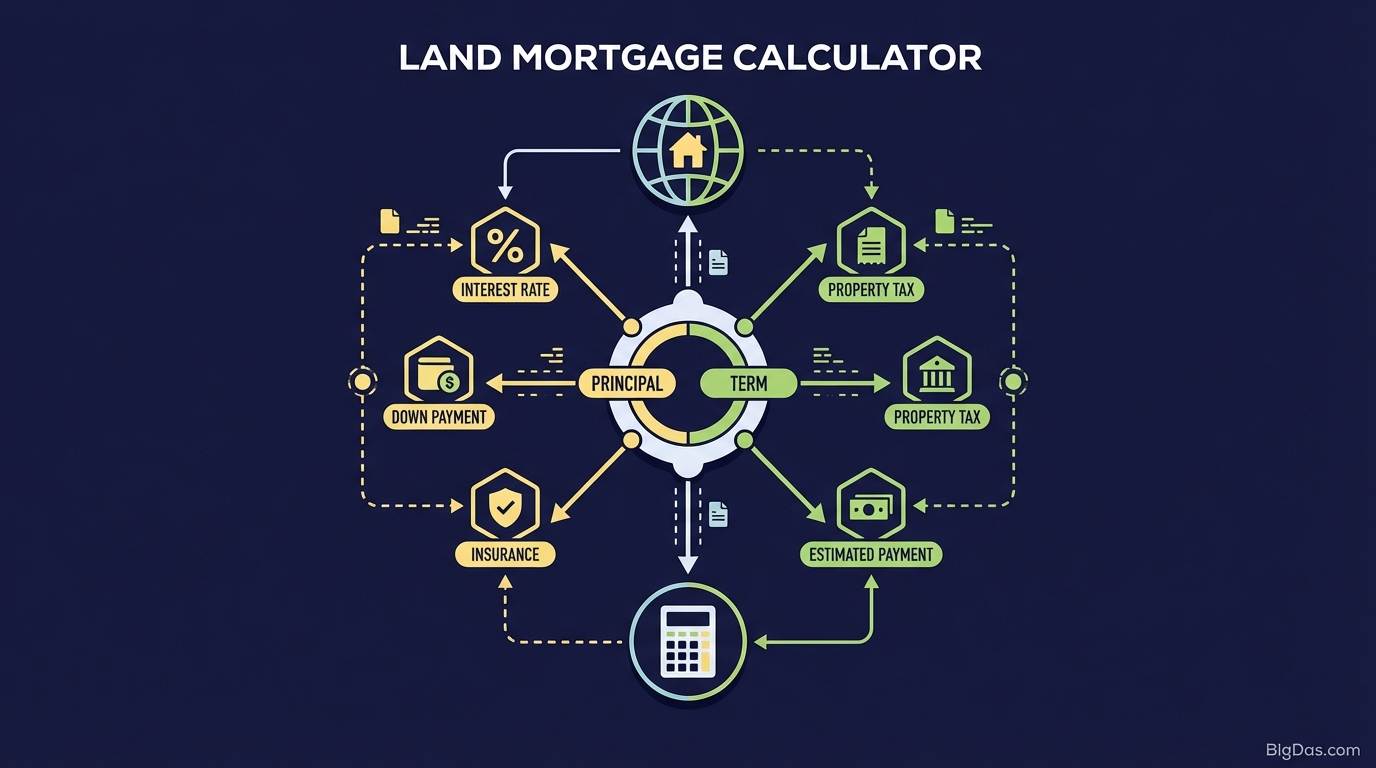
The big question most people ignore when buying land is the gap between the list price and the actual out-the-door cost. I have sat across from real estate agents who quoted a clean per-acre price, only to watch the closing number jump by thirty percent once all the hidden charges piled up. This happens constantly. It does not have to happen to you. A Land Purchase Calculator is simply a spreadsheet or app where you feed it the list price plus every ancillary charge so the tool can spit out a single bottom-line number. You enter the base price, the acreage, the transfer tax rate, any stamp duty, surveyor fees, title search costs, environmental assessment fees, and whatever escrow or closing costs your county charges. The tool sums it all and gives you a cost-per-acre figure and a total liability. I built my own version around 2018 because none of the free online calculators let me account for variable rates. Most of them assume a flat tax, which is wrong for roughly eighty percent of counties in the United States. Transfer taxes are frequently tiered. They change at certain price thresholds, and some municipalities add an extra surcharge for vacant land that residential properties do not trigger. If you use a calculator that does not handle tiers, your estimate will be off by thousands of dollars on a mid-range purchase.
Here is the workflow I actually use. I open a blank Google Sheet and set up columns for the base purchase price, acreage, transfer tax tier, stamp duty rate, recording fee, survey cost, environmental assessment fee, title insurance premium, escrow fee, and any outstanding liens I expect to absorb. I add a conditional formula that selects the correct transfer tax bracket based on the sale price rather than applying a single flat percentage. I also build in a column for a ten percent contingency buffer because you will always find something at the end you did not predict. When the calculator finishes, you get a line item breakdown and a total. You then compare that total to your financing terms, your cash reserves, and your absolute maximum budget before you make an offer. That comparison step is the whole point. You are not calculating to impress anyone. You are calculating so you do not bid against yourself with incomplete information. I will share a specific problem I ran into that most calculators do not warn you about. A client once used a standard land purchase calculator and came in twenty-two thousand dollars under their actual closing cost. The missing piece was a municipal impact fee for a new subdivision in Austin. The county adds a per-lot fee for infrastructure that ranges from twelve thousand to forty thousand dollars depending on the zoning district, and the listing price never mentions it. The calculator had no field for municipal impact fees because they are non-standard. I added a manual input row labeled "municipal and special assessments" and made it a hard requirement for any Texas purchase after that. If you are buying outside the major metros, you need to research these fees yourself before the calculator can even approximate them.
The Numbers You Need to Get Right
The first input is the raw purchase price, obviously. But you need to decide whether you are bidding on the gross land area or the buildable acreage. Survey companies often report gross acreage, and the tax assessor may use the same gross number, but the net buildable area is what determines your true cost per usable unit. I had a case where a buyer thought they were getting three buildable acres for a million dollars. After the survey came back, only two acres cleared the zoning setback requirements and the wetlands delineation. Their actual cost per buildable acre was fifty percent higher than their original calculation. Always run the numbers on both gross and net acreage so you know which scenario you are actually facing. Transfer taxes deserve more attention than they get. Some counties charge a flat rate per thousand dollars of value. Others use a sliding scale that jumps at specific price points. A few states impose a separate real estate transfer surcharge on cash deals that does not apply to financed transactions. Your calculator needs to reflect whichever system your county uses. If you pull the rate from the wrong source, you will understate your closing cost. The county clerk's website is the only place that matters. Do not trust the state revenue department page for this because the state rate and the county rate are often different. Stamp duty exists in certain states and Canadian provinces. It is calculated on the deed, not on the contract. That distinction matters because the deed value can differ from the purchase price if you are assuming existing liens or taking property subject to an easement with compensation. Most calculators I have seen default to the purchase price. That is usually close enough, but it is not always accurate, and the difference shows up as a surprise at closing.
Get the Full Details

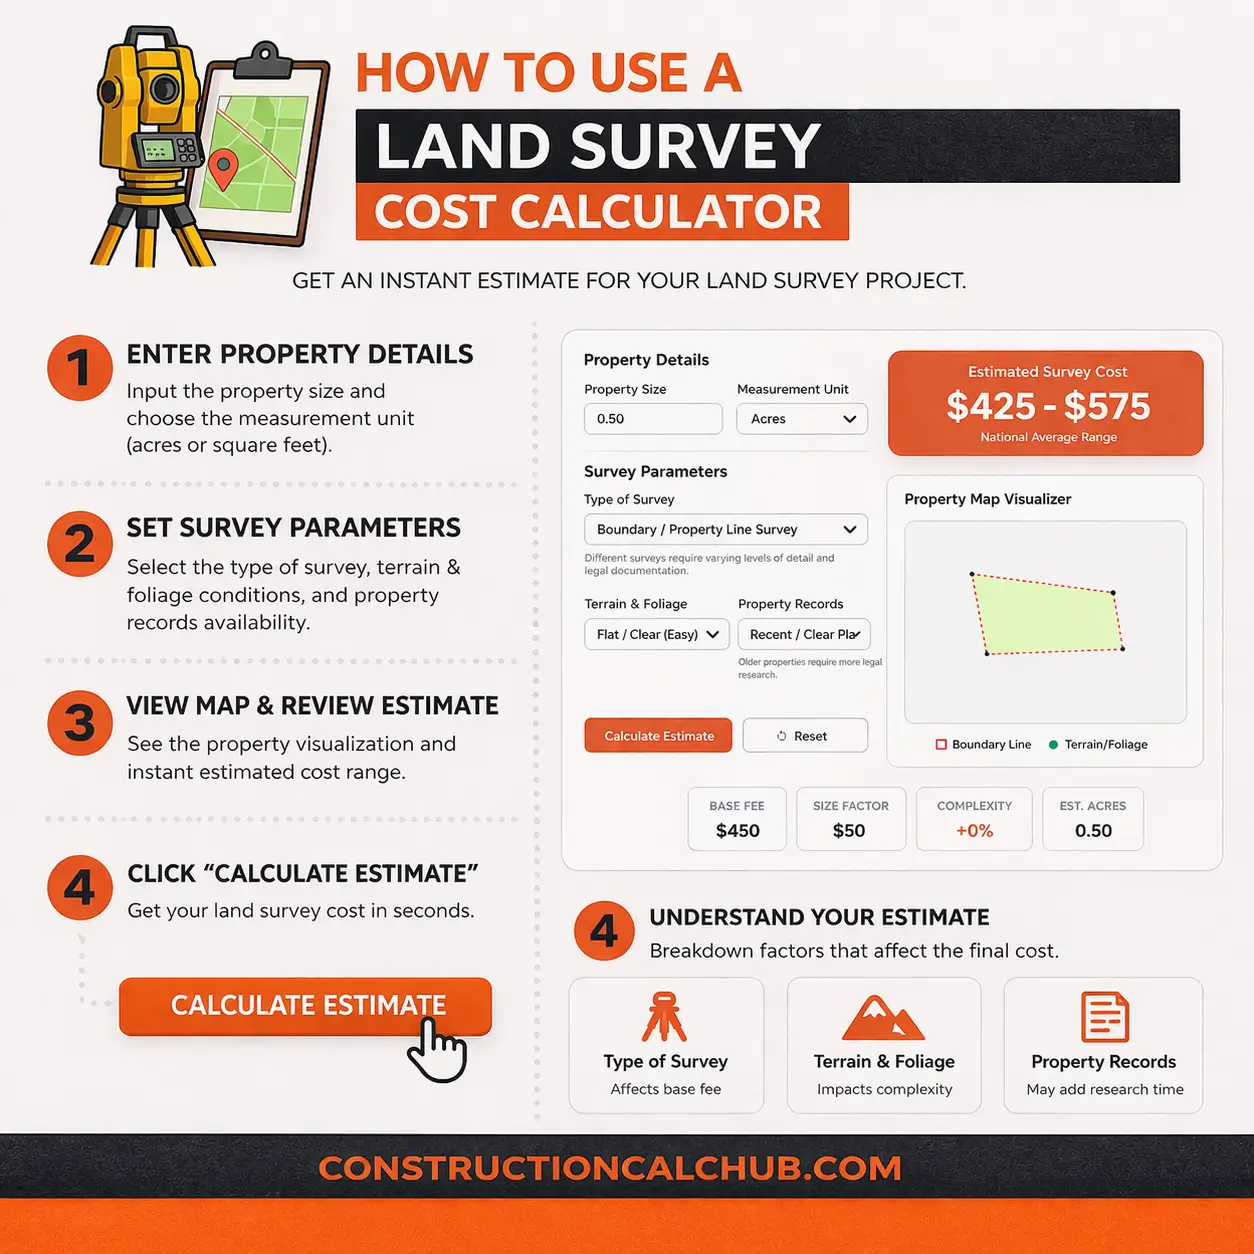
Survey and title costs are relatively predictable. A boundary survey runs between eight hundred and two thousand five hundred dollars depending on acreage and terrain. A title search and insurance package for raw land typically costs between one thousand and three thousand dollars. These numbers do not fluctuate wildly, so you can bake them into your estimate with confidence. The unpredictable items are environmental assessments, soil tests, and perc tests if you plan to install a septic system. A Phase I environmental assessment for a vacant parcel runs between fifteen hundred and four thousand dollars. A perc test runs between five hundred and one thousand two hundred dollars. If the seller already has a recent perc test on file, you can often skip your own, but verify the date. Most counties require the test to be less than five years old. An old perc result is not worth much at closing.
What the Calculator Will Miss
No calculator, including my own, will automatically catch every possible charge. Here is what usually falls through the cracks. First, outstanding utility extension fees. If the road to the parcel is a private gravel drive and the county requires you to bring utilities to the lot line before they will approve a building permit, that can cost anywhere from five thousand to fifty thousand dollars depending on distance and terrain. Second, easement conflicts. If a neighbor's drainage easement crosses your intended build site, you may need to negotiate a relocation agreement or redesign the foundation, which adds engineering fees and legal costs. Third, unrecorded liens that surface during title search. Agricultural equipment liens, mechanic's liens from old grading work, or HOA violations from a neighboring subdivision can all appear late. Your contingency buffer should be large enough to cover at least one of these surprises, ideally two. There is also the financing angle. Lenders treat raw land differently than residential property. Loan-to-value ratios for land loans typically top out at fifty percent to sixty-five percent. Interest rates are higher, often by one to two percentage points, and the amortization period is shorter. Some lenders require interest-only payments for the first few years. If you are factoring in financing costs, you need to include the actual rate and term your lender will offer, not the rate you saw for a conventional home loan. A land purchase calculator that assumes a standard mortgage rate will dramatically understate your monthly obligation.
Building the Spreadsheet Yourself
If you want a functional tool that does not miss the edge cases, here is exactly how I structure mine. The first section captures the inputs: purchase price, legal description reference, county, parcel number, gross acreage, estimated net buildable acreage, and the date you are running the numbers. The second section lists all the fee categories with fixed values and variable rates. I separate the variable rates because they change by jurisdiction, and I put each jurisdiction's rates in a lookup table so I can swap counties without rebuilding the sheet. The third section contains the formulas. The transfer tax formula uses a VLOOKUP against the tiered rate table. The stamp duty formula applies the correct rate based on the state column. The survey and title columns pull from the lookup table or accept manual overrides when the county has unusual fees. The environmental assessment column defaults to a midpoint estimate but allows manual adjustment if you already have quotes. The contingency column is set to ten percent of the subtotal, which you can change later if the property is in a high-risk zone. The output section shows the subtotal, the total estimated closing cost, the cost per gross acre, the cost per net buildable acre, and the financed down payment and monthly payment if you include loan terms. I also add a sensitivity range that shows the low, mid, and high scenarios by adjusting the contingency percentage and the transfer tax tier. This lets you see the worst case without having to re-enter anything.

I do not recommend buying a commercial land calculator for this unless you are managing a portfolio. The spreadsheet approach takes about an hour to set up the first time, and after that you just update the county lookup table when you change locations. That setup time pays for itself on the first transaction where you catch a tiered tax bracket that the generic tool missed.
When to Walk Away
The most useful output from this process is not the total number. It is the moment you realize the adjusted cost per buildable acre exceeds your pro forma budget. I have seen buyers fall in love with a parcel, sign the contract, and then discover that the impact fees alone wiped out their margin. Once the calculator shows you the real number, you either renegotiate the purchase price to accommodate the hidden costs or you walk. There is no shame in walking. Land contracts often have inspection and due diligence contingencies for a reason. Use them. One final note on reliability. This calculator gives you an estimate, not a guarantee. The actual closing statement will differ because some fees are finalized only after the title company completes their search and the county records the deed. A typical variance is between five percent and twelve percent from your initial estimate, provided you included the county-specific rates and accounted for impact fees where applicable. If your variance is larger than that, you probably missed a category. Go back through the checklist and find it before you sign the closing documents.