Working With McLachlan's Laplace Transform Textbook
I picked up the McLachlan book around 2018 when I needed to brush up on solving ODEs for a simulation project. I had been using Laplace transforms in undergrad and assumed I'd remember the procedure. I did not. The approach in this book is refreshingly practical, but it will eat you alive if you skip the earlier chapters and jump straight into the PDE stuff. The writing is dry. The examples are worked out in full. That is its main strength. The book covers the standard curriculum: definition and basic properties, solving linear ODEs with constant coefficients, partial fractions and inverse transforms, convolution, and then moves into PDEs and integral equations. It is not heavy on theory. You will not find rigorous proofs of existence theorems here. If you need that, look elsewhere. This is a methods book.
Laplace Transforms And Their Applications To Differential Equations N W Mclachlan
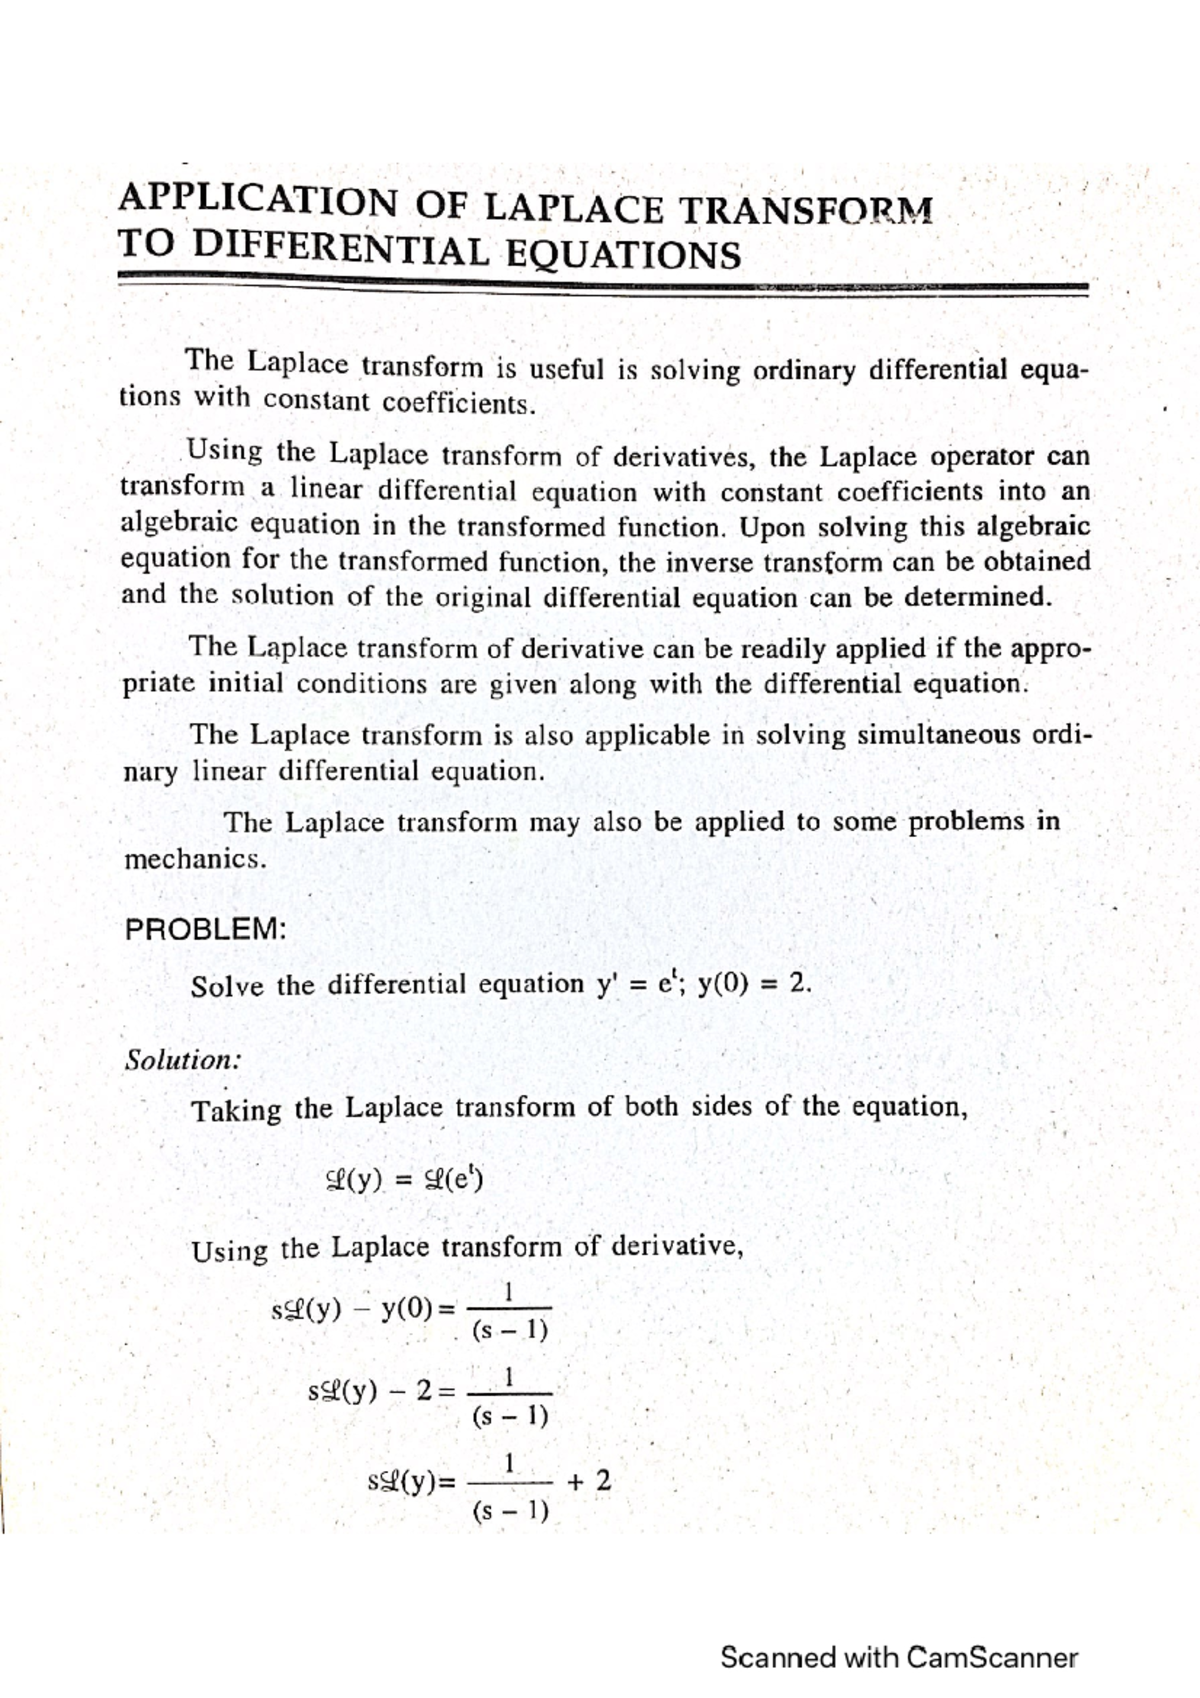
Here is how the method actually works in practice, which is different from how most lecture notes present it. You take your ODE, apply the transform to every term, use the derivative property to convert d/dt terms into algebraic expressions involving s, solve for Y(s), then invert. The inversion step is where everything falls apart for students. McLachlan handles this with tables and partial fraction decomposition, which is the standard route and the only route that matters in most engineering work. The partial fraction chapter deserves more attention than it gets. When you have repeated roots in the denominator, the standard decomposition formula changes. For a term like 1/(s+a)^2, you need both A/(s+a) and B/(s+a)^2. Students keep trying to force distinct-root methods onto repeated-root cases and end up with wrong answers that look almost right. Work through Chapter 3 slowly. The examples there are the key to the whole book. Convolution appears in Chapter 6 and it is genuinely useful, not just a theoretical curiosity. If your forcing function is piecewise or defined as an integral itself, the convolution theorem lets you bypass the mess. I used this specifically when modeling a damped oscillator with a discontinuous driving force that I could not write as a single closed-form expression. Instead of wrestling with Heaviside step functions and getting confused about which interval each term applied to, I wrote the forcing as a convolution integral, transformed it, solved algebraically, and inverted. Cut the problem from about 40 minutes of hand calculation down to roughly 12.
One thing the book does not emphasize enough: the region of convergence. You can get away with ignoring it for standard ODE problems with exponential-order functions, but if you are working with anything that grows faster than exponential or involves distributions, the inverse transform may not exist in the classical sense. McLachlan brushes past this. It cost me about three hours once when I was trying to invert a transform for a function that did not actually have a Laplace transform in the ordinary sense. Check the growth condition before you start inverting. It saves time. Another counter-intuitive point: Laplace transforms are not always the fastest method for solving ODEs, even though textbooks present them as universally applicable. For a second-order linear ODE with constant coefficients and simple initial conditions, the characteristic equation method is usually faster and less error-prone. Laplace shines when you have discontinuous or impulsive forcing, transfer functions, or system-level analysis where you care about poles and zeros. Don't reach for it automatically just because the problem says to. Use whatever gets you to the answer cleanly. The PDE section starting around Chapter 7 is where the book shows its real value. Solving the heat equation and wave equation with boundary conditions becomes mechanical once you see how the transform converts spatial derivatives into algebraic terms. I used this approach for a steady-state temperature distribution problem in a rectangular plate with non-homogeneous boundary conditions. Standard separation of variables would have required a Fourier series expansion that I could not easily sum. Laplace in the spatial variable turned it into a straightforward boundary value problem in the transform domain.
Get the Full Details
If you are looking to get a copy, the Dover edition is the one to get. It is cheap and the printing is readable. The original Oxford University Press editions from the 1940s and 50s are fine too but are harder to find and cost significantly more. There is also a 1964 second edition that adds a chapter on operational calculus techniques. The first edition covers everything you need for a standard undergraduate course. I downloaded a scanned PDF from a university repository a while back and it was sufficient for reference. Legal availability varies by jurisdiction, so check your local options. The Dover print copy runs about twelve dollars and the pages are about 200, which means it is portable without being padded with filler. The main limitation of this book is that it is old. It does not cover modern computational approaches to inversion, numerical Laplace transform methods, or applications to control theory in the way newer texts do. If you need those, pair it with a more contemporary source. But for learning the classical theory and applying it to differential equations by hand, it remains one of the clearest resources available. I still keep a physical copy on my desk. I refer back to the partial fraction tables and the convolution examples more often than I expected to.