So You Need To Navigate The Biggest Wealth Shift Ever
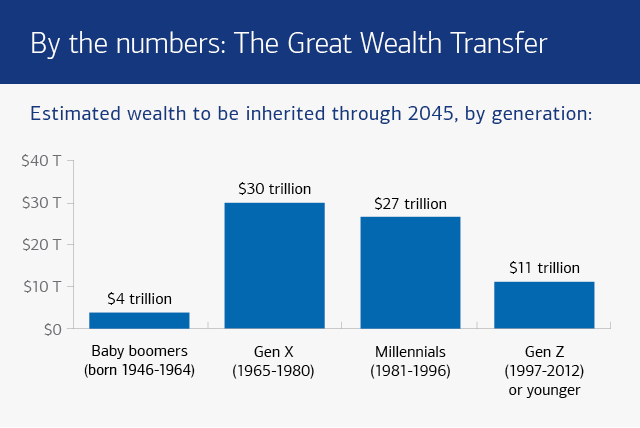
The generational wealth transfer isn't something that happens once. It's an ongoing process, and if you're sitting on either side of it, you need to understand what's actually moving and how the mechanics work. We're talking roughly $84 trillion in the US alone passing from Baby Boomers to younger generations between now and 2045, according to Cerulli Associates. That's not a projection anymore. That's happening right now, piece by piece. When people talk about the Largest Transfer Of Wealth In History, they usually mean the intergenerational flow from aging Boomers and their parents through Gen X, Millennials, and into Gen Z. But it's more complicated than just writing a check from a will. Most of this movement happens through a combination of lifetime gifts, inherited assets, rollover IRAs, 529 plans, and sometimes the sale of family businesses or real estate that was held for decades. The mechanics are deceptively simple on paper. Someone dies or decides to give, and assets move. In practice, it involves estate tax filings, trust administration, beneficiary designations that may or may not have been updated since 1998, and enough paperwork to fill a small office. I spent about three weeks in 2022 working on a transfer where the deceased had opened two IRA accounts in 2004 and never told any of their three kids which was which. The paperwork alone took longer than the actual asset distribution.
How The Transfer Actually Works
Here's the thing most people miss. The majority of this wealth isn't being transferred through probate. It's flowing through beneficiary designations, living trusts, and joint ownership structures that bypass the will entirely. That means the people who actually benefit are the ones whose accounts were properly designated, not necessarily the ones named in the will. I've seen it happen at least a dozen times. A father puts his daughter as beneficiary on his 401k in 2015. He remarries in 2020 and updates his will to leave everything to his new spouse. The 401k goes to the daughter because beneficiary designations override wills. The spouse gets nothing from that account despite what the will says. Another structural detail nobody talks about enough. The step-up in basis rule. When someone inherits appreciated assets, the cost basis gets reset to the fair market value at the date of death. That means the massive capital gains that accumulated over 40 years of holding disappear for tax purposes. If you inherited stocks that were worth $10,000 when your parent bought them 30 years ago and they're now worth $500,000, you don't owe capital gains tax on that $490,000 difference just by holding onto them. Sell them the next day and you only pay taxes on any gain above $500,000. This single rule is responsible for a huge chunk of why this transfer feels so much larger than it actually is in after-tax terms.
The Real Problems People Encounter
The biggest bottleneck in these transfers is usually not the money. It's the disagreement about timing and expectations. Boomers generally want to hold onto assets as long as possible. Younger generations are pressing for access, especially with housing prices and student debt making it difficult to build wealth from scratch. The gap between when wealth is transferred and when younger people feel they need it is one of the main sources of family tension I see in practice. Then there's the SBA transfer problem. Family business succession is where transfers go to die. I worked with a client in 2023 whose father owned a mid-sized manufacturing company worth roughly $12 million. The son wanted to take over but the father refused to transfer ownership until death, which meant the son had no equity stake to leverage against a loan to buy in. The father insisted on keeping control. Three years later the father had a stroke and couldn't run the business. The son had no legal authority to make decisions. The company was sold for scrap value within 18 months. The entire transfer window closed because nobody sat down and wrote out a concrete succession plan. Liquidity is another hidden killer. A lot of Boomer wealth is tied up in home equity and illiquid investments. The kid inherits a house in suburban Ohio worth $600,000 and $200,000 in taxable brokerage accounts. They also inherit $1.2 million in home equity and a vacation property. The estate has to pay estate taxes, funeral costs, and outstanding debts. There isn't enough cash to cover it all without selling assets. The house gets sold at the worst possible market moment because the executor needed liquidity. This happens more often than you'd think.
Get the Full Details

What Actually Moves The Needle
If you're receiving wealth, the fastest way to accelerate your position is to understand the tax-advantaged vehicles available. The annual gift tax exclusion is $18,000 per recipient per year as of 2024. That's $36,000 if you're married and splitting gifts. A family of four can receive $144,000 per year tax-free from each set of parents. That's $288,000 annually that never touches gift tax. Most families I talk to aren't using anything close to this. They're letting wealth sit until death when it gets compressed into a single transfer event that may face estate tax depending on the total size. If you're transferring wealth, the single most effective tool is the irrevocable life insurance trust. It removes the death benefit from your taxable estate while still providing liquidity to heirs who might otherwise need to sell assets to cover estate taxes. I had a client in 2024 whose estate was $14.5 million. Without any planning, his heirs would have owed roughly $3.2 million in federal estate tax. With an ILIT structured into the plan, that dropped to about $1.8 million. That's a real difference that affected whether the family business stayed intact. Gragant IRA rollovers are the new thing everyone should know about. The SECURE 2.0 Act changed required minimum distribution rules for non-spouse beneficiaries. If you inherit a traditional IRA, you generally have to withdraw everything within 10 years. That means a $1 million inherited IRA could trigger enormous taxable income if you're not strategic. Converting portions to a Roth IRA before death, or having heirs do a backdoor Roth strategy after inheritance, can dramatically reduce the tax drag. I recommend running the numbers with a tax professional before any inherited IRA touches your hands.
The Ugly Truths Nobody Publishes
This system is not designed to work fairly. It's designed to preserve existing wealth within existing wealth-holding families. People who already have assets to transfer can use trusts, LLCs, and other structures that cost money to set up but save money on taxes. People who don't have anything to transfer get nothing. The entire structure amplifies inequality because it rewards those who already have wealth with tax advantages that those without wealth simply cannot access. The state-level tax situation is also wildly inconsistent. Some states have no estate tax and no inheritance tax. Others have both. Some have passed-through exemption thresholds that are far below the federal level. If you're transferring assets across state lines, which most families are, you need to understand which jurisdiction claims what. I've seen estates lose six figures to a state inheritance tax that the executor didn't even know existed because the deceased had changed states twice in ten years. And the timing risk is real. The federal estate tax exemption is scheduled to sunsetting after 2025. It's currently around $13.61 million per person but could drop back to roughly $7 million per person if Congress doesn't extend it. This creates a weird incentive where some people are rushing transfers now, and others are waiting to see what happens. Neither approach is clearly better. It depends entirely on your total estate size and your state's tax situation.
The one piece of advice that actually matters: document everything. Account numbers, passwords, beneficiary designations, trust documents, and the location of physical assets. I've seen transfers stalled for months because the executor couldn't find the PDF of the trust that was supposed to direct everything. Your parents probably haven't organized this. If you're on the receiving end, start asking questions now. If you're doing the transferring, get it in writing while you still can.