How to Actually Use the Larry Burkett Budget Worksheet Without Losing Your Mind
The Larry Burkett Budget Worksheet is a zero-based budgeting system that assigns every dollar of income to a specific expense category before the month begins. If you have money left over after filling in all your categories, it goes to debt payoff or savings. That is the basic idea. The worksheet itself is a printed (or printable) sheet that breaks your expenses into fixed, variable, and savings categories, with columns for budgeted amount, actual spending, and variance. I have used this system in various forms for about fifteen years across different household income levels. The first time I encountered it, I thought it was just another rigid budget template. It is not. The structure forces you to make decisions about spending before you spend, which is the whole point. Here is how it works in practice.
Where to Get the Larry Burkett Budget Worksheet
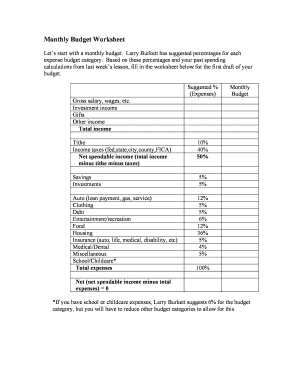
You can download the original worksheet from dave ramsey's website since he acquired Burkett's ministry and legacy materials after Burkett's passing. The PDF is free. There are also several third-party adaptations floating around Google Sheets and Excel. I stick with the original Dave Ramsey version because it matches the category structure Burkett originally designed. The downloadable file has spaces for your monthly income at the top, then a grid that runs down the page with categories already pre-printed. The categories typically include housing, utilities, food, transportation, insurance, medical, clothing, personal spending, entertainment, savings, debt payments, and gifts. Each row has three columns: what you planned to spend, what you actually spent, and the difference. You fill this out once per month, ideally at the start of the month for the budgeted column, and then again at the end to record actuals. Here is where most people run into trouble. The worksheet assumes your income is stable and predictable. When I worked a commission-based sales job, my income varied between four and seven thousand dollars per month. Filling in the top line became a guess, and the whole system wobbled because I was either over-budgeting in bad months or scrambling to redistribute mid-month in good months. My workaround was simple: I budgeted off my lowest monthly income. Whatever came in above that minimum went straight to a surplus bucket that I labeled "extra month buffer." It kept the worksheet honest even in volatile income months. You do not need to change the form. You just need to anchor it to your worst month instead of your average.
Another thing people miss about this system is that the variance column is not just a mathematical exercise. Writing down that you spent two hundred and forty dollars on groceries when you budgeted two hundred is a behavioral correction, not accounting homework. The discomfort of seeing that red number is the mechanism that changes spending habits. I learned this the hard way during a three-month stretch where I kept misjudging my dining-out category by fifty to eighty dollars each time. The worksheet did not tell me I had a problem. The variance column was screaming at me. Once I started looking at that column each time I filled in the actuals, my restaurant spending dropped by nearly half the following month without any conscious effort. There are some real limitations you should know about. The original worksheet does not account for irregular annual expenses well. You can add them manually, but the single-page format gets cramped when you try to list every subscription, holiday gift, and car maintenance expense across twelve separate rows. I ended up creating a secondary sheet that tracked my annual expenses divided by twelve and plugging those monthly averages into the relevant categories on the main worksheet. It added about ten minutes to the process but kept everything accurate. Another limitation is that the system works best when you use cash or debit for variable categories. If you pay groceries and gas with a credit card, you are one statement cycle behind, which means your "actual" column is always lagging. This is a real problem during month-to-month tracking. I switched to using a separate debit card for discretionary spending only, and paid all fixed bills through checking. That aligned my actual spending with the calendar month and eliminated the lag issue entirely. It took about a week to reorganize my accounts but it has been seamless since.
Get the Full Details

The worksheet also does not help much with couple budgets where spending styles diverge significantly. One person treats the budget as a constraint and the other treats it as a suggestion. The form itself is neutral on this, but the psychological gap shows up in the variance column as resentment rather than data. If you are using this with a partner, you need to agree on the rules of the game before you fill out a single row. I have seen marriages survive worse financial stress than a poorly agreed-upon budget system. For anyone who finds the printout cumbersome, a spreadsheet adaptation works fine as long as you preserve the three-column structure and the category list. I have tried converting it to Google Sheets multiple times and always come back to the paper version. There is something about writing the numbers by hand that makes you pay attention. Typing them into a cell feels too frictionless, and that friction is the whole point.