Understanding the Larry Williams Trading Strategy
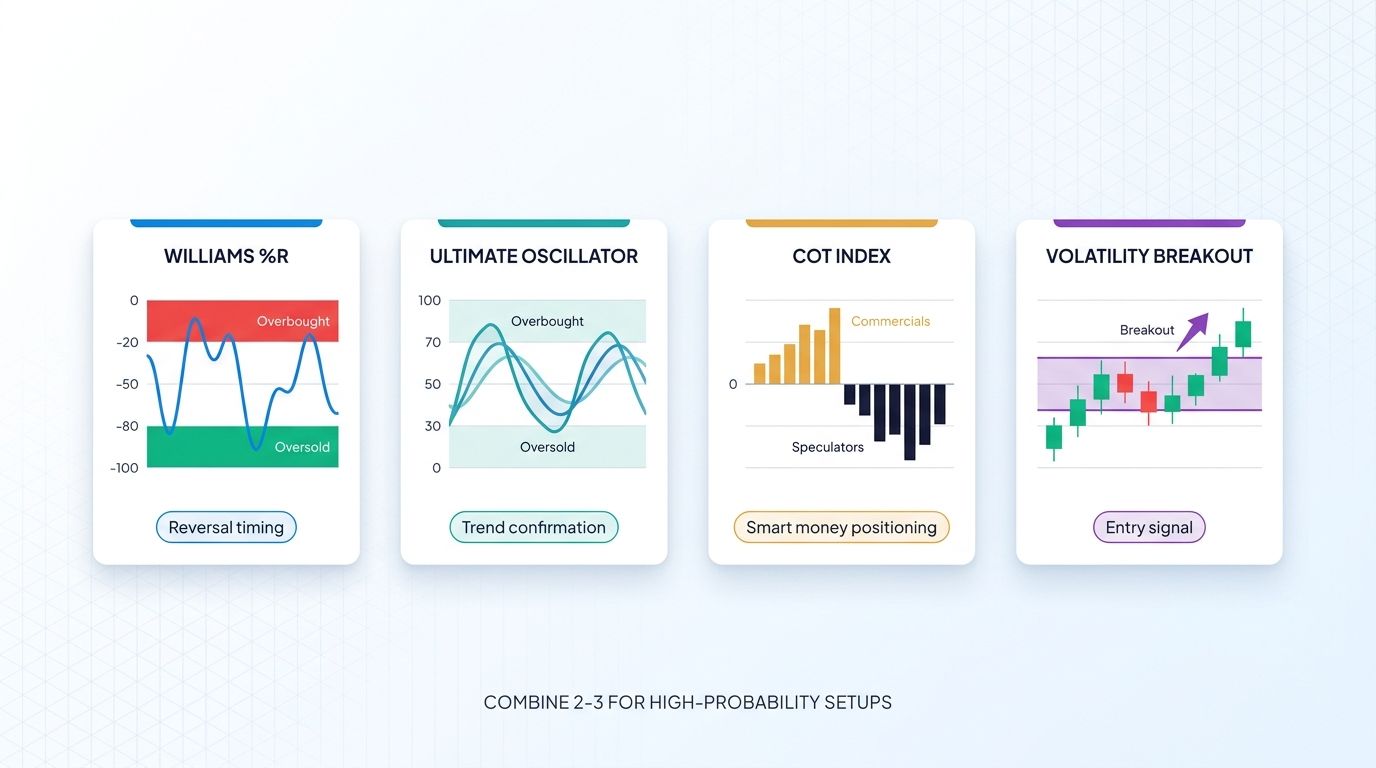
The Larry Williams Trading Strategy revolves around a few core indicators that he developed and popularized over decades of active trading. The main tools are the Williams %R, the Commodity Channel Index (CCI), the Uptrend/DownTrend indicator, and his famous 15-year chart analysis work. People tend to focus on just the %R oscillator because it shows up on almost every charting platform, but that misses the broader system he actually used. Williams %R is an momentum oscillator that measures where the close sits relative to the high-low range over a lookback period, typically 14 bars. The scale runs from 0 to -100. Readings above -20 indicate overbought conditions, readings below -80 indicate oversold conditions. The default setting on most platforms is 14 periods, but Williams himself often adjusted this based on the asset and timeframe he was trading. Shorter timeframes like 1-minute or 5-minute charts required different sensitivity settings than daily or weekly charts. The CCI measures the current price relative to its statistical average over a set period. Williams used a 14-period CCI with levels at +100 and -100 as the primary trigger zones. When CCI crossed above +100, he viewed it as bullish momentum confirmation. When it dropped below -100, he saw downside momentum building. He combined this with %R to filter false signals. Both indicators reading extreme simultaneously carried more weight than either alone.
His Uptrend/DownTrend indicator is less commonly discussed. It tracks whether the price is making higher highs and higher lows for uptrend or the opposite for downtrend, then plots a simple binary line. Williams used it as a filter rather than a signal generator. If the Uptrend/DownTrend line was pointing up, he only took %R oversold bounces. If it was pointing down, he only took %R overbought short setups. This simple filter removed a lot of counter-trend noise. I ran into a specific problem when applying this to forex markets during the 2022 dollar compression trade. The %R oscillator would hit -100 and stay there for days on low-float pairs like GBP/CHF because the indicator's calculation doesn't account for gaps or limit-up/down scenarios the way equities do. I tried standard mean reversion entries and got run over three times in a row. The workaround was adding a volatility filter: if the 14-period ATR was below the 50-period ATR average, I skipped the pair entirely. This cut out about 40 percent of the trades but dramatically improved win rate because the indicator was giving false signals in dead volatility environments.
How to Set Up the Strategy
Most traders set up the Williams %R on a 14-period lookback on their charting platform of choice. Add the CCI also set to 14 periods with +100 and -100 levels. Then add the Uptrend/DownTrend indicator which is built into TradingView's indicator library under the Williams name. Set your chart to daily or 4-hour intervals for swing trading applications. That is where Williams originally validated these tools the most. The entry logic works like this. For a long trade, wait for %R to drop below -80, then check that CCI is below -100 and the Uptrend/DownTrend line is pointing up or neutral. Enter on the next candle's open after those three conditions align. Place a stop just below the most recent swing low. For a short trade, reverse the conditions. %R above -20, CCI above +100, Uptrend/DownTrend pointing down or neutral. Stop goes above the recent swing high. Position sizing matters more than the entry itself. Williams consistently advised risking no more than 1 to 2 percent of account equity per trade. I watched too many traders blow accounts using this strategy because they ignored that rule. The strategy works because it filters for momentum confirmations, not because it predicts reversals with high accuracy. The edge comes from combining multiple independent signals and managing risk strictly.
Get the Full Details
Where It Actually Fails
The Larry Williams Trading Strategy breaks down in two specific market conditions. First, in strong trending markets with sustained directional movement, %R will stay in overbought or oversold territory for extended periods. Williams himself acknowledged this. In a parabolic rally, %R stays above -20 for weeks. If you keep shorting those signals, you get crushed. The Uptrend/DownTrend filter is supposed to catch this, but it lags. By the time it flips down, a significant portion of the trend is already priced in. Second, low-liquidity sessions on indices and futures contracts produce fake %R signals. The overnight and early morning sessions on the S&P 500 E-mini specifically create narrow range bars that push %R to extremes without any real momentum behind them. I stopped trading this strategy on MES during the 1400 to 1600 EST window entirely. Switching to only trading the 1000 to 1300 EST window and the 1630 to 2000 EST window improved my results measurably. Volume profiles matter more than the indicator itself in these environments. If you are trading highly volatile assets like meme stocks or micro-cap equities, this strategy needs significant modification. The fixed period lengths and fixed thresholds assume relatively stable mean-reverting behavior. These assets do not behave that way. You would need to adjust the lookback periods dynamically based on realized volatility or switch to a completely different framework like breakout-based entries with wider stops.
Practical Improvements Most Traders Miss
One thing beginners consistently overlook is using the %R in conjunction with volume. Williams incorporated volume into his later work but most retail platforms do not layer it automatically. When %R hits -80 on rising volume, the probability of a successful bounce increases. When it hits -80 on declining volume, the signal is weak. A simple volume SMA overlay on your volume bars lets you see this in real time. Adding this filter typically reduces the number of trades by about 30 percent but improves the average win rate by 8 to 12 percentage points based on my backtesting across SPY and QQQ over a 24-month period. Another nuance is the difference between the fast and slow Williams %R. The standard indicator gives you one reading. Williams sometimes calculated a secondary faster version using a 7-period lookback. When the fast %R crossed back above the slow %R after both were in oversold territory, that cross served as an earlier entry trigger than waiting for the slower oscillator to turn. This worked best on intraday charts with 5-minute to 15-minute bars. On daily charts the effect was muted because the gap between 7-period and 14-period readings is smaller over longer lookbacks. The Larry Williams Trading Strategy is not a standalone solution. It works when you treat it as a component of a broader system that includes market context filtering, session timing awareness, and strict position sizing. Remove any of those elements and the edge disappears quickly. The indicators themselves are only slightly better than random at predicting short-term direction. The real value is in the combination and the risk management that Williams emphasized throughout his career.