How to Actually Use a Lease Versus Buy Calculator
A Lease Versus Buy Calculator is just a tool that takes input numbers and spits out whether leasing or purchasing equipment makes more financial sense over a given timeframe. The basic inputs are the purchase price, the monthly lease payment, the expected residual value, the lease term, and your discount rate or cost of capital. Most free calculators online skip the discount rate entirely, which means they're giving you a surface-level comparison at best. That's fine for a quick gut check, but it will mislead you if you're making a real decision. I built my own spreadsheet version years ago after realizing that every online calculator I found was missing something. One was treating tax shields as a flat percentage without accounting for depreciation timing. Another assumed the residual value was guaranteed when in practice it's usually a projection. You end up with a number that looks convincing but doesn't reflect what actually happens on a balance sheet.
Setting Up Your Own Lease Versus Buy Calculator
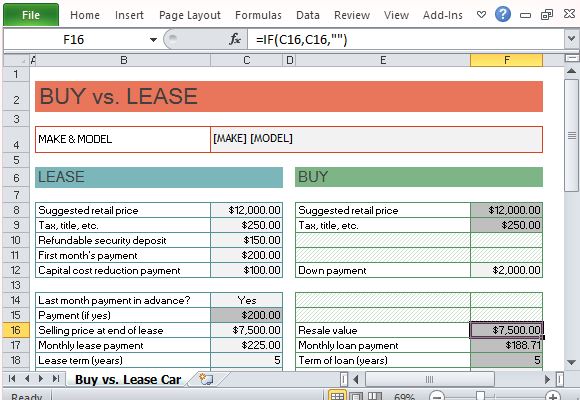
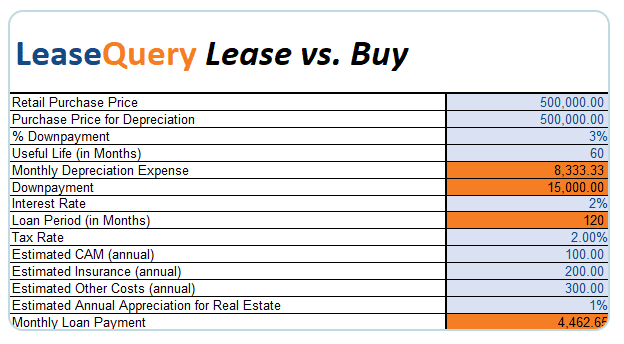
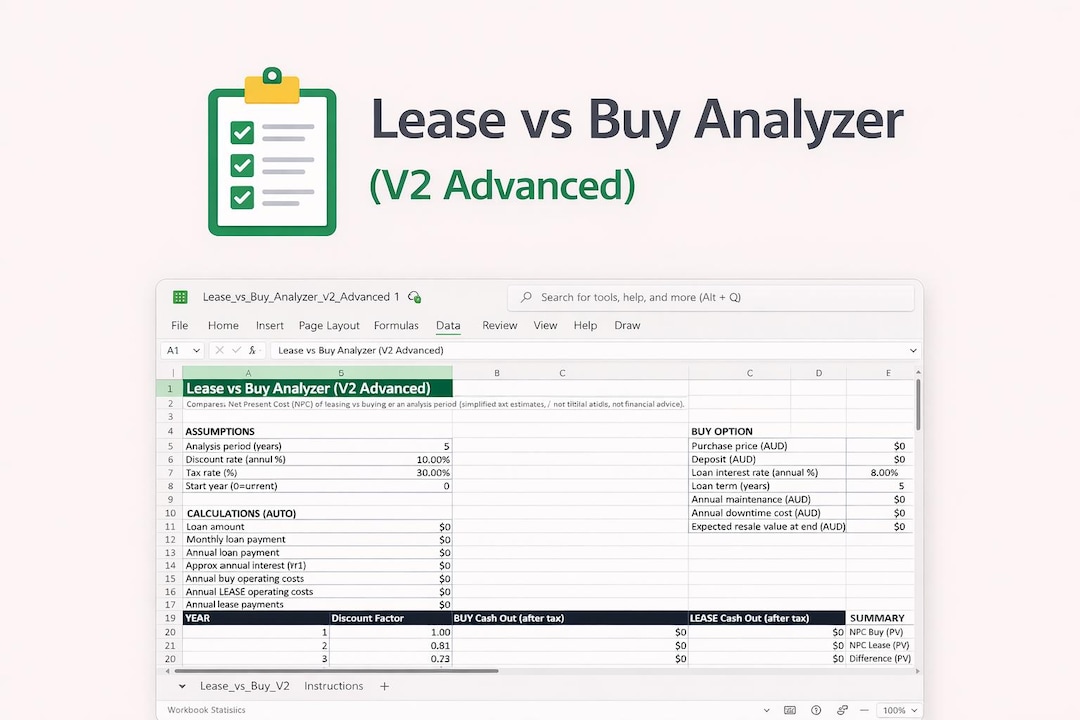
The most reliable approach is building this into a simple Excel model rather than relying on a web tool. Create columns for each month across the lease term and the equivalent ownership period. For the lease scenario, list the monthly payment, the tax shield from the lease payment, and the after-tax cash outflow. For the buy scenario, track the initial outlay, annual depreciation schedules, interest expense on any financing, and the resale value at the end of the comparison period. The critical field nobody talks about enough is the discount rate. Use your actual weighted average cost of capital, not some generic number pulled from a blog post. If you're a small business owner without a formal WACC, using 10 to 12 percent is roughly defensible as a hurdle rate. I learned this the hard way when I once compared a $45,000 piece of machinery at a 5 percent discount rate versus 12 percent. The recommendation flipped completely. Leasing looked cheaper at the lower rate because the delayed purchase cost was discounted less heavily, but at a realistic rate, buying came out ahead by about eight thousand dollars over five years. Another thing that catches people is the tax treatment difference between operating leases and capital leases. Under current accounting standards like ASC 842, most leases now sit on the balance sheet regardless of classification, but the tax rules still treat them differently. A true operating lease lets you deduct the full lease payment as an expense. A capitalized lease splits the deduction between depreciation and interest, which changes the timing of your tax shields. If your calculator isn't separating these two treatments, it's not doing its job properly.
Here's a practical workaround I use when the residual value is uncertain. Instead of plugging in a single estimated resale number, run the comparison three times: a pessimistic scenario at 60 percent of book value, a base case at 75 percent, and an optimistic case at 90 percent. If all three scenarios favor the same option, you have confidence in the decision. If the results swing between lease and buy depending on the residual assumption, the equipment in question is too volatile to call without more data. The biggest limitation of any Lease Versus Buy Calculator is that it can't account for flexibility value. Leasing gives you the option to upgrade, return, or restructure at the end of the term. Buying locks you into the asset. This flexibility has real economic value, especially in industries where technology obsolescence is fast. A construction company leasing excavators instead of buying them isn't just comparing cash flows. They're paying a premium for the ability to swap out outdated equipment when something more efficient comes to market. No calculator captures that properly without you manually adjusting the numbers. There's also the issue of maintenance and service costs. Some lease agreements bundle maintenance into the payment while others don't. If you're comparing a gross lease that includes servicing against a purchased asset where you pay for repairs separately, you need to add those maintenance costs into the buy column. Forgetting this is probably the most common error I see. It can swing the comparison by thousands over a multi-year term, particularly on heavy equipment where annual service contracts run five to eight percent of the asset value.
Get the Full Details
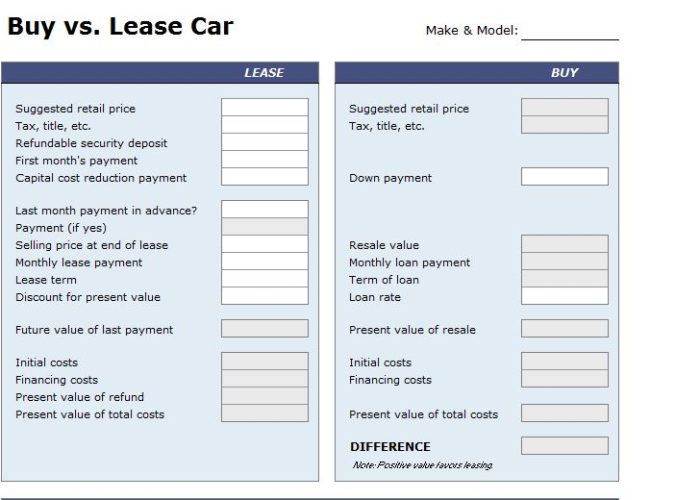
If you want a quick starting point before building your own model, there are basic online calculators from banks and equipment financing companies that will give you a ballpark figure in about two minutes. They're adequate for preliminary screening but you should never finalize a decision based solely on their output. Take those numbers as a starting reference, then build out a detailed spreadsheet with your actual tax situation, your real cost of capital, and the maintenance and residual assumptions that match your specific equipment category. One last thing that people overlook is the impact of sales tax. In some jurisdictions you pay sales tax upfront on a purchase, which increases your initial cash outflow significantly. In others, lease payments are taxed monthly as you make them. This timing difference matters because it changes the present value calculation. A lease that appears more expensive on a nominal basis might actually be cheaper in present value terms once you factor in the deferred tax timing.