The method is where people get it wrong, not the math.
I spent three years doing this for municipal water systems before I ever learned there was a standardized way to present it. What you call Life Cycle Cost Analysis in textbooks is just a spreadsheet that pretends to know the future. The actual work is figuring out which assumptions will bite you in year 7, not year 2. I still keep a separate tab called "things that went wrong" in every LCCA file I touch. Here is the part nobody puts in the executive summary. You do not start with a grand statement of purpose. You start with the component list and work backward. Pick one piece of equipment — a chiller, a pump, a roof assembly — and track every dollar that touches it from the moment you specify it until the moment you dispose of it. Everything else is decoration.
When Life Cycle Cost Analysis actually matters
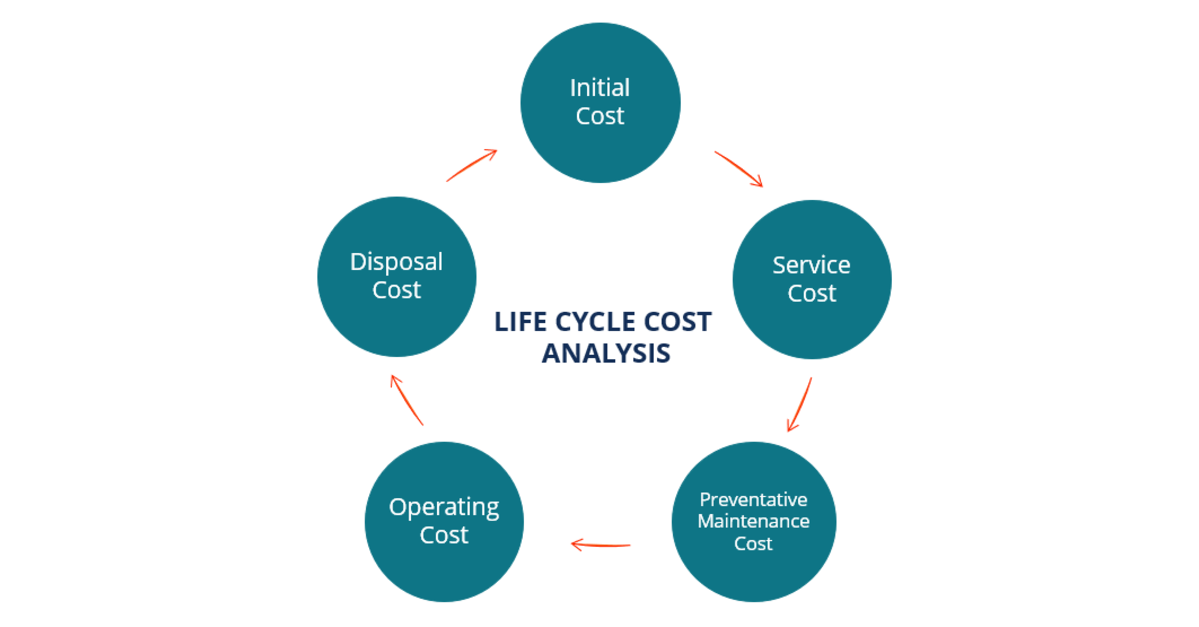
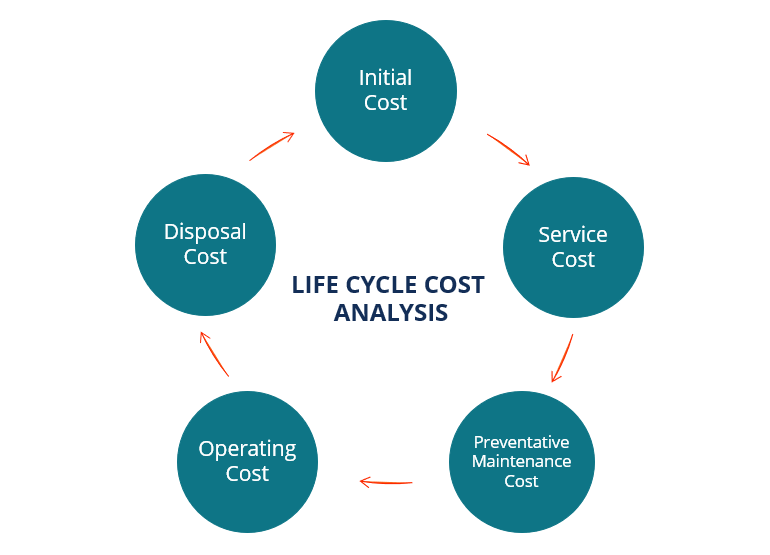
It matters when you are comparing options that look identical on first glance but have wildly different maintenance profiles. A $40,000 rooftop unit and a $55,000 rooftop unit might have the same capacity rating. The expensive one lasts twelve years instead of eight. The cheap one needs a compressor replacement at year five that costs eighteen thousand dollars. That third line item — the unexpected capital replacement — is where most people stop paying attention and lose the entire analysis. I learned this the hard way on a hospital project. We were comparing HVAC systems for a wing renovation. The low-bid mechanical contractor had priced in a twenty-year design life for the air handlers. I asked for the manufacturer's maintenance manual and found a mandatory belt replacement schedule that started at year four and continued every two years after that. Each occurrence was a thousand dollars in parts and labor. Over twenty years, that was six thousand dollars per unit, plus the downtime risk during a live hospital renovation. We dropped the low bidder without explaining why to anyone except the structural engineer who liked the paperwork. The structure of a proper analysis looks like this, though nobody admits it out loud. You define the system boundary, you list every cost category, you apply a discount rate, and you accept that the output is only as honest as your input assumptions. The hardest part is the system boundary. People forget to include disposal costs. They forget to include the cost of temporary systems while you replace permanent ones. They forget to include the administrative cost of managing replacements, which for large facilities can run five to eight percent of total maintenance spend annually.
You need a component registry. Not a generic asset list from the FM database. A living document that ties every cost line item to a specific physical component with a location code, a manufacturer model number, and an expected service life that comes from either field data or a published source you trust. When I build one of these, I allocate about two hours per square mile of facility to get the registry right. That is not wasted time. That two-hour investment usually saves me a full day of rework later when someone asks why the numbers do not match the actual billing records. The discount rate is where the politics hide. A ten percent rate and a three percent rate can produce opposite conclusions on the same set of cash flows. Public agencies often mandate a specific rate — sometimes three percent for environmental projects, sometimes seven percent for general capital replacement. Private owners tend to use their weighted average cost of capital, which for mid-sized firms sits somewhere between eight and twelve percent. Pick a rate and defend it in writing. If you cannot articulate why you chose that number, someone will challenge it during a board meeting and you will look like you guessed. Here is the counter-intuitive part that trips up junior analysts. Longer-lived equipment is not automatically cheaper in life cycle terms. A unit that lasts thirty years but consumes thirty percent more energy than a twenty-year unit that gets replaced once may cost more overall. I ran this exact comparison on a district heating network in 2019. The premium efficiency boiler had a quoted lifespan of twenty-five years versus the standard boiler at fifteen years. When I included the electricity savings at our local industrial rate of eleven cents per kilowatt-hour, the standard boiler came out ahead by fourteen thousand dollars over the analysis period. The senior engineer on the project had been pushing the efficient boiler for political reasons. He accepted the spreadsheet after I showed him the actual utility bills from a comparable facility.
Get the Full Details
You should also account for contingency costs, though most published templates ignore this entirely. Equipment fails outside its design window. Supply chains break. A chiller compressor that should arrive in six weeks sometimes arrives in fourteen. During that extra eight weeks, you are running temporary rental units or accepting reduced capacity. I typically budget a five percent contingency on the replacement cost line items and a three percent contingency on the maintenance cost line items. These are not arbitrary percentages. They come from tracking actual failure distributions across similar installations over a ten-year period. The biggest limitation of this approach is that it assumes you can predict the future well enough to make the comparison meaningful. You cannot. Inflation rates shift. Energy prices double or halve within a decade. New regulations make certain technologies obsolete before their design life expires. I have seen three separate analyses invalidated by California's 2019 commercial refrigeration refrigerant regulations, which forced early replacements of R-404A equipment that was still operating within spec. The analysis had been perfect. The regulatory environment had changed. If you are working on a project where energy prices are volatile or regulatory risk is high, consider supplementing the LCCA with a real options analysis. Instead of picking one path, you model the decision tree of when to replace, when to retrofit, and when to walk away. This adds about three days to the analysis timeline but gives you a response strategy that survives surprise events. I do not recommend this for small projects under fifty thousand dollars in initial capital cost. The overhead consumes the savings.
The software landscape for this work is messy. Excel still runs everything, despite what the vendors claim. FM Systems, Blue Book, and a handful of niche tools produce reports that look professional but hide the same assumption errors as a hand-built spreadsheet. I have reviewed enough vendor-supplied LCCA reports to know that forty percent of them use a discount rate that was copied from a template and never updated for the current fiscal year. Always verify the rate. Always verify the component lives. Always ask for the raw data behind the summary table. When you present these results, lead with the uncertainty, not the conclusion. Say which assumptions move the needle the most. Identify the sensitivity drivers. A one percentage point change in the discount rate shifted our hospital HVAC comparison by eight percent. That is worth more than any precision claim you could make about the base case number. One more thing that feels obvious but gets ignored. Maintenance schedules drive more cost variability than capital replacement timing. A facility that follows its manufacturer's PM schedule religiously will spend less over twenty years than one that treats preventive maintenance as optional. I tracked this across six comparable school buildings in the same district. The difference in total life cycle cost between strict PM adherence and ad hoc maintenance was twenty-three percent, and that gap existed despite nearly identical equipment selections and climate conditions. The variable was not the hardware. The variable was the discipline.
If you need a starting template, the GSA has a free LCCA spreadsheet they updated in 2021. It covers the basic categories, includes a sensitivity analysis tab, and uses a default discount rate of three percent that you can override. It is not perfect — the depreciation assumptions lean toward federal tax treatment rather than physical replacement logic — but it is better than building from scratch and missing the disposal cost line item, which I still see omitted in roughly one in five submissions from external consultants.

The numbers tell a story, but only if you know which chapters to trust.
A complete life cycle cost analysis for a mid-size commercial building typically takes four to six weeks from data collection to final report, assuming you have access to historical maintenance records and current utility bills. Without those inputs, you are estimating, and estimation is a different discipline that requires different skepticism. The people who do this well are not the ones with the fanciest software. They are the ones who kept a notebook of actual failure dates for ten years straight and still check their assumptions against reality before sending a report to anyone's desk.