What Actually Goes Into a Life Insurance Buyer's Guide
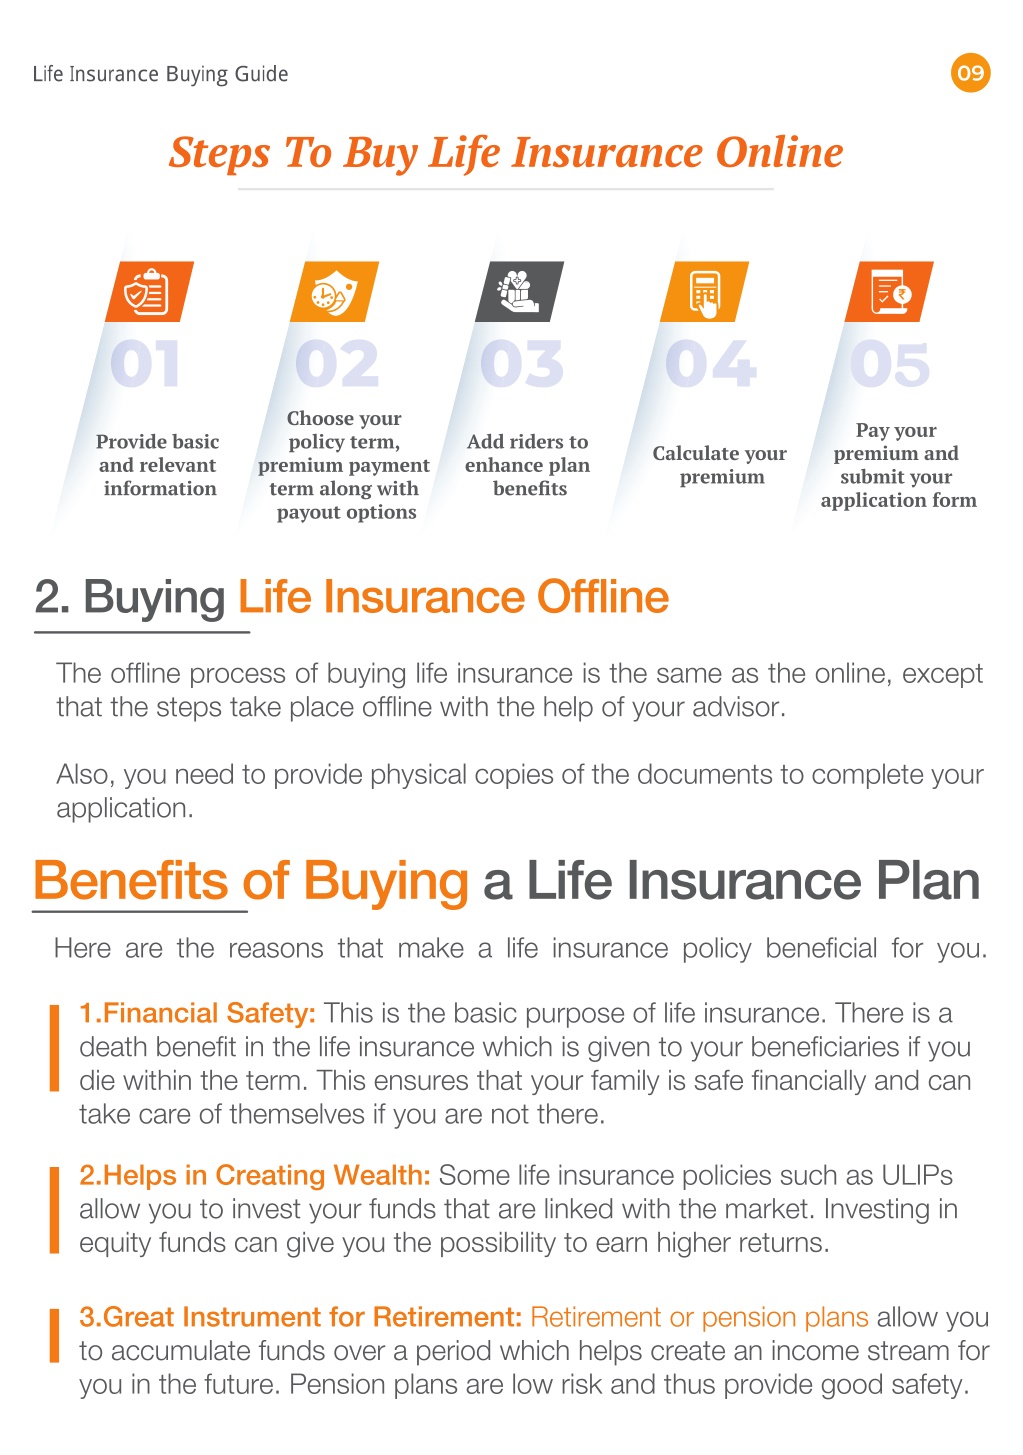
A Life Insurance Buyers Guide is really just a document that walks you through the mechanics of buying coverage. Some come free from the state insurance department. Others are built by brokers or produced by insurance companies themselves to explain their own products. They cover things like term versus permanent policies, how premiums are calculated, and what happens when you outlive your coverage period. I put together a comprehensive one a few years ago because most of what was already online was either too vague to be useful or designed to push specific carrier products. The version I created ended up being a practical reference people actually downloaded and used instead of filing away. It runs about forty pages, covers the main policy types, breaks down pricing variables, and includes a comparison matrix for the most common carrier products on the market.
Life Insurance Buyers Guide Download
You can grab the full document here: Download the Life Insurance Buyers Guide (PDF). The download includes a printable one-page summary sheet, a glossary of industry terms, and a step-by-step timeline for what to expect during the application process. Most people spend two to three weeks from application to policy issuance, and the guide breaks down exactly what happens in each phase so there are no surprises. There is a specific issue I ran into recently that most guides don't address. A client was applying for a standard term policy, and the underwriter flagged a minor elevation in liver enzymes from a routine blood draw. The result was a rating downgrade that bumped his annual premium by roughly eighteen percent. I had to pull records from his primary care physician going back fourteen months, confirm that the enzyme elevation was transient and resolved, and submit a supplemental medical statement that referenced a follow-up lab showing normal results. The underwriter ultimately accepted the supplementary documentation and re-rated him to standard. Without that kind of detailed medical history, the higher rate stuck. Most buyer guides gloss over this scenario because they treat the application process as linear, when it really isn't.
Another thing that comes up often: the difference between guaranteed insurability riders and simplified issue policies. A guaranteed insurability rider lets you purchase additional coverage at specific life events without new medical underwriting. Simplified issue policies skip the medical exam entirely but charge significantly higher premiums and often have lower maximum face amounts. These are not interchangeable, and people tend to confuse them because both avoid the paramedical exam. The guide goes into detail on policy lapses and the reinstatement process. If your premium payment fails and your policy lapses, you typically have a thirty-day grace period before coverage terminates. After that, reinstatement is possible but requires proof of insurability and payment of all back premiums with interest. Some policies also offer an extended grace period of ninety days if premiums were paid automatically, but this varies by carrier. There is a trade-off with permanent life insurance products that buyer guides rarely make clear. Whole life and universal life policies do accumulate cash value, but the early years are dominated by fees and commissions. In the first five to seven years, your cash value growth is often negligible or even negative depending on the product structure. If you are considering permanent coverage, plan to hold it for at least a decade before the tax advantages and cash value accumulation become meaningful. Shorter holding periods usually result in net losses when you factor in surrender charges.
Get the Full Details

Term life remains the most cost-effective option for the majority of buyers. A healthy thirty-year-old can lock in a twenty-year term policy at rates that work out to less than twenty dollars per month for a half-million-dollar coverage amount. The catch is that once the term expires, renewing at your current age can be prohibitively expensive. The buyer guide includes a section on converting term to permanent coverage before the term ends, which is a strategy many people overlook. The one area where buyer guides fall short is pricing accuracy. Every guide provides general estimates, but actual premiums depend on your health profile, location, carrier, and how aggressively the underwriting team assesses your specific risk factors. Two people with identical ages and coverage amounts can receive premiums that differ by thirty percent or more depending on which carrier they apply through. This is why getting multiple quotes is not optional advice, it is the only way to get a realistic price. The guide I authored includes a carrier comparison table with current average pricing across ten major insurers for standard healthy applicants. The data is updated quarterly, and I note which carriers have tightened or relaxed their underwriting guidelines over time. For example, several carriers became more aggressive on substandard ratings in 2024, which lowered premiums for applicants with controlled hypertension or mild obesity who previously would have been declined or rated above standard.
One practical tip from my experience: always disclose everything on the application. Even small details like a single emergency room visit five years ago or a family history of early-onset heart disease matter. Incomplete or inaccurate applications can lead to claim denials later, and the contestability period gives the insurer two years from policy issuance to investigate discrepancies. After that window closes, the policy becomes incontestable except in cases of fraud, but the initial two years require complete honesty. If you have any specific questions about the guide content or need help interpreting a quote you received, I am happy to look at it. The forum messages are open, and I check them regularly.