Why Most People Get Life Insurance Needs Analysis Wrong
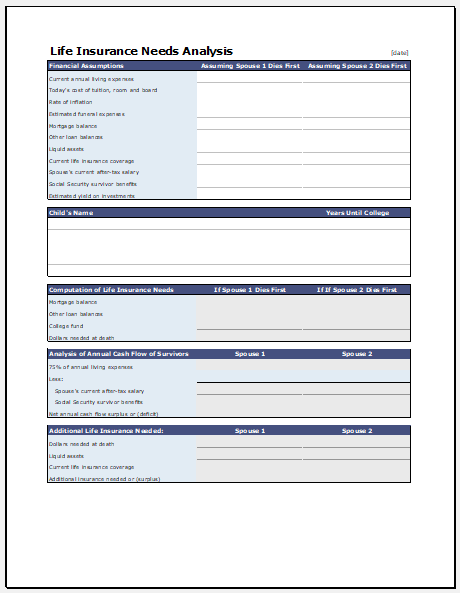
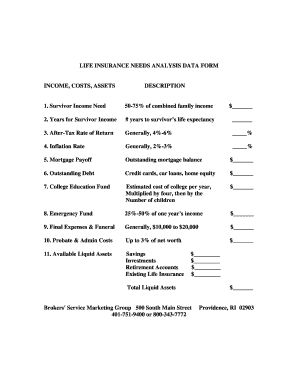
Most people treat this as a math problem. It isn't. A needs analysis gives you a single dollar figure, but that number means nothing if you're filling out a form blind. The process starts with understanding what each household expense actually is and whether it disappears on death, continues unchanged, or changes at all. Income replacement, final expenses, debts, education costs, spousal support, inflation adjustments. Each line item has different logic behind it. Getting them wrong means you either underinsure and leave people short, or overinsure and pay premiums that could be working elsewhere.Life Insurance Needs Analysis Example: How It Actually Works in Practice
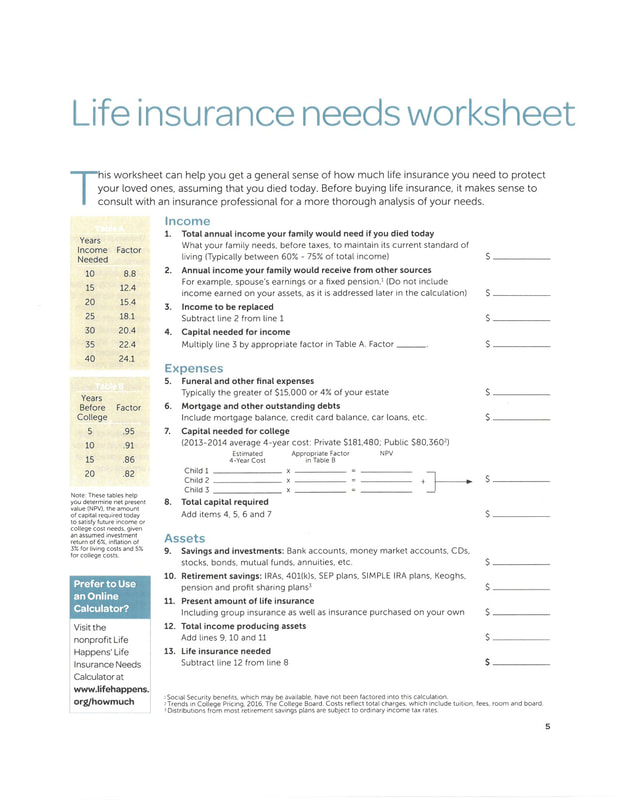
The standard method people encounter online is the DIME approach or the Human Life Value method. Both are useful as starting points. Neither is sufficient on its own. I've sat across from clients who had a spreadsheet showing they needed $2.4 million in coverage, then asked me why the $2.4 million figure didn't match what any carrier would actually bind them for at their age and health class. It didn't match because the spreadsheet assumed a static dollar amount for 30 years and ignored that mortgage balances drop, children become independent, and survivor income needs shift dramatically year to year. Here is what a real needs analysis looks like step by step. First, list all monthly and annual expenses the household would lose if the insured died. Include mortgage, utilities, food, transportation, childcare, education, healthcare, and whatever discretionary spending actually happens. Second, identify which of those expenses stop when the insured dies. A second car payment usually ends. College tuition may stop if a dependent no longer needs support. Third, determine which expenses grow. Healthcare costs generally increase with age. Fourth, calculate the income replacement gap. Take the insured's after-tax income and subtract the surviving household's own earned income. That difference is what needs to be replaced. Fifth, account for existing assets. Savings, retirement accounts, existing life insurance policies, and investment accounts all reduce the need. Sixth, factor in lump-sum expenses. College tuition, wedding costs, or debt payoff requirements that will hit at a specific future date. Now here is where most spreadsheets fail and where I have seen people get burned repeatedly. The standard example tells you to multiply the income gap by the number of years until the youngest child turns 18, then add outstanding debts and final expenses, then subtract assets. That produces a number. But it treats every dollar the same. It does not account for the time value of money, inflation erosion, or the fact that investment returns on the death benefit will generate their own income stream. A proper needs analysis uses a present value calculation. You discount future income replacement needs back to today's dollars using a conservative assumed rate of return. The result is almost always lower than the simple multiplication method produces. It is also more accurate.
I once had a client who ran a needs analysis that told her she needed $1.8 million in coverage. She was 34, married, had two children, a $320,000 mortgage, and made about $85,000 a year. Her husband made $95,000. The analysis ignored the husband's income entirely and treated the mortgage balance as a static obligation. When I redid it with proper discounting and included the spousal income offset, the adjusted need came to roughly $620,000. She had already been quoted premiums for $1.8 million on a 20-year term. We restructured to $650,000 and she saved nearly $90 a month in premiums, which she redirected into a taxable investment account instead. Over 20 years, that difference compounded to something substantial. The point is not that she was wrong for doing the analysis. The point is that the standard online calculators produce inflated numbers that make people buy more insurance than they actually need.
The Two Most Common Mistakes in Needs Analysis
The first mistake is treating the needs analysis as a one-time exercise. It is not. Household finances change. A bonus becomes regular income. A child goes to college. A parent moves in. An inheritance arrives. A business starts generating cash flow. Every major financial event resets the calculation. I recommend running the full analysis every two to three years or after any significant life change. Doing it once and setting it aside is like filing your taxes in January and never looking at them again. The second mistake is ignoring health classification impact. The dollar amount you need and the premium you will actually pay are two separate calculations. A healthy 35-year-old might qualify for Preferred Plus rates. A borderline smoker with elevated blood pressure might only qualify for Standard or even Substandard. The need stays the same, but the cost changes dramatically. This means your actual insurance strategy should account for both the coverage amount and the health class you are likely to receive. Sometimes the better move is to lock in coverage at a younger age while you qualify for preferred rates, even if the exact need hasn't fully crystallized yet. Term policies that renew or convert give you that flexibility.
Get the Full Details
When a Needs Analysis Completely Fails You
There are scenarios where this method produces unreliable results and you should use something else. If you own a business, a needs analysis based on personal expenses misses the entire ownership transition picture. Succession funding, buy-sell agreements, key person insurance, and estate liquidity needs operate on completely different logic than household income replacement. A business owner who runs a standard household needs analysis might find she needs $400,000 in coverage, while the actual business valuation and buyout agreement requires $2.1 million. The gap is catastrophic if you only acted on the household number. Another failure point is high-net-worth individuals where estate tax planning dominates the conversation. A $5 million estate might not need traditional life insurance for income replacement because the assets themselves provide sufficient liquidity. The question becomes whether the estate will owe federal or state death taxes, and whether life insurance is being used to equalize inheritances among heirs or to provide liquidity for tax payments. In those cases, the needs analysis shifts from an income replacement calculation to a tax and estate planning calculation. The methodology is different enough that plugging high-net-worth numbers into a standard calculator produces nonsense. A third scenario where needs analysis breaks down is when the insured has irregular or commission-based income. If your annual earnings fluctuate between $60,000 and $200,000, picking a single income figure for the calculation is arbitrary. Some analysts use the lowest five-year average. Others use the peak. Both approaches have flaws. The realistic workaround is to model multiple income scenarios and stress-test the coverage need against the worst-case income year while assuming the best-case earning capacity still supports the family's baseline expenses. It is more work, but it prevents you from buying coverage based on a single year's income that may not repeat.
A Practical Walkthrough You Can Actually Use
Let me walk through a concrete example using real numbers so you can see how the pieces fit together. Consider a family where the primary earner makes $92,000 annually after taxes. The secondary earner makes $58,000 after taxes. They have a mortgage balance of $285,000. They have $45,000 in combined consumer debt. They have two children aged 6 and 9. They have $120,000 in retirement accounts and $35,000 in a taxable investment account. They currently have $200,000 in employer-provided term life insurance. The primary earner is 38 years old and in good health. Start with the income gap. Combined household income is $150,000. If the primary earner dies, the surviving household income drops to $58,000. The gap is $92,000 per year. But that gap does not last forever. The younger child will finish high school in about nine years. The older child in about six years. College costs for both need to be factored in separately. Let's estimate $100,000 per child in future college tuition, discounted to present value, which comes to roughly $140,000 total at a 4 percent discount rate. Now calculate the present value of the income replacement. The gap of $92,000 per year does not continue for 25 years. It shrinks as expenses drop and children become independent. A reasonable approximation is to model the gap declining over 15 years as the household adjusts. Using a present value of an annuity formula at a 3.5 percent discount rate, 15 years of declining income replacement comes to approximately $980,000 in today's dollars. Add the $285,000 mortgage, $45,000 in consumer debt, $140,000 in college costs, and roughly $25,000 for final expenses and estate settlement costs. Total needs come to about $1,475,000.
Subtract existing assets. $120,000 in retirement accounts, $35,000 in taxable investments, and $200,000 in existing employer coverage equals $355,000 in offsets. The net insurance need is approximately $1,120,000. That is the number that matters. Not the $1.8 million a basic calculator would have produced, not the $400,000 a lazy analyst might suggest. The real number sits somewhere in the middle and requires actual line-by-line work.

What to Do After You Have the Number
Getting the number is the easy part. Implementing it is where things get messy. Term life insurance is the most cost-effective way to cover a calculated need during your highest-responsibility years. A 20 or 30-year term policy will cover you through the period when income replacement matters most. If your need is $1.12 million, buying a $1 million term policy and a $250,000 term policy on a joint basis gives you the coverage without overpaying for whole life or universal life products that carry unnecessary cash value costs for someone whose primary need is temporary income replacement. Permanent life insurance has its place, but it is not the default answer for most people running a needs analysis. If you have maxed out all other tax-advantaged accounts and still have excess cash flow that you want to shelter, permanent insurance can serve as a supplemental vehicle. If you have a special needs dependent who will require lifelong support, permanent insurance provides a guaranteed payout regardless of when you die. If estate tax liquidity is the concern, permanent insurance matches the timing of the tax event better than term insurance. But for the average family with a calculated temporary need, term insurance at the calculated amount is the correct solution most of the time. The hardest part of this process is being honest about your assumptions. The income gap calculation depends on your spouse's ability to maintain their current employment. The college cost estimate depends on whether they plan public or private schools and whether scholarships or employer assistance will reduce the burden. The discount rate you choose changes the present value significantly. A 2 percent discount rate produces a much higher need figure than a 5 percent discount rate. There is no single correct assumption. The goal is to pick reasonable assumptions, document them clearly, and revisit them whenever circumstances change. A needs analysis is not a destination. It is a snapshot of your financial situation at a specific point in time, and the value comes from how often you update it and how carefully you interrogate your own assumptions.