Why most people skip this step and regret it later
I have sat across from clients who had term policies for 15 years without ever running a proper needs analysis. They knew their face amount—something they picked up at a car dealership when financing a mortgage. When we finally sat down and actually worked through the numbers, the gap between what they thought they needed and what their family would require was massive. That disconnect happens constantly. It's not because people don't care. It's because the tools available are either too simplistic or written in language that makes you feel like you need a certification to fill them out. A Life Insurance Needs Analysis Worksheet exists to bridge that gap. It is not a magic bullet, but it is about as close as you are going to get to a structured conversation that forces you to confront actual numbers instead of guesses.
How to actually use a Life Insurance Needs Analysis Worksheet
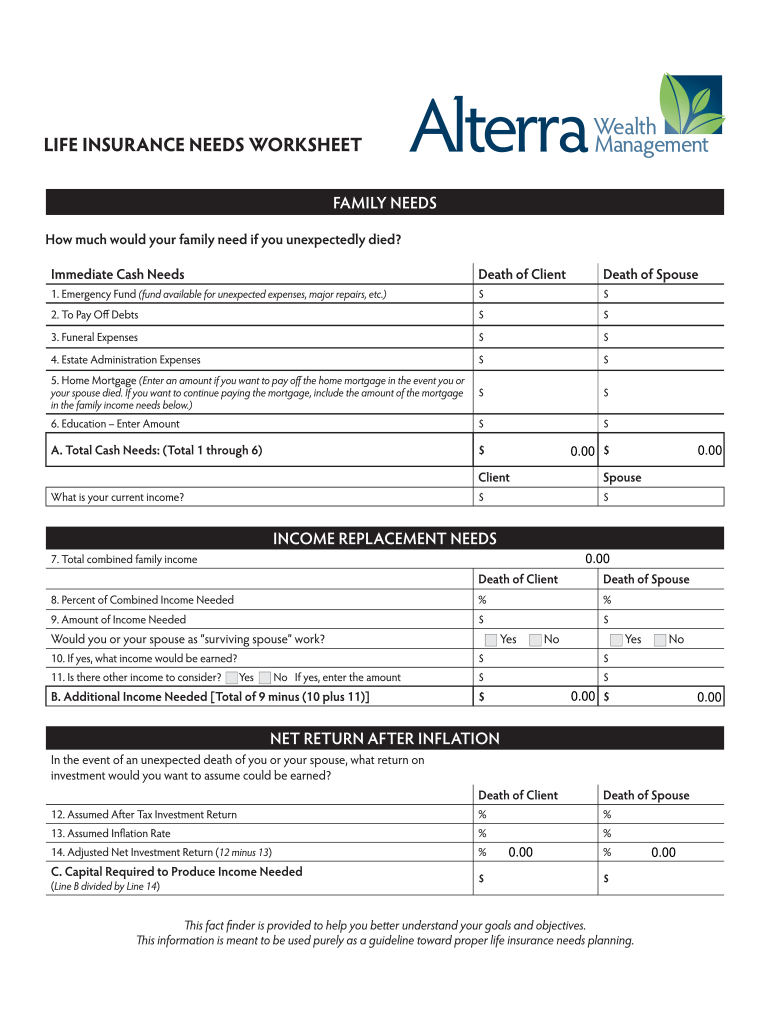
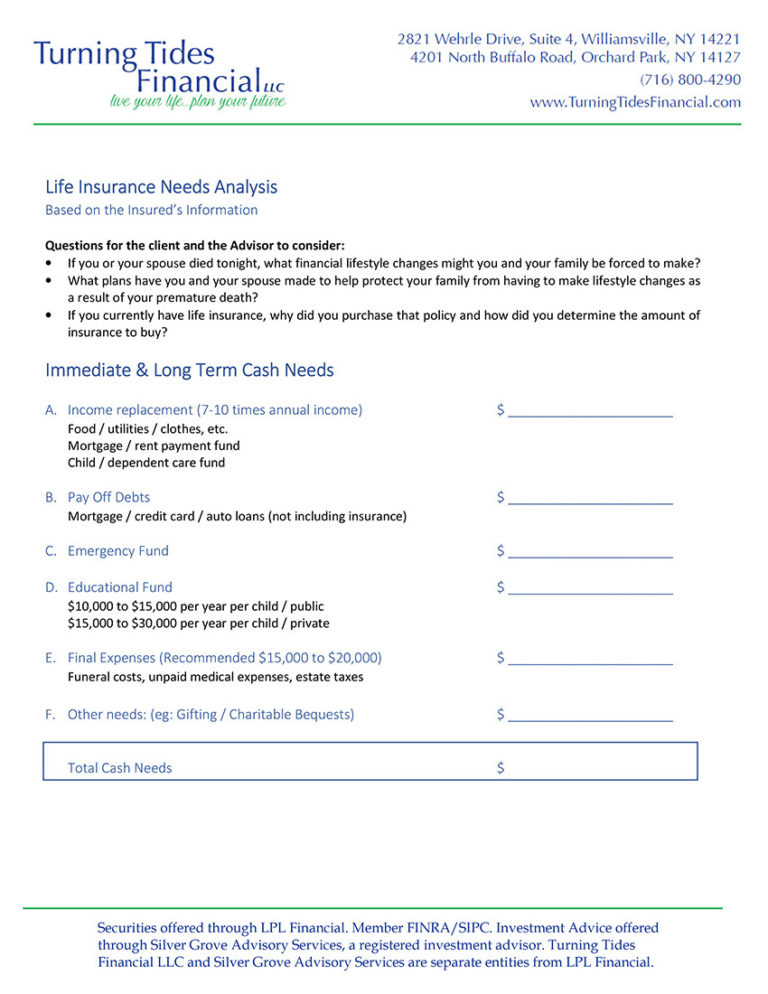
The worksheet breaks down into four core buckets. You start with immediate expenses, then move to income replacement, then outstanding obligations, then future obligations. After you add those numbers up, you subtract existing assets and coverage. The remainder is your gap. That gap is your target face amount, adjusted for inflation and your family's specific timeline. Immediate expenses are the things that show up within the first six to twelve months after death. Funeral costs average around nine thousand dollars these days, but that varies by region and preference. Outstanding medical bills that survive the policyholder are also included here, though many people do not think to factor those in. Credit card debt does not die with the person, which surprises a lot of clients. If you have a co-signed card, the surviving spouse or cosigner inherits the full balance. Settle that on paper before moving forward. Income replacement is where most worksheets go wrong because people default to a simple salary multiplier. Multiply your annual income by however many years the dependents will need support and call it done. That ignores tax implications, inflation, and the fact that income does not stay flat. Use a discounted cash flow approach instead. Take the annual income figure, adjust for an estimated inflation rate of two to three percent, then discount it back to present value using a conservative investment return assumption of four to five percent. It takes slightly longer but produces a number you can actually defend if something goes sideways.
Outstanding obligations are debts that survive you. Mortgages, auto loans, student loans, personal loans. Pull the current payoff balances, not the original amounts. I had a client last year who thought his student loan was paid off because he stopped getting statements a few years back. It was in default. The balance had ballooned to nearly forty thousand dollars. Without pulling the actual payoff quote from the servicer, the worksheet would have shown zero debt. That is the kind of detail that silently ruins a needs analysis. Future obligations include education costs and spousal support. If you have children, run the current cost of a public university against expected financial aid and any existing 529 balances. Do not assume your kids will go to school without help. Also factor in whether a surviving spouse would need income continuity to maintain the family home. That is not always covered in standard worksheets. Assets and existing coverage are your offset column. This includes liquid savings, retirement accounts, existing life insurance policies, and any survivor benefits from employers or government programs. Do not double-count. A common mistake is listing a 401(k) as an asset and also including it in income replacement calculations. Pick one method and be consistent.
Get the Full Details
The edge case nobody warns you about
There is a specific scenario that derails more than a few worksheets. I ran into it with a client whose wife was a stay-at-home parent with no formal employment history. Standard income replacement models returned zero for her contribution, which would have drastically understated the family's needs. Her labor had economic value—childcare, household management, transportation, meal preparation. I had her run local market rates for those services and added an annual figure to the income replacement section. It changed the target coverage by nearly two hundred thousand dollars. The worksheet does not account for this unless you force it. Another edge case involves business owners with key-person provisions. If the business has a buy-sell agreement funded by life insurance, that coverage exists separately and should not be folded into the family needs analysis. I see people count the same dollar twice when they mix business and personal worksheets into one document. Keep them apart and reconcile only at the total exposure level.
Common pitfalls that produce bad numbers
Using age-based bands is the quickest way to get a mediocre result. Products like the NAA guide or the 10-times-salary rule were never meant to replace an actual analysis. They are marketing shortcuts. I have seen them land people three times undercovered and three times overcovered for the same family structure. Use them only as a sanity check, never as the final answer. Ignoring liquidity constraints is another frequent error. A worksheet might tell you that you need a two million dollar policy. But if you are a high earner with most of your wealth tied up in a deferred compensation plan and a privately held business, a two million dollar death benefit might arrive slowly or not at all if the insurer disputes the application due to health disclosures. Match the death benefit structure to the actual liquidity timeline of your estate. Not adjusting for state-specific probate rules matters more than most people realize. In community property states, the surviving spouse may inherit policy proceeds differently than in common law states. Certain creditor protections vary by jurisdiction. If the family lives in a state with aggressive probate timelines, an oversized lump sum death benefit can get consumed by legal fees before anyone sees it. Factor in an approximate estate settlement cost of two to five percent of the gross estate as a buffer line item.
What the Life Insurance Needs Analysis Worksheet cannot do for you
It cannot replace a conversation with a financial advisor who understands your full picture. The worksheet is a calculation engine, not a decision framework. It will tell you what the gap is. It will not tell you whether term or permanent insurance is appropriate, whether you should lock in rates now or wait, or whether your current health status justifies accelerated underwriting versus standard processes. I have watched clients use a worksheet to justify purchasing a whole life policy when a term policy would have covered the gap at a fraction of the cost. The tool produced the right number. The product recommendation came from elsewhere. It also struggles with blended families, second marriages, and situations where one spouse has significant pre-existing debt. Standard worksheets assume a single nuclear family structure. If your situation deviates from that, you will need to manually adjust sections or build custom line items. There is no universal version of this worksheet that handles every scenario cleanly. If you find yourself spending more than thirty minutes trying to make the worksheet fit your situation, you are better off switching to a spreadsheet with custom fields or working with someone who has built this model before.
Where to find a usable template
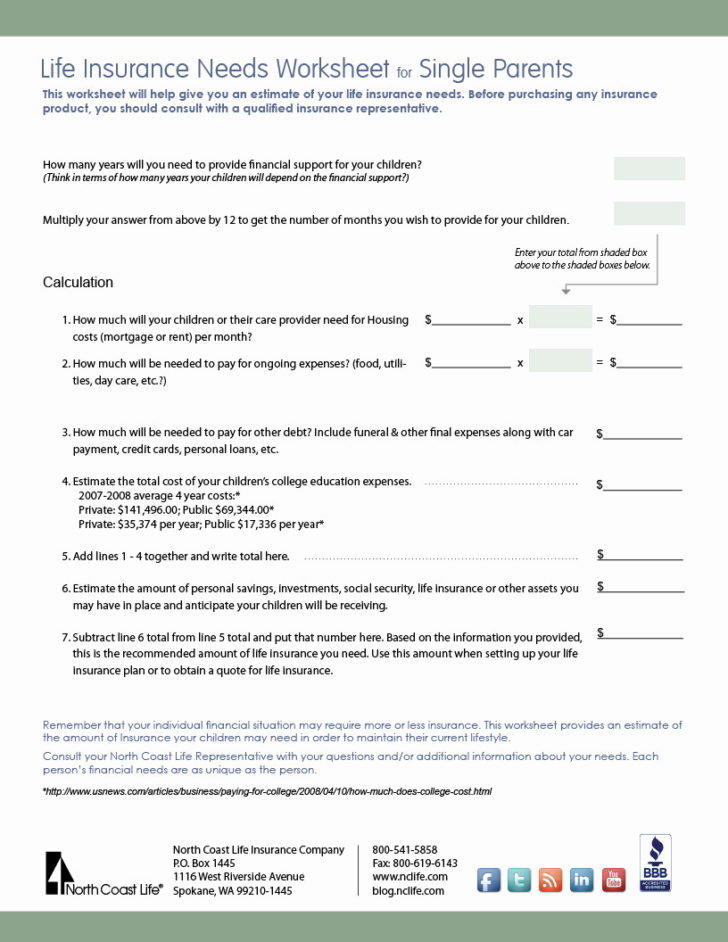
Most industry associations publish free worksheets. The American Institute of Chartered Financial Consultants, the National Association of Insurance and Financial Advisors, and several major carriers offer downloadable versions. The ones you want are the detailed multi-section forms, not the one-page summary sheets. A usable worksheet should have at least twelve line items and room for assumptions documentation. If a template has fewer than eight fields, it is a brochure, not a tool. I usually recommend starting with the NAIFA standard needs analysis worksheet, then adding custom rows for edge cases like business obligations, special needs trusts, and state-specific estate costs. That hybrid approach gives you a solid foundation while preserving flexibility for situations that the standard form was not designed to handle.
Running the numbers correctly
Use current dollar values, not nominal future projections. When you list debts, use the payoff balance as of today, not the original principal. When you calculate income replacement, use after-tax income, not gross salary. When you factor in investment returns, pick a number you are comfortable defending and document why you chose it. A four percent real return assumption is defensible. A ten percent assumption is not, and anyone who reviews this worksheet will know the difference. Re-run the analysis every three to five years or after any major life event. Marriage, divorce, birth, death, business sale, inheritance, job change. These shift the numbers significantly. I once recalculated a client's coverage after his father died and left him an inheritance that was already earmarked for a sibling's education. The worksheet should reflect that money is no longer available for the spouse, even though it increased the client's personal net worth. Context matters more than raw totals. The output of a well-executed needs analysis is not just a face amount. It is a documented rationale that shows where every number came from, what assumptions were made, and what variables could change the result. If you hand that to an advisor or an underwriter, you save hours of back-and-forth. If you leave it undocumented, you have a piece of paper that is useless the next time someone asks how you arrived at the conclusion.


