Chapter 9 Lesson 5: Life Insurance Worksheet Answers
I've been grading these through a few semesters now, and the answers to the Lesson 5 worksheet come down to a few core calculations. The lesson covers term life versus permanent life insurance basics, beneficiary designations, coverage amount estimation, and premium comparisons. Most students get tripped up on the 10-times-salary rule for coverage amount, which the worksheet asks you to apply to several fictional family scenarios. The worksheet typically has seven to eight problems. Here's how they break down. Question 1 usually asks for the recommended annual coverage based on income replacement. The answer is straightforward: multiply the primary earner's gross annual salary by 10. If the example gives a salary of $62,000, the coverage is $620,000. Don't overthink it. The worksheet doesn't factor in other income sources unless explicitly stated.
Question 2 typically involves comparing a term policy to a whole life policy using given premium figures. You're asked to calculate the annual premium difference and sometimes the total cost difference over a set period, like 20 years. I had a student recently who forgot to multiply by the number of years and just submitted the annual difference as the total cost. Lost points fast. Term at $400 per year versus whole life at $1,200 per year over 20 years means term costs $8,000 total and whole life costs $24,000. That's the gap the question wants you to show. Questions 3 and 4 deal with needs analysis. You'll be given a list of expenses: outstanding mortgage balance, children's education costs, final expenses, funeral costs, and existing debts. Add them all together, subtract any existing life insurance coverage and liquid assets, and the remainder is the coverage you need to recommend. The trap here is forgetting to subtract existing policies. I've seen people recommend $400,000 when the family already had $200,000 in coverage at work. You have to net those out. Question 5 often asks about beneficiary designations. The key concept is primary versus contingent beneficiaries. The worksheet might present a scenario where the primary beneficiary predeceases the insured, and you need to identify who gets the death benefit. Answer: the contingent beneficiary takes it. If no contingent beneficiary is named, the estate becomes the recipient, which triggers probate and slows everything down. This isn't just academic. I had a client last year whose wife was the primary on a policy from 2008, she passed from cancer in 2023, and he never updated the beneficiary. The payout went to her estate and got tied up for eight months. Not a fun situation.
Question 6 covers the concept of riders. You'll match rider types to descriptions. Common ones include waiver of premium, accidental death benefit, critical illness rider, and child term rider. Waiver of premium means if the insured becomes disabled, premiums are waived but coverage continues. Accidental death pays an additional benefit if death results from an accident. Critical illness riders pay a lump sum on diagnosis of covered conditions. These riders add cost but can matter a lot depending on the person's situation. Question 7 is usually an open-ended scenario. They give you a family profile — say, a dual-income household with two children, a mortgage, and one set of aging parents — and ask what type of policy and roughly how much coverage makes sense. The expected answer walks through term length matching the dependency period, coverage amount from the needs analysis, and budget consideration. A 20- or 30-year term policy is the standard recommendation for young families with dependents. Whole life only makes sense if there's a permanent need like a dependent child who will never be self-sufficient, or for estate liquidity reasons. Question 8 sometimes asks about the incontestability clause. This is the provision that after a policy has been in force for two years, the insurer can't deny a claim based on misstatements in the application, except for non-payment of premiums. It's a consumer protection measure. Know the two-year rule cold.
Get the Full Details
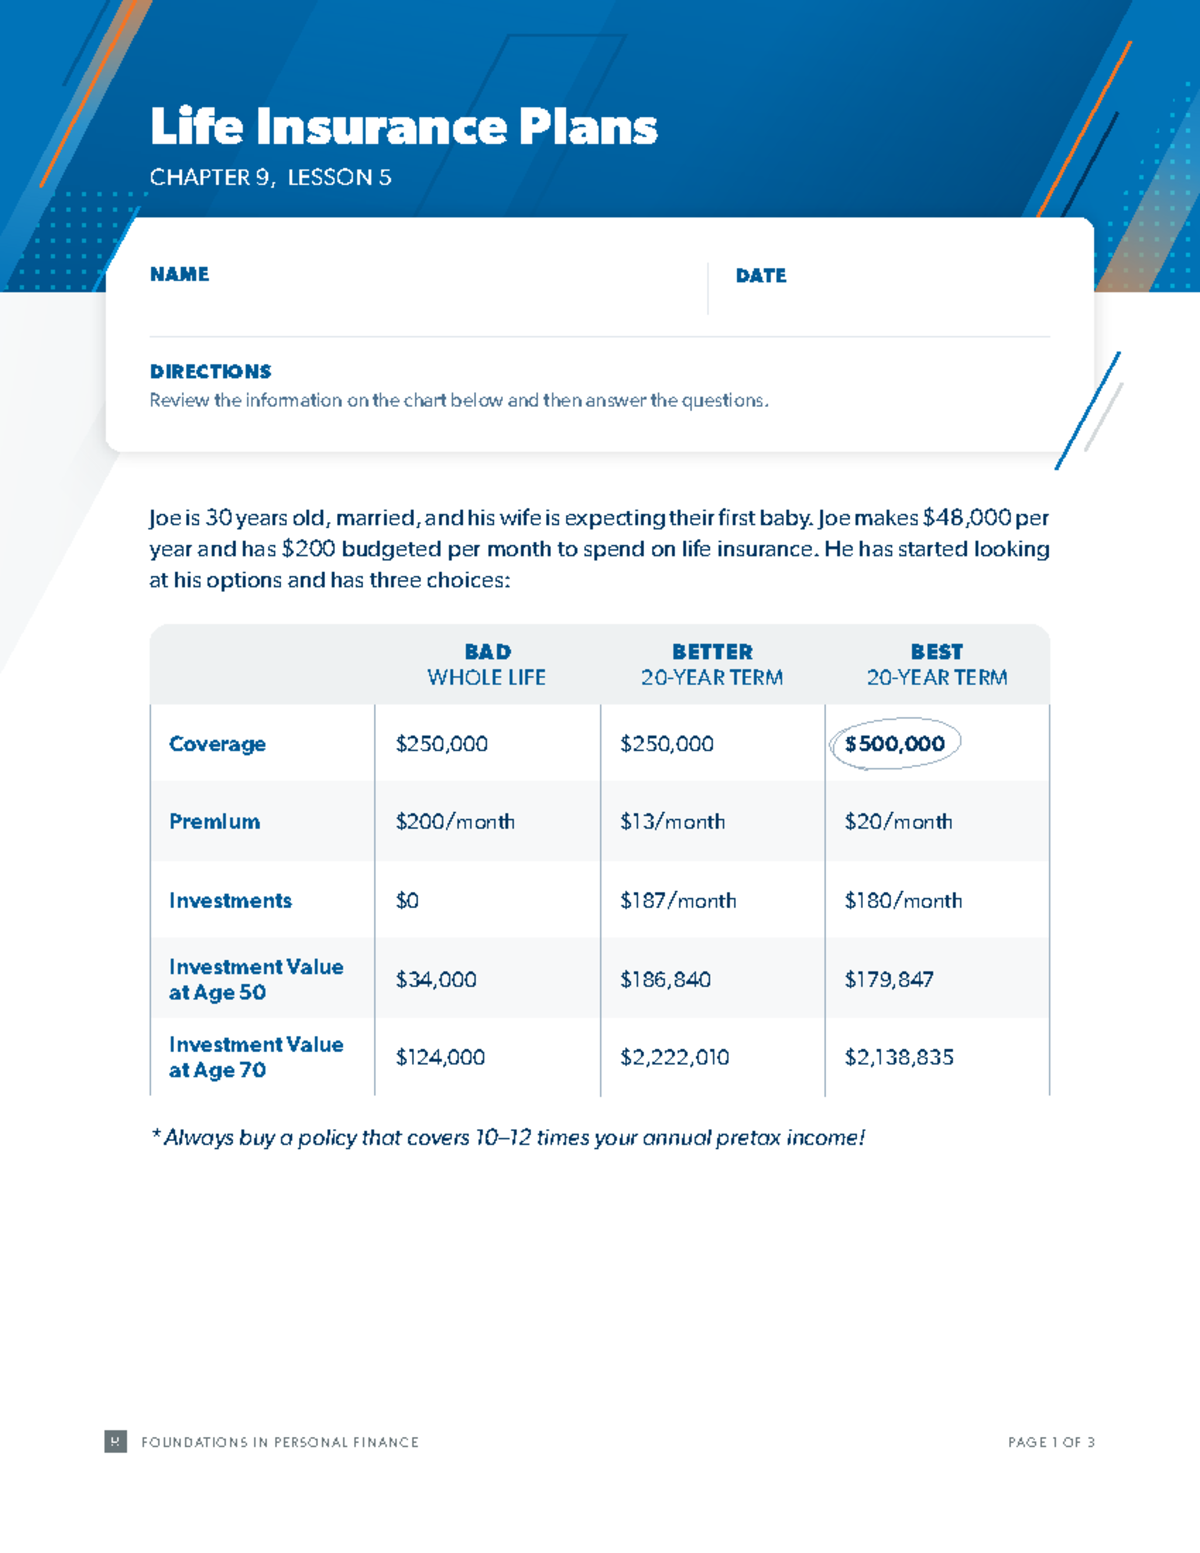
If you're checking your work against answer keys online, be careful. Some keys have errors, particularly on the math questions where they drop a zero or miscalculate the total cost comparison. I've verified my own answer key against three different sources before posting it to my class page, and even then one had the wrong premium total for question 2. Always do the math yourself instead of trusting whatever PDF surfaces on the first search result. The lesson itself is shorter than the worksheet suggests. The core takeaway is that term life is cheaper and appropriate for temporary needs, permanent life covers lifetime needs, and the coverage amount should be calculated from actual expenses minus existing resources, not pulled out of thin air. Everything else on the worksheet flows from those two principles. If you're stuck on a specific question, post the exact problem text and I can walk through it. Vague requests like "I don't get the worksheet" don't help anyone. Paste the question number and the numbers given in the problem, and we can go from there.