What You Actually Need to Know About Life Insurance Practice Tests
Most people treat practice tests as a shortcut. They download a free PDF, answer questions until they get 90%, and feel ready for the licensing exam. That approach fails more often than it succeeds. The core problem isn't the test content itself. It's that the questions on real state licensing exams are written by professional psychometricians who specifically design them to test your ability to think through a scenario, not your ability to recall a definition. Memorizing answers from a practice bank is almost useless because the exact same question will rarely appear twice, and even when the topic overlaps, the wording shifts enough to make your memorized answer irrelevant. A proper Life Insurance Practice Test approach starts with understanding the structure of the actual exam. Each state has its own exam provider. Pearson VUE runs many of them, but a handful of states use Prometric or their own proprietary vendor. The exam typically breaks into two sections: national questions covering general life insurance principles, and state-specific questions covering your jurisdiction's regulations, sliding scale commissions, and local consumer protection laws. The national portion usually makes up about two-thirds of the exam, though this varies. You need roughly 70 to 75 percent correct to pass, but the passing threshold differs by state. Some set it at 70, others at 75 or higher. Check your state's department of insurance website before you do anything else. It saves you weeks of studying the wrong passing standard.
Life Insurance Practice Test: How to Actually Use Them
The way most people study is wrong. They flip through a question bank, mark answers, check the key, and move on. This passive method creates an illusion of competence. You recognize the question pattern and recall the answer without truly processing the underlying concept. A more effective method involves active retrieval. Read the question, close the book or put the app away, and force yourself to explain the answer out loud as if you were teaching it to someone else. If you cannot explain why answer C is correct and answer D is wrong, you have not actually learned that concept yet. This takes longer, but the retention difference is significant. Another practical technique is timed simulation. Set a timer for the exact duration of your state's exam and work through a full practice test without interruption. Most state exams run between 60 and 90 minutes with 60 to 100 questions. Sitting down to answer questions under real pressure exposes weaknesses that open-book review never reveals. I remember one agent who consistently scored above 85% on untimed practice sets but kept failing his actual licensing attempt. His issue was time management, not knowledge. He spent nearly two minutes on early difficult questions, ran out of time on the later ones, and panicked. Once he started doing full timed simulations and practiced moving on after 45 seconds when stuck, his pass rate improved dramatically. The practice test showed him he had knowledge gaps. The timed simulation showed him he had a pacing problem. The best practice questions mirror the style of your actual exam provider. If you are taking a Pearson VUE exam, find resources that specifically mention that vendor, because each provider has a slightly different question construction style. Some lean heavily on numerical calculation. Others prioritize scenario-based reasoning. Reviewing sample questions from the correct vendor gives you a realistic sense of what to expect.
Which Topics Show Up Most Often
Certain subjects appear consistently across nearly every state exam. Terminology is one area people underestimate. Understanding the difference between a named beneficiary, a primary beneficiary, and a contingent beneficiary sounds basic, but the exam mixes these concepts in ways that trip up unprepared candidates. If a primary beneficiary predeceases the insured and no contingent beneficiary is named, the proceeds typically pass to the insured's estate, which then triggers probate and creditor claims. Questions about this sequence appear frequently. Premium payment methods is another high-frequency topic. Limited pay, ordinary life, single premium, and extended term insurance are standard categories, but the exam also tests narrower distinctions like the paid-up additions option or automatic premium loans. A common trap question involves an unpaid premium during the grace period. The policy remains in force during those 30 to 31 days depending on state law, but if the insured dies during that window, the claim is paid minus any outstanding premiums. Many students forget the deduction part and pick the wrong answer. Policy dividends deserve attention too. Participating policies issued by mutual companies return dividends, and the exam expects you to know the standard dividend options: cash withdrawal, premium reduction, accumulated at interest, one-year term, and paid-up additions. The paid-up additions option is usually the one most agents recommend for long-term growth because it purchases additional fully paid shares of stock that also earn dividends themselves, creating compounding effects. Questions sometimes ask which option provides the greatest long-term cash value growth, and the answer is generally paid-up additions, not one-year term, which is the cheapest way to use dividends temporarily.
Get the Full Details
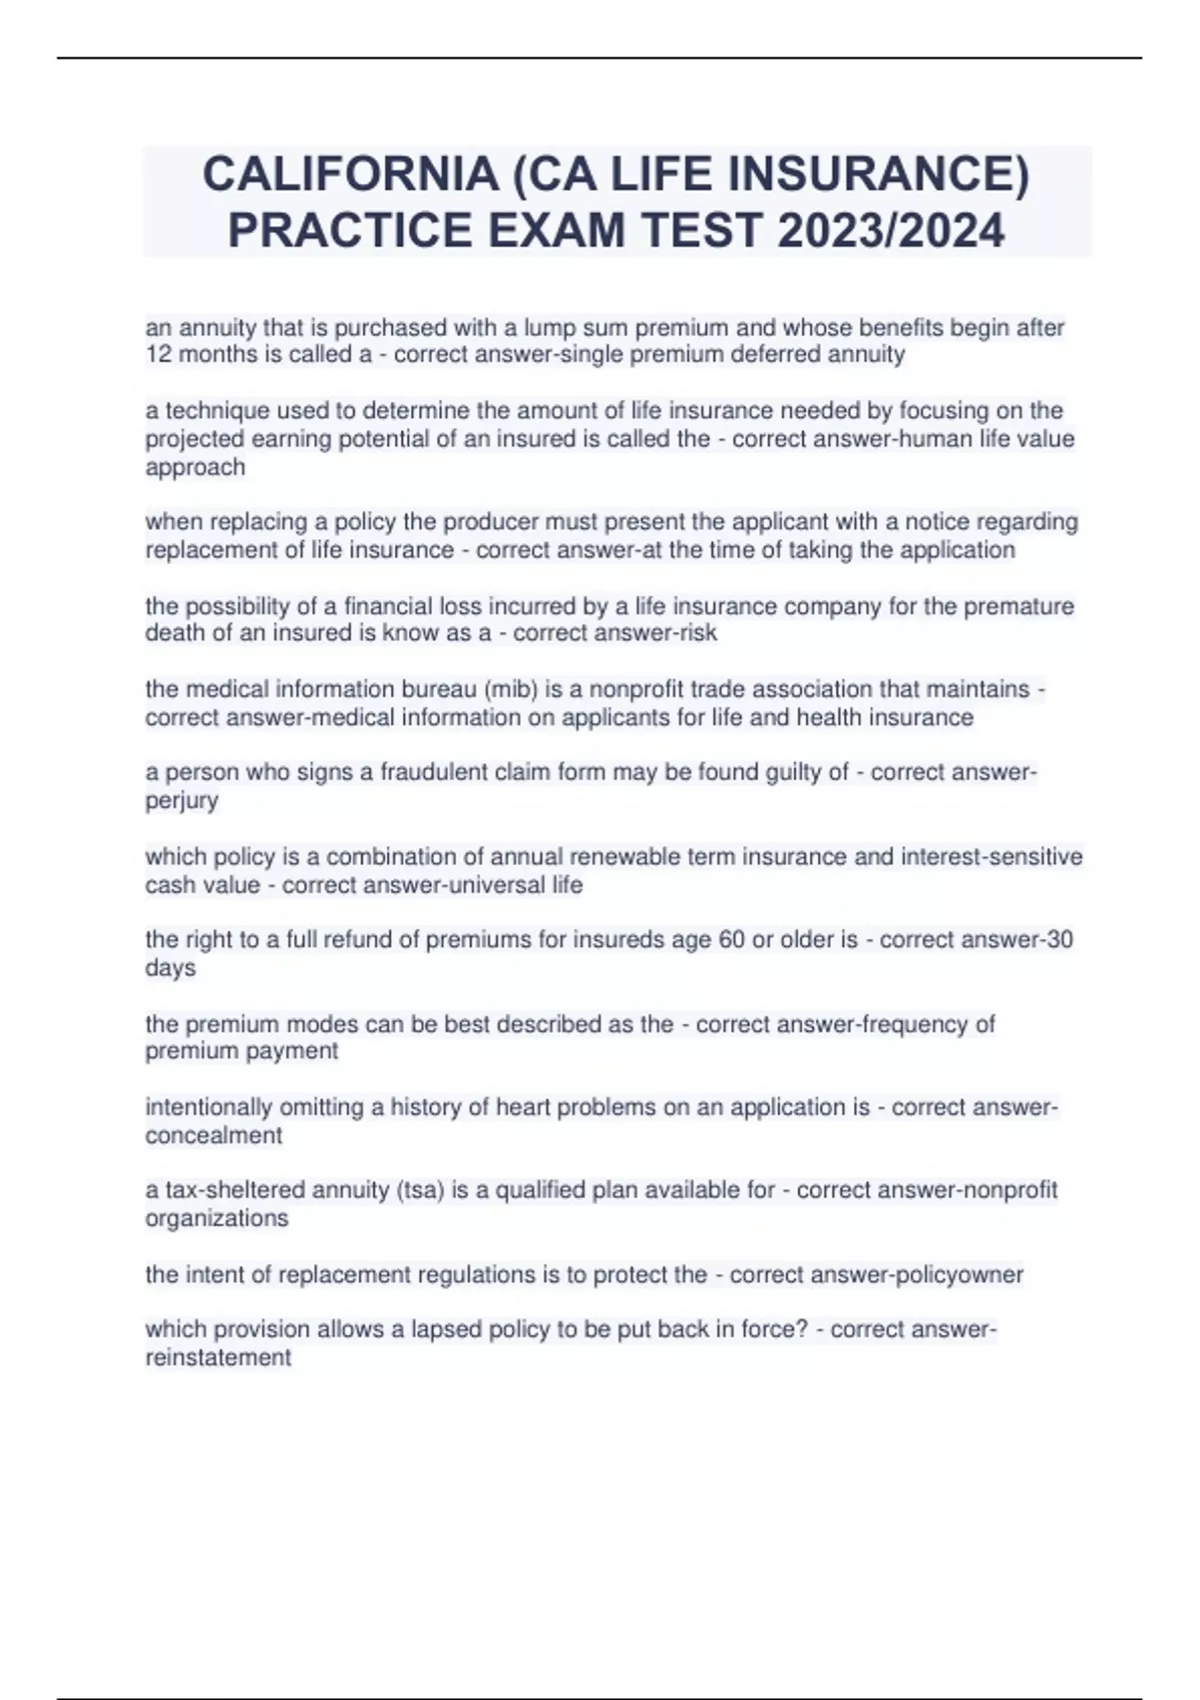
Settlement options for death benefits are also heavily tested. The lump sum payment is the default and the simplest option, but the exam often presents a scenario where a minor inherits or where the beneficiary wants steady income over time. In those cases, the extended term insurance settlement, the income stream settlement, or the annuity settlement become relevant. Know the trade-offs between them.
Calculation Questions You Cannot Avoid
Some states include numerical problems, and even states that do not officially test calculations still require you to understand the math behind policy features. Cash value growth, premium calculations, and loan interest impact are fair game. You should be comfortable with basic time value of money concepts. If a policy has a cash value of $50,000 and you take a $10,000 loan at 6 percent interest, you need to understand that the loan does not reduce the death benefit dollar for dollar unless it goes unpaid. The death benefit remains face value minus any outstanding loan plus accrued interest. Misunderstanding this distinction causes incorrect answers on a surprising number of questions. I had a student once who failed her exam because she kept choosing the wrong answer on a loan-related question. The question asked what happens to the death benefit after a policyholder takes a loan and then passes away. She picked face value minus loan amount, which sounded logical, but the correct answer was face value minus loan plus accrued interest. She did not account for the interest compounding against the policy. She had studied the concept but missed the specific mechanic. After switching her practice strategy to focus on worked examples instead of flashcards, she passed on the second attempt. Reading about a calculation is not the same as working through one from scratch.
Common Pitfalls That Derail People
The biggest mistake I see is relying on a single practice test provider. Every question bank has blind spots. One provider might cover tax implications thoroughly but skimp on state-specific rider questions. Another might excel at policy types but fail to include enough regulatory law questions. Using multiple sources covers these gaps. I recommend combining at least two reputable practice test providers and cross-referencing any topic you feel uncertain about. Another pitfall is ignoring the state-specific portion entirely until the last week. Many agents spend weeks on national content and treat their state laws as an afterthought. This is backwards. State-specific regulations are often straightforward once you read them, but they are numerous and specific. Knowing your state's exact grace period length, free-look period, and sliding scale commission structure is essential. These details change between states and can be the difference between passing and failing on narrow margins. Finally, do not skip the ethical and regulatory questions. These cover the unruh act, deceptive practices, rebating, twisting, and cohibitation. Each state has specific rules about what constitutes illegal rebating. In some states, offering a gift with a policy is a violation. In others, it depends on the gift's value. Know your state's line. The exam will ask about it directly.

Where Practice Tests Fall Short
No practice test covers everything you will see on the actual exam. This is a fundamental limitation. The question banks available commercially contain thousands of items, but the actual exam draws from a much larger pool that vendors do not publish. Even the highest-quality practice test will miss topics that appear on your specific test date. Treat practice tests as a diagnostic tool, not a guarantee of content coverage. They tell you what you do not know, not what you will definitely be asked. Another limitation is the gap between practice test scenarios and real-world complexity. Practice questions tend to present clean, simplified situations. Real policy situations involve overlapping complications: a beneficiary dispute, a policy loan, an outstanding premium, and a changed health status all at once. The exam does not always simulate this level of messiness, which means passing a practice test does not automatically mean you can handle the nuances of actual policy advising. Supplement your practice testing with case study reading and real policy illustrations whenever possible.
Free Resources and Where to Find Them
Several free practice test resources exist online. Insurancy offers a free state-specific practice exam after you create an account. Themortgageprofessor.com provides free sample questions organized by topic. Preproval maintains a paid library but also posts free quizzes for many states. None of these are perfect, but they are useful starting points, especially combined with your state's department of insurance study materials. Your state's DOI website often provides an official exam outline or candidate bulletin that lists the exact content areas and weightings. This document is more reliable than any commercial guide and should be your primary reference for structuring your study plan. If you prefer a structured self-study course, Preproval and Kaplan Financial Education both offer comprehensive packages that include practice tests, video lessons, and study guides. These are paid products but generally cost between $100 and $300 depending on the state and package level. The investment is reasonable relative to the cost of retaking the exam, which most states charge $50 to $150 per attempt for.
A Practical Study Schedule
Most people need between 40 and 80 hours of focused study to pass on their first attempt, though this varies by individual background. If you already work in insurance or finance, the lower end of that range may apply. If you are coming from a completely unrelated field, plan toward the higher end. Break your study time into daily blocks of two to three hours rather than marathon sessions. Consistency matters more than volume. Studying two hours every day for three weeks builds better retention than studying eight hours straight on Saturday. Structure your weeks around practice tests. Begin with a diagnostic test to establish your baseline. Review every wrong answer thoroughly and note which topic it belongs to. Spend the following week focused on weak areas using textbooks, videos, and targeted quizzes. End the week with another full timed practice test under realistic conditions. Repeat this cycle three or four times before your scheduled exam date. Track your scores over time. If your score plateaus or declines, shift your strategy rather than grinding more hours on the same material. More studying is not always the answer. The Life Insurance Practice Test is a tool, not a solution in itself. It works well when used deliberately and combined with other study methods. It fails when treated as a checklist to rush through. The agents who pass tend to be the ones who study actively, acknowledge their weaknesses early, and adjust their approach based on what the tests reveal rather than what they hope to see.