Most people treat life insurance as a single product. It isn't. It's two separate machines bolted together: protection against dying too soon, and a place to park money that grows slowly. When those two functions get mixed up, premiums explode and policies underperform. The finance side is usually where things break down.
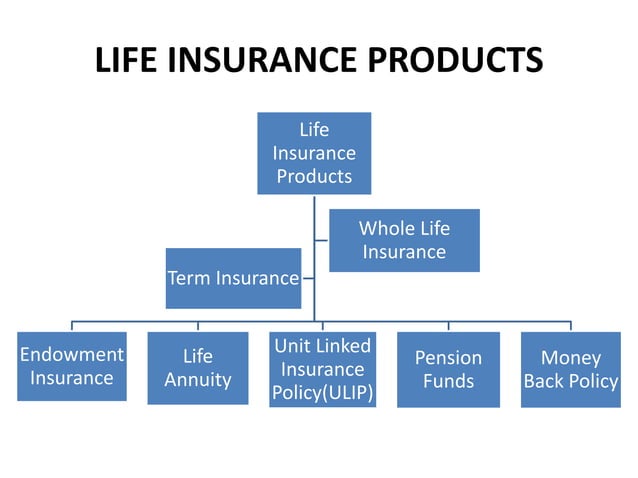
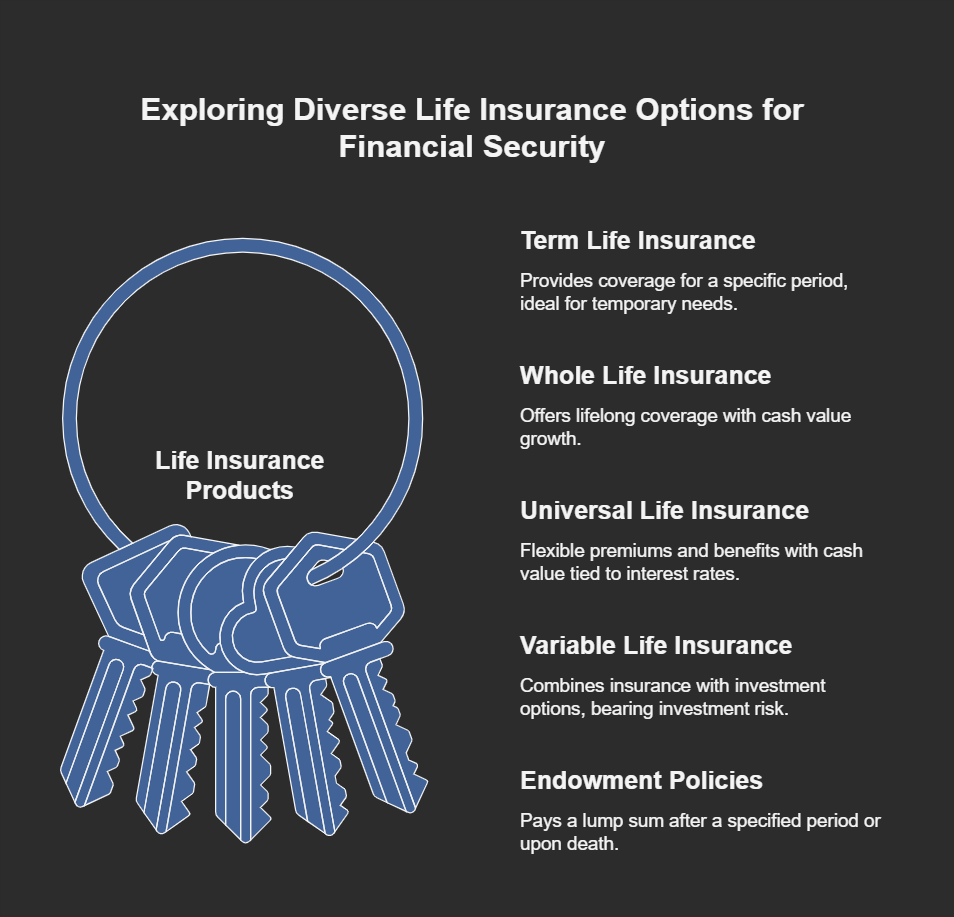
Here's how it actually works in practice. Term life covers a specific period at a low price. Whole life covers you forever and builds cash value at a fixed rate. Universal life flexes both the premium and the death benefit, and the cash value tracks an interest rate or an index. Variable life puts your cash value into subaccounts that move with the market. Each one has a different cost structure, tax treatment, and liquidity path. Pick the right one for the actual liability you're trying to cover. Don't pick the one your agent wants to sell you.
Life Insurance Products And Finance
The finance part matters because premiums are paid over years, but claims happen once. Insurers price using mortality tables, interest assumptions, and expense loads. Your premium buys three things: the death benefit, the cost of insurance, and any savings component. In term policies, you're paying almost entirely for the first two. In permanent policies, a slice goes to the savings piece, which is why premiums are five to ten times higher for the same face amount.
Cash value growth is not a secret wealth hack. It's taxable deferred, which helps if you're in a high bracket now and expect to be lower later. But surrender charges usually lock that money away for seven to ten years. Withdrawals up to your basis are tax-free. Amounts above that are taxable as ordinary income. Loans against the policy are tax-free as long as the policy stays in force. If it lapses with an outstanding loan, the insurance company treats the gain as a distribution and you owe taxes on it.
I ran into a specific case a few years back where a client had a high-cost variable universal life policy from the late nineties. The interior riders were charging roughly $400 a year in mortality and expense fees, and the subaccounts were underwater. The policy looked like it was growing on paper because the death benefit was level, but the cash value was shrinking every quarter. I asked for a full illustration with current columns, compared the cost of insurance to a new term policy, and ran a 12B2E exchange analysis. The workaround was to convert the permanent portion to a one-pay whole life policy inside the same contract, drop the underperforming subaccounts, and shift the death benefit to a level term rider. That cut the annual carrying cost by about sixty percent and stopped the cash value bleed without forcing a surrender tax hit.
If you're buying term, match the term to the liability. Twenty years of term makes sense if you have a mortgage that pays down in twenty years and kids who become independent around eighteen. Thirty years makes sense if you want to leave a legacy or cover a special-needs child. One-year renewable term is cheap but prices jump sharply after age fifty. Level term locks your rate for the full period. Guaranteed renewable term lets you renew without medical underwriting, but the premium increases are built in.
Whole life is straightforward but expensive. You pay a fixed premium, the cash value grows at a declared rate, and dividends are possible but never guaranteed. The internal rate of return on the cash value typically sits between four and five percent after fees. That's fine if you need forced savings and a predictable payout. It's poor if you want growth. A common mistake is comparing whole life dividends to term investment returns without accounting for the insurance component. You're paying extra for the permanent coverage and the tax deferral. If you don't need that, you're overpaying.
Universal life gives you flexibility. You can adjust premiums within limits and change the death benefit type. Type A pays the face amount plus accumulated cash value. Type B pays only the face amount, so the cash value grows tax-free because the cost of insurance is deducted from the account value. The tradeoff is complexity. Interest rates reset periodically, and if your credited rate drops while your cost of insurance rises, the policy can become underfunded quickly. I've seen policies lapse because the owner didn't increase premiums when the indexed credit rate fell below the internal assumption.
Indexed universal life tracks a market index with a participation rate and a cap. The downside is the cap. Even if the index jumps twenty percent, your credit might be limited to eight percent. The upside is protected by a floor, usually zero percent. That protection comes at a price. The annual renewal rates often include option costs that reduce the effective return. If you're buying IUL, insist on a detailed illustration that shows the credited rate under multiple scenarios, not just the maximum.
Variable life puts your cash value in subaccounts. Returns vary with market performance. There's no guaranteed minimum cash value. If the markets drop hard, the policy can fail unless you add premiums or reduce the death benefit. It's useful if you want market exposure inside a life insurance wrapper, but it's not a substitute for a well-diversified investment account. The tax advantages are real, but the fees can eat seven to nine basis points per year across management and rider costs.
Simplified issue and guaranteed issue policies skip medical exams. Premiums are thirty to fifty percent higher for the same face amount. They're appropriate when you have health issues that make standard underwriting impossible or when you need coverage within days. Don't buy them unless you have to. The underwriting savings from a standard policy usually outweigh the convenience cost.
Here's a practical workflow that saves time. Start with a liability estimate. Add outstanding debts, final expenses, income replacement for dependents, and any special needs funding. Subtract existing assets and existing coverage. The gap is your target death benefit. Run term quotes for that gap. If you need permanent coverage for estate planning or a special-needs trust, get illustrations for whole life and universal life side by side. Compare the cost of insurance per thousand, the projected cash value at year ten and year twenty, and the lapse scenario at your expected premium. Don't compare premiums alone. A cheaper premium with a higher cost of insurance will outpace you later.
If your policy is already in force, pull the current illustration and the original contract. Check the in-force showing for the last three years. Look at the cost of insurance charges, the credited rate, and the cash value trajectory. If the cash value is declining while premiums are level, the policy may be on a lapse path. Contact the carrier for a non-forfeiture alternative or a paid-up reduction. Reducing the face amount to a paid-up equivalent often preserves some coverage without requiring new premiums.
Downsides are real. Term policies expire with no value. Permanent policies carry high upfront costs. Indexed and variable products have caps, floors, and market risk that can undermine projections. Surrender charges reduce liquidity. Loans reduce the death benefit if unpaid. Lapsed policies trigger taxes. None of these are dealbreakers, but they are constraints you need to model before you commit.
A few numbers that matter. A healthy forty-year-old male might pay roughly twenty to forty dollars per month for a twenty-year level term policy with a half-million face amount. The same person buying whole life for that face amount could pay four to six hundred dollars per month. Universal life might fall in between, depending on the design and credited rate. These are rough ranges. Actual pricing varies by carrier, state, and medical class. Use current illustrations, not brochure estimates.
If you want a quick check on whether your current policy is still optimal, run a policy review using the in-force illustration, your current age, and your actual financial situation. Compare the cost of maintaining the policy versus buying term plus investing the premium difference. The breakeven point usually appears around year ten to year fifteen, depending on the product and your investment returns. Before making changes, verify tax consequences and surrender charges. A premature surrender can wipe out years of growth with a single tax event.
The bottom line is simple. Life insurance is a tool, not an investment account. Use it for the risk you can't absorb yourself. Keep the finance mechanics transparent. Watch the costs. Revisit the design when your life changes. Policies that stay aligned with actual liabilities perform well. Ones that chase returns or ignore fees tend to disappoint.
Gallery Life Insurance Products And Finance
Life insurance products and finance : charting a clear course : Atkinson, David B : Free ...
LiFe InsUraNcE anD iTs ProDucTs aNd PreMiuM PayMenT | PPTX
Life insurance premium finance loans: 9 Powerful Benefits 2025
Life Insurance Products | College Hive
Harnessing the Power of Premium Finance Life Insurance: | by Tomer Dicturel | Medium