What You Actually Need to Know Before Filling Out a Life Insurance Application
I spent twelve years underwriting term policies before moving into consulting, and the single most frustrating thing I see isn't the paperwork itself, it's the people who treat it like a formality instead of a financial commitment. Life Insurance Questions And Answers come down to one thing: honesty, but specifically accurate honesty. Lying on an application isn't just rude, it voids the entire policy when they find out. And they will find out. Every major insurer runs a paramed exam, pulls your MIB records, checks your prescription history, and cross-references your medical database. If you check "no prescription medications" while taking blood pressure pills, your beneficiary gets nothing. Simple as that. The average application takes between 20 and 45 minutes depending on your health complexity. If you've been treated for cancer, have a BMI over 40, or smoke regularly, expect to answer follow-up questions that add another hour or so. It's not the end of the world, it's just part of the process. Insurers are not trying to scam you out of a payout, they're trying to figure out if you're a liability they can price correctly.
Common Life Insurance Questions And Answers That People Get Wrong
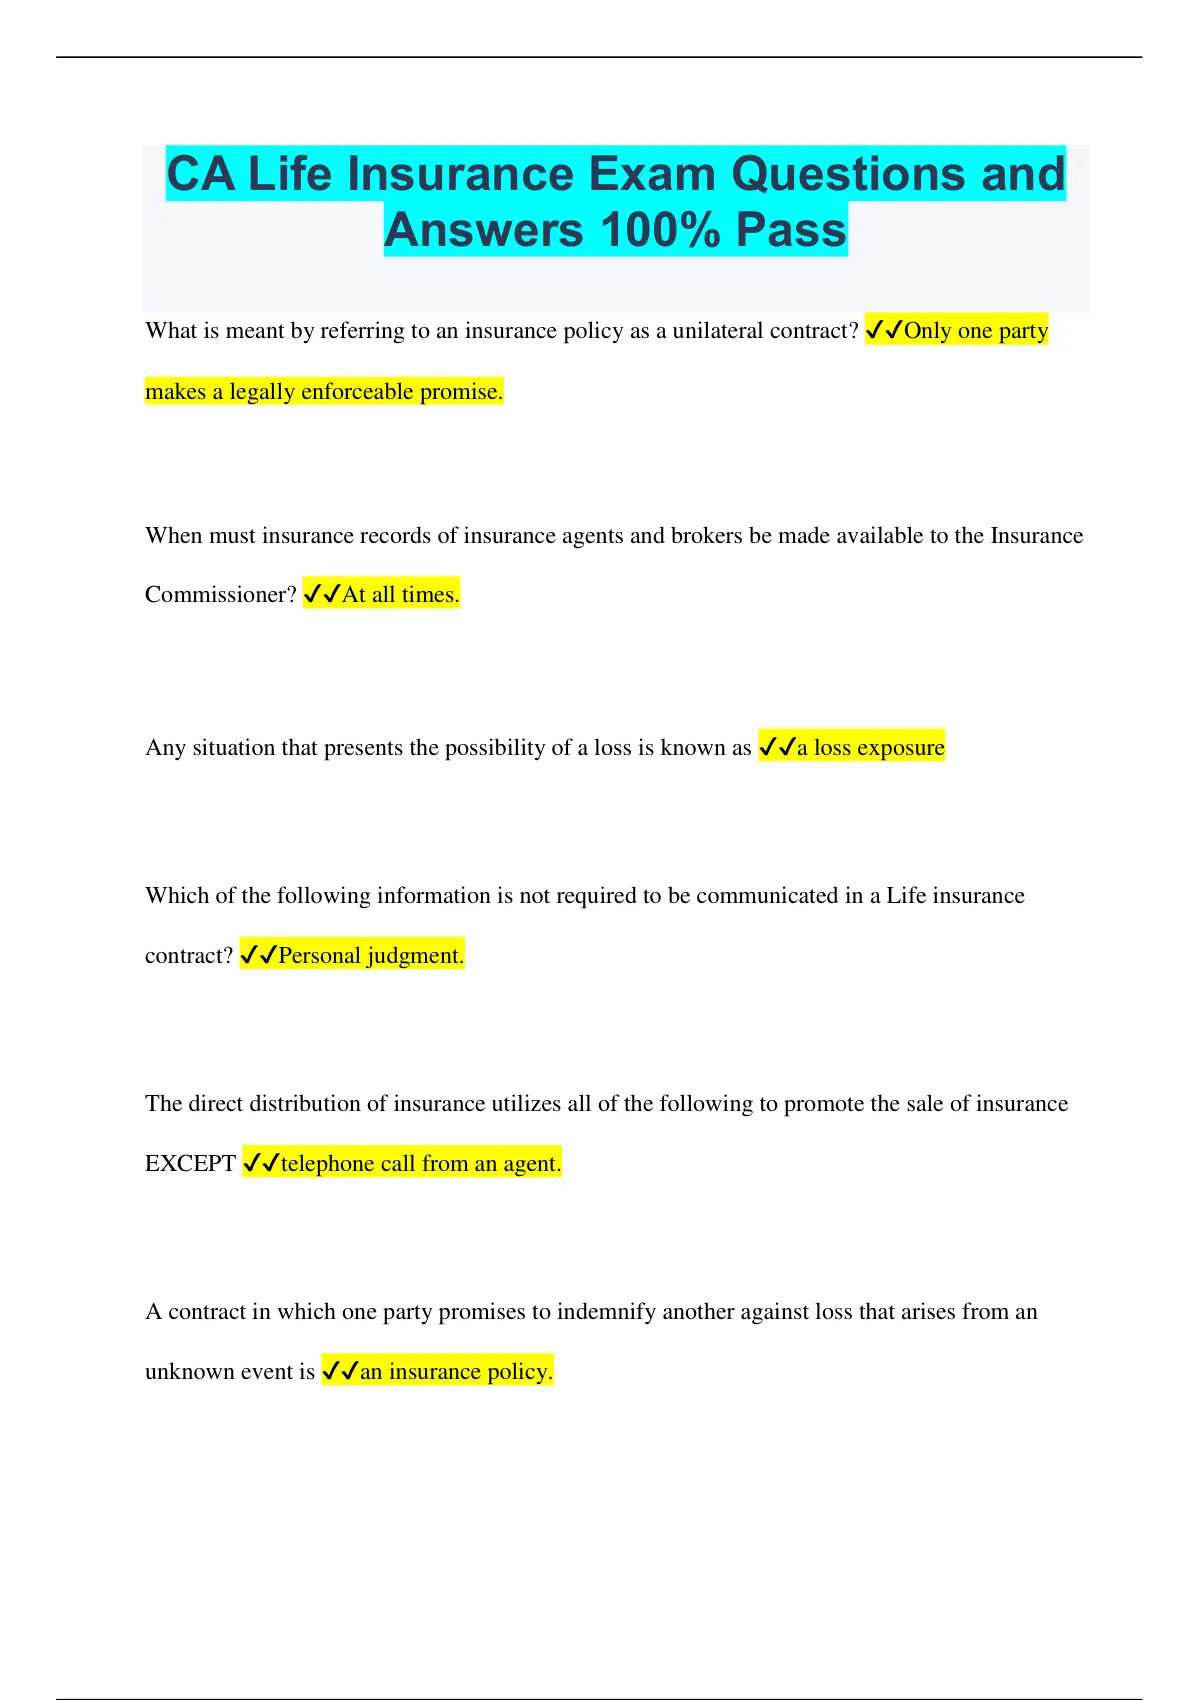
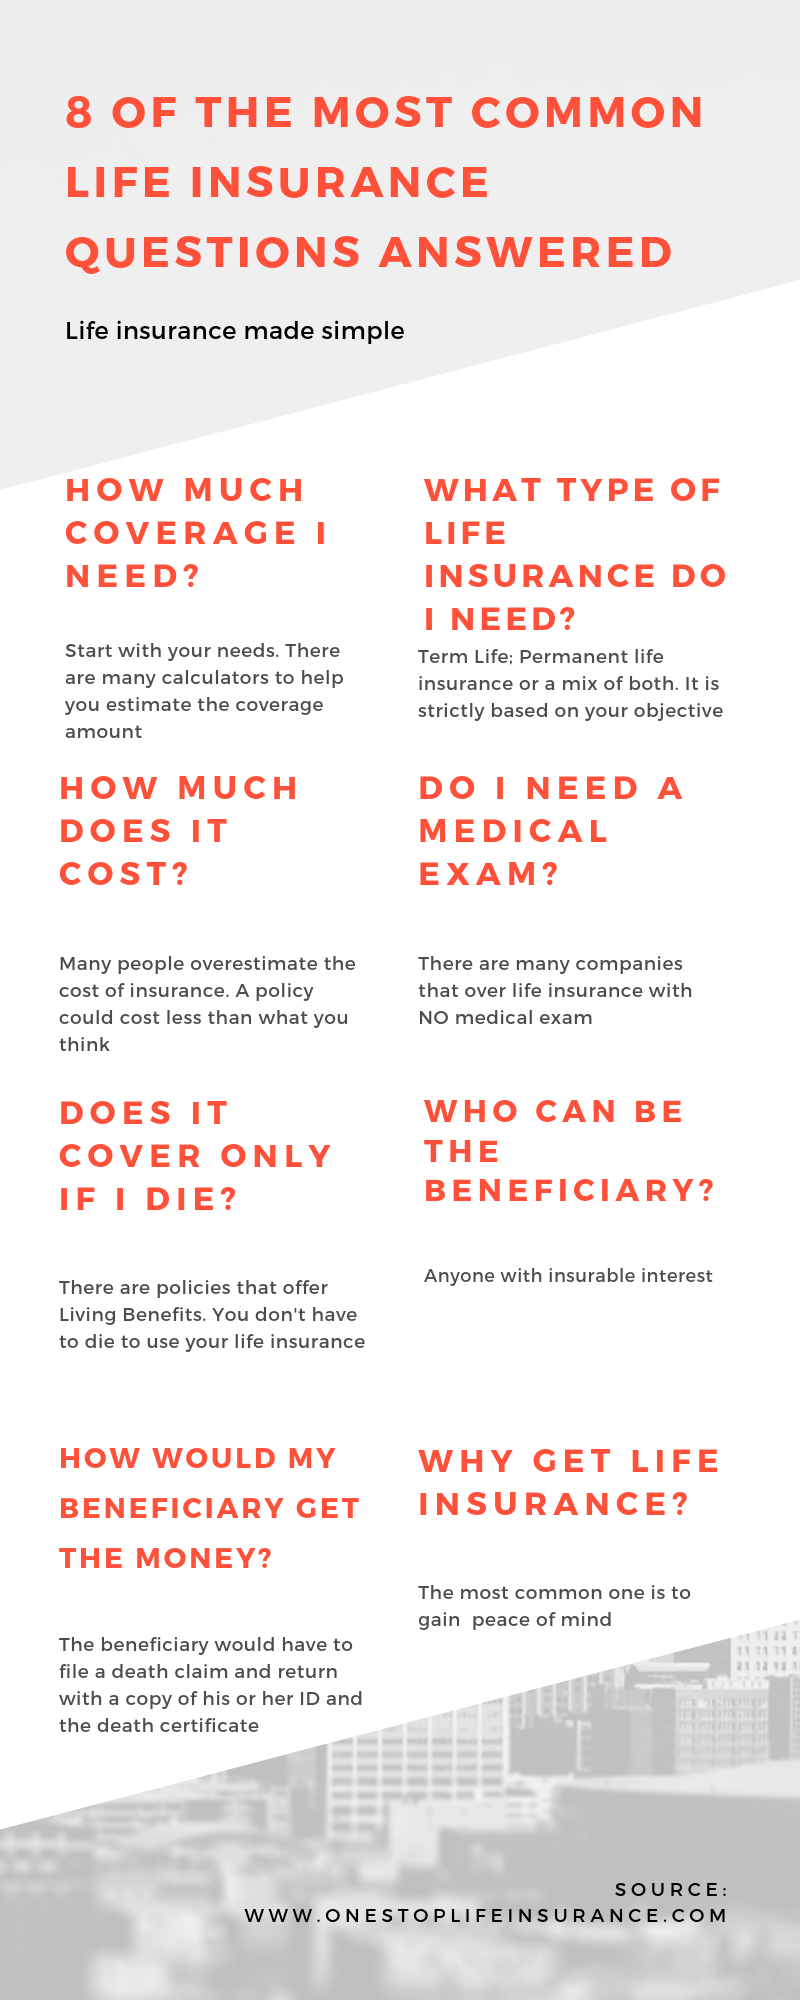
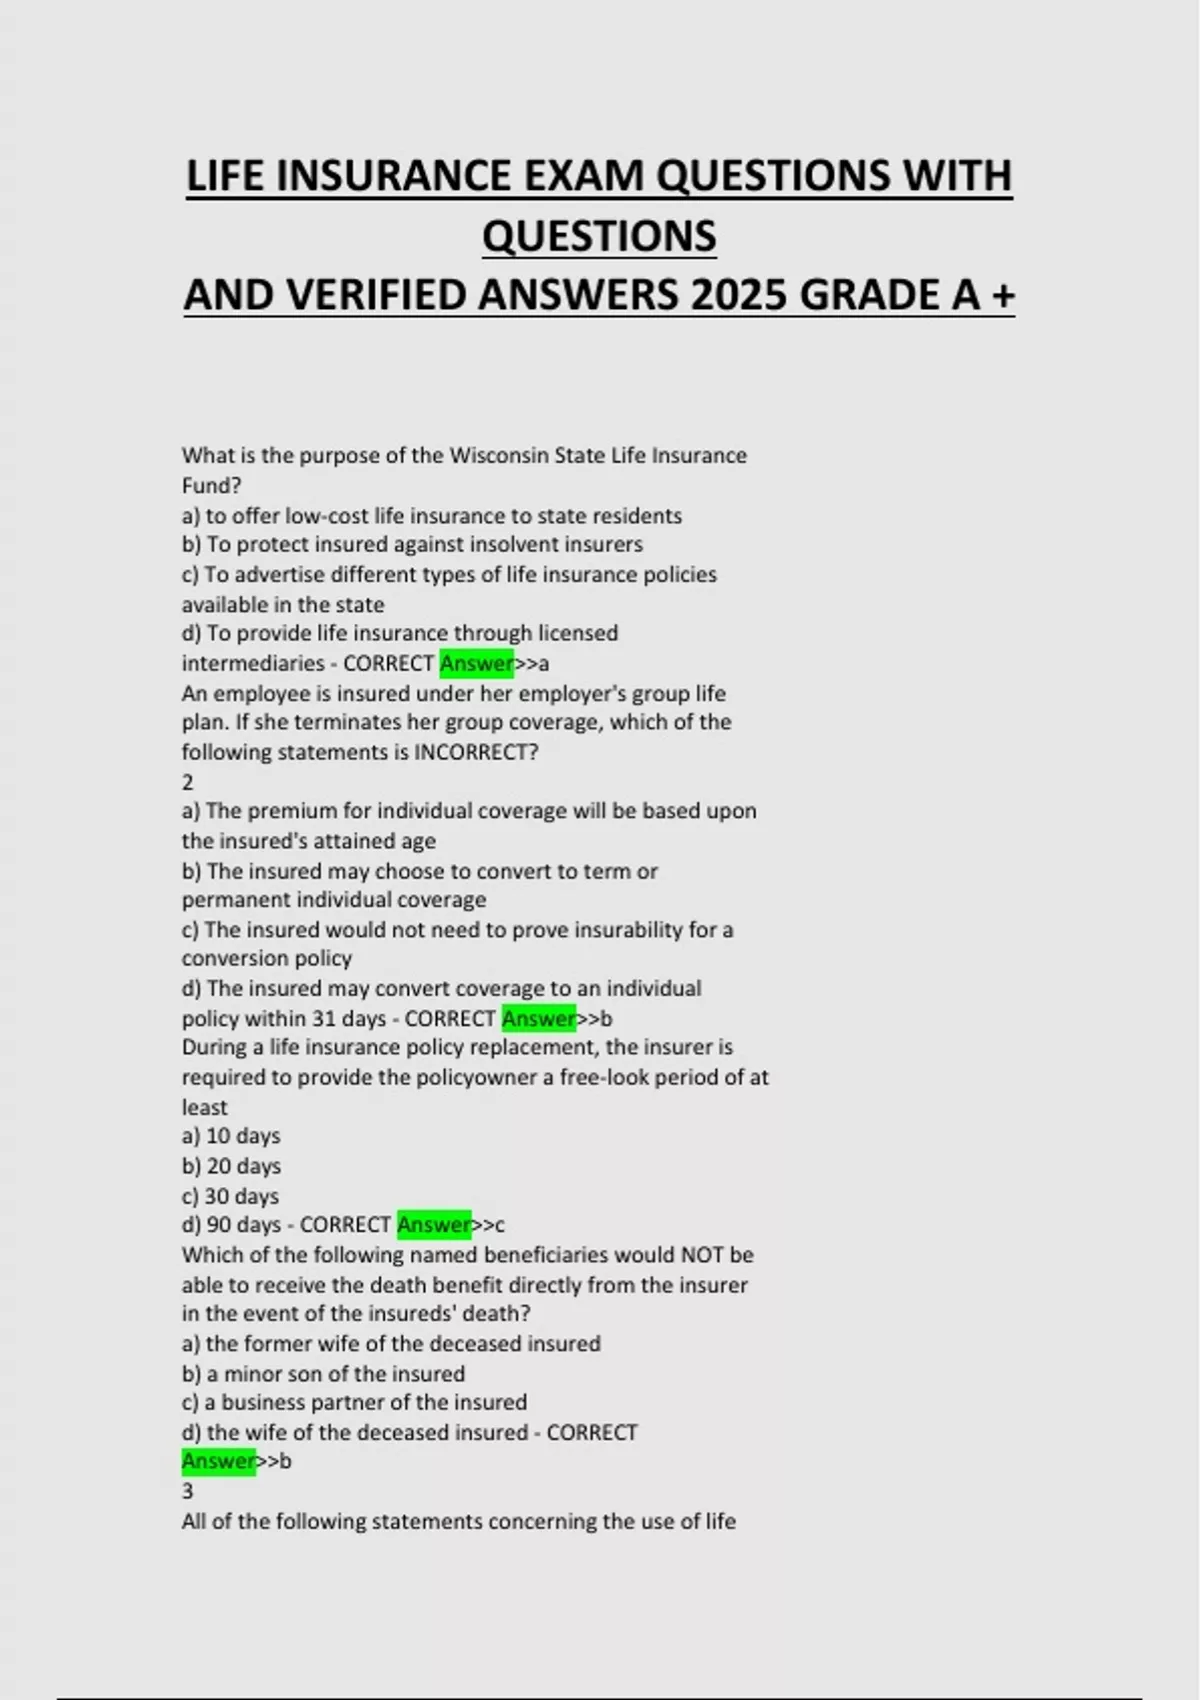
Here are the questions that trip people up most often. The answers are almost never what applicants think they should be. Do you use tobacco or nicotine? This seems straightforward until someone says they only vape occasionally or they used to chew dip but quit six months ago. A "no" here only works if you haven't touched nicotine in at least a full year, and some carriers require two. Vapes count. Nicotine patches count. Even the occasional cigar at a wedding makes you a smoker in their system. The premium difference between a smoker and non-smoker rate can be 200 to 300 percent, so don't cheap out on this answer. Have you had any medical issues in the past five years? "Medical issues" is deliberately broad. A broken arm from last year? Probably doesn't matter. A hospital stay for gallbladder? That goes on the record. A blood test that showed slightly elevated liver enzymes? Yeah, they'll ask about that. When I was still in underwriting, I had one applicant who denied a single abdominal ultrasound he had "for routine checkup purposes." We pulled the record within a week. He ended up getting denied coverage altogether because the inconsistency destroyed his credibility. A minor issue you voluntarily disclose looks responsible. One you hide looks like fraud.
What is your occupation? This isn't just about what job you have, it's about risk exposure. A desk worker and a construction foreman might have the same annual salary, but their rates differ significantly. Some applications let you code your job under a NAICS code, which the insurer uses to calculate hazard risk. Don't inflate your title to sound more impressive. "Senior project manager" when you spend 40 percent of your time climbing scaffolding doesn't help you. Put the actual duties down. Are you currently prescribed any medication? Again, this is broader than people realize. Antidepressants, ADHD medications, birth control, even seasonal allergy meds can trigger a medical inquiry if you're applying for a large policy. Most standard term life policies won't reject you for being on medication, but they will want to know the diagnosis behind it. SSRIs usually get a standard or mildly rated policy. Anti-anxiety meds combined with a substance use history can bump you to table ratings. Table ratings mean extra premiums, usually 25 to 75 percent above standard, but not a denial. Knowing this before you apply helps you pick the right carrier.
Get the Full Details
The Process Nobody Tells You About
After you submit the application, there's a waiting period that makes most people nervous. The 30 to 60 day window between application and policy issuance is where things actually happen behind the scenes. Your medical exam gets scheduled, usually within a week. The paramedic comes to your home or office, draws blood, checks your vitals, and sends everything to the insurer's medical department. Meanwhile, your MIB report gets pulled, your prescription database gets checked, and your driving record gets reviewed if you're over 50 or applying for a high face amount. I've seen healthy 35-year-olds get their policy issued in 14 days flat. I've also seen otherwise fine applicants stuck in limbo for 90 days because they had an unresolved cardiac stress test from two years ago that the new insurer wanted re-evaluated. Delays like this aren't punishment, they're just how the machinery works. The person you applied through doesn't always have access to the same underwriting information as the carrier's internal team, so they can't always tell you why you're waiting. One thing I learned the hard way: never apply to multiple insurers at the exact same time if you have a complex health history. Hard credit inquiries aren't the issue here, it's the duplicate medical requests. If three different companies are pulling your same records and ordering your same paramed simultaneously, you create a tangled mess of conflicting reports. Your broker should coordinate this for you. Apply to one primary carrier, and if that falls through, move to the next. Parallel applications are fine for clean, healthy applicants. They're a disaster for anyone with pre-existing conditions.
What Happens If You Get Rated or Declined
This is the part most people don't want to think about, so they skip reading it entirely. Getting rated means you'll pay more. Getting declined means you get nothing. Both are common, and neither is permanent. A standard table rating adds a percentage to your base premium. Table 2 is usually plus 25 percent, Table 3 is plus 50 percent, and Table 4 is plus 75 percent. Some carriers go as high as Table 8, which is roughly double the standard rate. The good news is that your rating is locked in for the policy term. If you get a heart attack two years after being issued a Table 3 policy, your premium doesn't go up. The bad news is that a high table rating on a 20-year term for a $500,000 policy could mean the difference between $60 a month and $110 a month. Over the life of the policy, that's six thousand dollars you'd rather not spend unnecessarily. If you're declined by one carrier, try another. Different companies have different appetites for risk. An insurer that declines you for a history of migraines might rate you standard if you apply to a carrier that specializes in neurological conditions. This is where having a broker who actually understands underwriting guidelines matters. Generic agents will send your application anywhere. Good brokers know which companies are friendly toward specific health profiles.
Tax Implications Most People Ignore
Life insurance death benefits are generally income-tax-free to your beneficiary. That's the whole point. But there are scenarios where the IRS gets involved, and they're almost always avoidable if you plan ahead. If you own a policy worth more than $100,000 in death benefit and your estate is large enough to trigger federal estate tax, the policy payout becomes part of your taxable estate. For most Americans this doesn't matter because the estate tax exemption is around $13.61 million per individual as of 2024. For wealthy individuals, it absolutely matters. The workaround is putting the policy in an irrevocable life insurance trust, or ILIT. The trust owns the policy, the trust pays the premiums, and the death benefit goes to the trust beneficiaries outside of your estate. It costs about $2,000 to $4,000 to set up and requires annual maintenance, but it saves significant estate tax for high-net-worth individuals. There's also the MEC, or Modified Endowment Contract, issue. If you overfund a cash-value policy by paying in too much premium too quickly, the IRS reclassifies it as a MEC. MECs lose their favorable tax treatment. Withdrawals come out taxable, and early withdrawals before age 59½ incur a 10 percent penalty on the gain portion. Most people never intend to create a MEC, it happens accidentally when someone tries to use a life insurance policy as a short-term savings vehicle. It's a mistake that costs real money.
The Online Application Trap
Buying life insurance online is faster, cheaper, and often perfectly fine. But it comes with a tradeoff you should understand before you click "submit." Online applications are usually processed by a smaller group of carriers that have automated underwriting systems. These systems are great for healthy people in their 20s and 30s with no medical history. If you're over 50, have diabetes, or have ever been hospitalized, the automated system will either decline you or offer you a terrible rate because it doesn't have the nuance to evaluate your situation the way a human underwriter does. I've watched brokers save clients from online rejections by simply picking up the phone and explaining the circumstances that a drop-down menu couldn't capture. One client had a thyroid nodule that was biopsied and found benign. The online system saw "thyroid condition" and auto-declined. A human underwriter reviewed the pathology report and offered standard rates. That's the difference between doing it yourself and having someone who knows the system on your side.
What to Do When the Policy Is Issued
Your policy arrives, usually by mail or through your agent's portal. Read it. Not the summary page, the actual contract. Check that the beneficiary names are correct, the face amount matches what you applied for, and the term length is right. Mistakes happen more often than people expect. I found a policy once where the insured had written "John" as the beneficiary's first name but his legal name was "Jonathon." The insurer processed it as written, and when the claim was filed, the beneficiary had to provide a legal name correction before the payout was released. It added three weeks of delay to an already difficult time. Store your policy documents somewhere safe and make sure your beneficiary knows where they are. Put a copy in your will, but don't rely on your will as the primary document. Life insurance payouts bypass probate entirely, which is one of its main advantages. But if your beneficiary can't find the policy number, the insurer name, and your contact information, the claim process starts with a paperwork search instead of a simple call.
Final Reality Check
Life insurance is a contract, not a product you buy at a store. Once it's signed, you can't return it. Once it's issued, you can't change your health history. The questions matter because the answers lock in your rate for the entire term. Take the time to be thorough, be honest, and if something feels unclear, ask your agent to explain it before you sign. A confused signature costs more than an hour of clarification. The industry is old, slow, and occasionally frustrating, but for the vast majority of applicants it works exactly as designed. You disclose your health, they assess the risk, they set the price, and you get a guarantee that your family gets paid when you die. Nothing mystical about it. Just paperwork, biology, and money. If you handle the paperwork honestly, the rest takes care of itself.