How To Actually Calculate Line Of Credit Interest
Most people think of their line of credit as a revolving credit card. It is not. The interest mechanics are fundamentally different, and getting them wrong will cost you money without you ever realizing it. I spent three years fixing loan portfolios for a regional bank before I left the industry. One of the most common errors I saw was borrowers underestimating how much interest accumulates during the draw period because they treated the calculation like a simple annual percentage rate problem. It is not.The core mechanism is straightforward enough. You borrow a portion of your available credit, and interest accrues daily on the outstanding balance at your stated annual rate. When you make a payment, it first covers accrued interest, then reduces principal. The next day's interest calculation uses the new lower balance. This daily compounding on a declining balance is what makes the math slightly different from a standard installment loan.
Using a Line Of Credit Interest Calculator
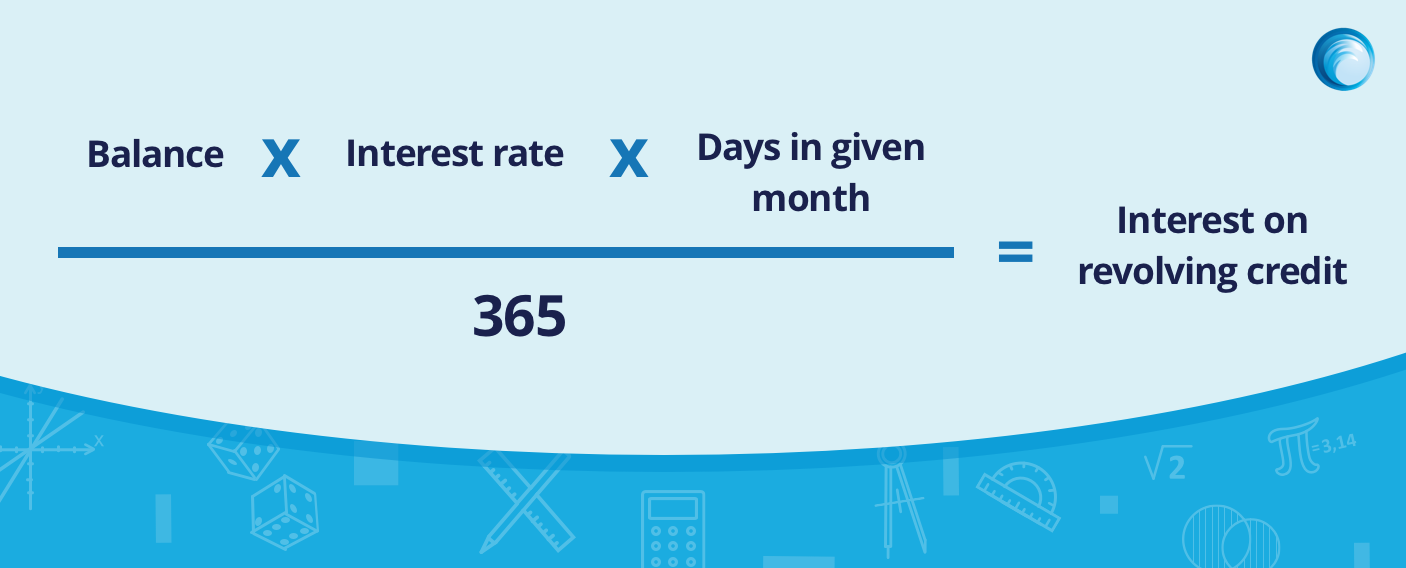
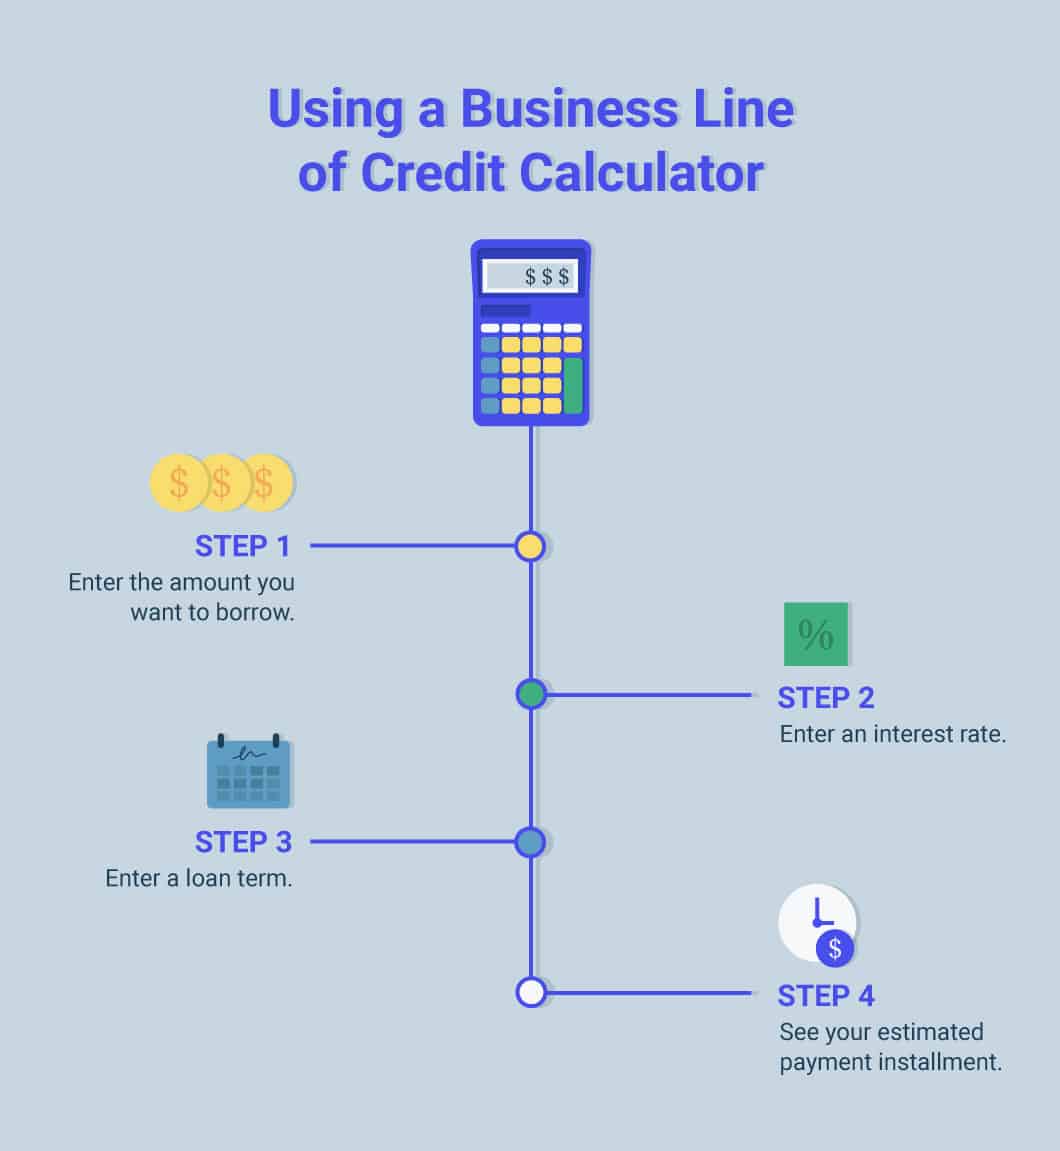
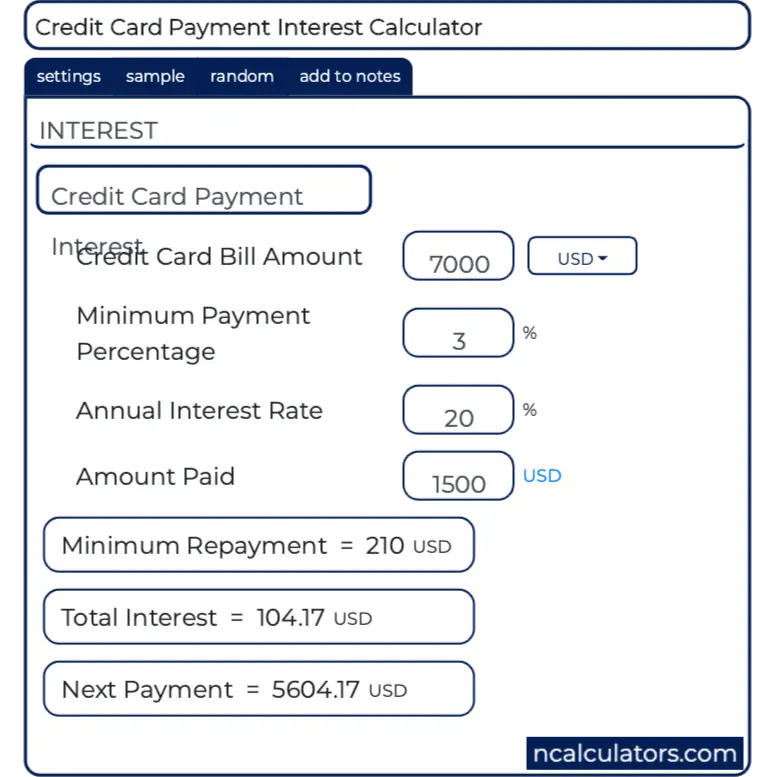
A Line Of Credit Interest Calculator takes your available credit limit, the amount you have drawn, your annual interest rate, and the time period you want to project. The output is your estimated interest charge for that window. Some calculators also show how additional payments reduce total interest over the life of the line. Here is the basic formula behind it. Daily interest equals your outstanding balance multiplied by your annual rate divided by 365. So if you owe $15,000 on a 9.5% line, your daily charge is approximately $3.90. That number changes every time you draw more or pay down. Most online calculators automate this but still require you to input a realistic payment schedule, or the numbers are useless.I once ran into a situation where a client had a home equity line structured with a 10-year draw period followed by a 20-year amortization recast. They were paying minimums during the draw phase and assumed their interest was simple. It was actually compounding daily, and when the recast hit, their payment jumped from about $280 a month to over $900 because the entire unpaid balance got re-amortized. A Line Of Credit Interest Calculator that accounts for the recast date would have shown this before they signed. The one they used did not.
The Details That Mess People Up
Not all lines of credit calculate interest the same way. Some use the average daily balance method, which smooths out fluctuations if you are drawing and paying within the same billing cycle. Others use the daily balance method, charging interest on whatever you owe at the end of each day. The difference matters. If you draw $8,000 on day one of a 30-day cycle and pay it back on day 25, the average daily balance method gives you credit for that repayment for five fewer days than the daily balance method would. In practice, that is maybe $12 to $18 extra in interest depending on your rate. It seems small until you are carrying a six-figure balance over a year.Another thing most calculators silently ignore is the rate structure. Many lines of credit have variable rates tied to the prime index. If the prime moves 0.25 percent, your accrual rate moves with it. A calculator that locks in today's rate will give you a snapshot, not a forecast. For actual planning, you need to model at least two or three rate scenarios. I built a quick spreadsheet that let me toggle the rate up and down in quarter-point increments and see the impact on monthly interest. Took about twenty minutes to set up and saved me from bad advice multiple times.
Get the Full Details

What Happens When The Calculator Lies To You
Online calculators usually assume you will make fixed monthly payments toward principal. If your line is interest-only during the draw period, the calculator output becomes decorative. It is showing you a payment schedule that does not exist. The real question is what your balance will look like at any given point, not what a hypothetical principal-plus-interest payment would be.The bigger problem is fees. Some lines charge annual maintenance fees, transaction fees on draws, or early termination penalties. A standard Line Of Credit Interest Calculator will never include those. They are real costs that change your effective APR. If you are comparing a line against a personal loan, you need to add the annual fee to the interest total yourself. Otherwise you are comparing apples to orange juice.
When To Use One Versus When To Do It By Hand
Use a calculator when you want a quick estimate for budgeting or comparing two products. It takes about thirty seconds to get a ballpark figure. Do it by hand or in a spreadsheet when you need precision, such as planning a large draw for a renovation or evaluating whether paying down the line is worth it compared to another debt. Spreadsheet models give you control over the assumptions. You can build in rate changes, irregular payments, and fee schedules. A generic calculator does not.I keep a simple model that tracks daily balance projections. You enter your starting balance, your rate, your expected draw dates and amounts, and any planned payments. The sheet calculates daily interest and cumulative totals. It replaced the calculator for anything beyond a rough estimate. The setup time is reasonable, and once it is working, you just update it when your situation changes. That is far more reliable than re-entering numbers into a web tool every time you want a new projection.