Understanding How These Calculators Actually Work
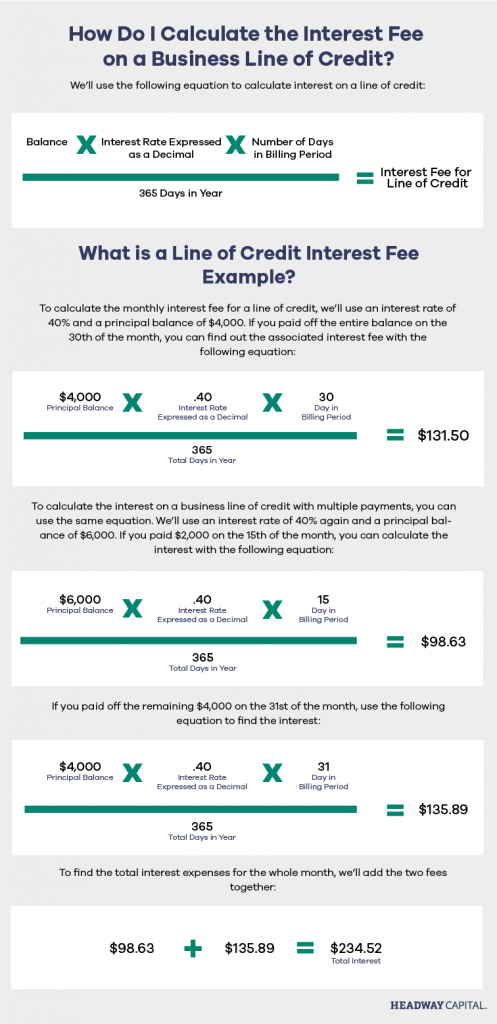
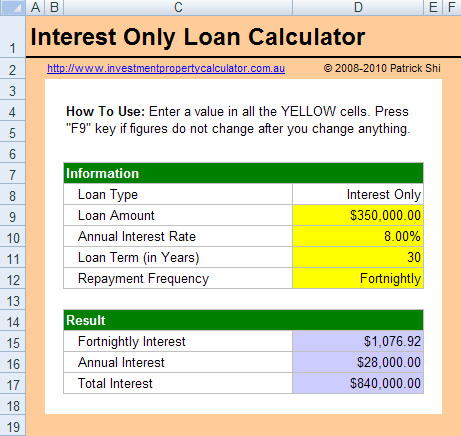
A Line Of Credit Interest Only Loan Calculator is basically a spreadsheet with better packaging. You plug in your credit line amount, the interest rate, and the draw period, and it spits out what your monthly payment looks like while you're only paying interest. Sounds straightforward until you realize most people don't understand what they're actually looking at when the number appears on screen. I ran into this a few years back with a client who was comparing a $250,000 HELOC against a traditional home equity loan. She told me the monthly payment was $1,200 and she thought that covered both principal and interest. It didn't. It covered interest only. The calculator wasn't broken, but her understanding of what the output meant was incomplete. Most online calculators won't tell you that this payment changes the second you start paying down principal, or that your payment can jump significantly once the interest-only period expires.
Line Of Credit Interest Only Loan Calculator
Here's how to get useful numbers out of one instead of just getting a misleading figure and calling it a day. You need five inputs at minimum. The credit line amount, the annual interest rate, the length of the interest-only period, the length of the repayment period after that, and how the lender calculates your minimum payment. Number five is the part everyone skips. Some lenders use a percentage of the outstanding balance, others use a flat amortization schedule from day one, and a few recalculate based on your current balance every quarter. If you don't know which method your lender uses, the calculator output is essentially decorative. Take a specific case. I worked with someone who pulled $80,000 against a line of credit at 7.5% for a renovation. The calculator showed $500 a month during the 5-year interest-only window. She budgeted for $500 and kept going. At the end of year five, the payment recalculated over a 20-year amortization on the remaining $80,000 balance, and her payment jumped to roughly $637. That's a 27% increase with no warning built into the original calculation. She'd already spent the money, so refinancing wasn't an option anymore.
The trick most people miss is that variable-rate lines of credit change your payment every time the index moves. If the prime rate ticks up half a point, your interest-only payment goes up too, even if you haven't borrowed another dollar. A good calculator will let you model rate changes, but most free online versions don't have that feature. You end up guessing at what your payment might look like two years out instead of knowing it. Here's another edge case that tripped me up once. A borrower had partially paid down his line from $150,000 to $90,000 before the interest-only period ended. The calculator output was based on $90,000, but his lender had a clause that reset the amortization period based on the original term length minus the time already elapsed. So instead of a fresh 20 years of payments, he was left with roughly 15 years on a reduced balance, and the monthly payment was higher than either he or the calculator had projected. Some lenders build this into their tools automatically. Most don't. If you're serious about using one of these calculators, you need to ask your lender three questions before you trust any number: how is the minimum payment calculated, what happens to the amortization schedule when the interest-only period ends, and how often does the rate adjust. Write down the answers. Put them into the calculator manually if you have to. The default assumptions most tools make are usually favorable to the lender, not to you.
Get the Full Details

There's also the question of whether paying interest only is actually saving you anything meaningful. The math says you're deferring principal, not reducing it. If you're using a line of credit to fund a business venture that returns 12% annually, then carrying a 7.5% interest-only balance is reasonable leverage. If you're using it to cover living expenses or consolidate high-interest credit card debt without a payoff plan, the calculator output is just a number that makes the problem look smaller than it is. The payment stays low while the balance stays high, and you're quietly building equity erosion that doesn't show up on any statement. For anyone who wants to dig into this more, I've put together a working spreadsheet version that handles rate changes, partial paydowns, and the amortization reset scenario I mentioned. It's more accurate than most browser-based tools because it forces you to input lender-specific terms instead of relying on generic assumptions. You can grab it and adjust the fields to match your actual loan documents. The standard calculators out there are fine for a rough estimate, but they'll never catch the clause your lender buried in section four of your note.