How Liquidity Actually Moves In Markets
I spent six months in 2019 watching a regional bank's deposit outflows eat through their Treasury holdings faster than any model predicted. The Fed's own liquidity coverage ratio said they should have been fine. They weren't. That gap between textbook liquidity and real-world liquidity is where most policy discussions go wrong. Liquidity Theory Evidence And Policy Solutions isn't one thing. It's a collection of empirical findings about how easily assets convert to cash without moving prices, plus the regulatory frameworks built on top of those findings. The evidence base is older than most people realize. Gallant's 1989 work on market depth and later empirical studies by Kyle, Subrahmanyam, and more recently Brunnermeier and Pedersen showed that liquidity isn't constant. It evaporates exactly when you need it most. That insight rewrote a lot of regulatory thinking after 2008. The core problem is that liquidity has two faces. There's on-balance-sheet liquidity, which is straightforward to measure. Cash, reserves, Tier 1 securities. Then there's market liquidity, which depends on willing buyers, bid-ask spreads, and the depth of the order book. Banking regulators spent the decade after 2008 trying to lock down the first face with the Liquidity Coverage Ratio and the Net Stable Funding Ratio. Both work under normal conditions. Neither accounts for the second face collapsing simultaneously across the system.
I ran stress tests for a mid-tier institution that used the LCR correctly on paper and still got caught in a funding spiral. The issue was counterparty liquidity, not balance sheet liquidity. When money market funds started redeeming, the bank couldn't roll short-term paper because the buyers had vanished. The Fed's discount window was theoretically available, but using it sends a signal that triggers exactly the panic you're trying to avoid. We ended up drawing on emergency collateral agreements with larger correspondent banks at a 400-basis-point premium. That's the real cost of illiquidity, not the spreadsheet number.
Where The Evidence Actually Points
The academic literature on liquidity theory has converged on a few uncomfortable conclusions. Liquidity provisioning is procyclical. Market makers widen spreads and reduce inventory during stress because their capital constraints bind tighter than your funding constraints. This isn't theoretical. During the March 2020 treasury market dysfunction, primary dealers couldn't absorb the Fed's outright purchases fast enough. The Repo Market got stuck. The Fed had to step in with overnight repos and permanent Treasury purchases just to restore basic functioning. Another finding that surprises people: liquidity risk is mostly concentrated in off-balance-sheet vehicles. Money market funds, commercial paper conduits, and even some repurchase agreement arrangements created liquidity transformation without the capital charges that come with traditional banking. The Shadow Banking Framework paper by Adrian and Shin quantified this. The leverage ratio of non-bank liquidity providers expands and contracts roughly three times faster than the traditional banking sector. That amplification is why the 2008 crisis spread so quickly through seemingly separate markets. Policy responses have addressed parts of this. The Dodd-Frank Act introduced the Volcker Rule to limit proprietary trading, but the liquidity provisions are scattered across multiple frameworks. The Basel III liquidity standards are bank-specific. They don't cover the shadow banking channel that matters most during crises. The SEC's money market fund reform in 2016 added swing pricing and conditional redemption gates, which helps, but those tools haven't been tested at scale since their implementation.
Get the Full Details
What Actually Works And What Doesn't
Permanent liquidity backstops work. The Fed's Primary Market Corporate Credit Facility and the Commercial Paper Funding Facility in 2020 showed that central bank willingness to buy risk assets changes market behavior immediately. The mere announcement compressed spreads by 50 to 80 basis points across investment-grade corporates. But permanent facilities create moral hazard. Banks and shadow creditors price their funding assuming the backstop will be there, which means they take on more short-term liability than they would without it. When the backstop is temporary, markets revert to correct pricing within days. When it's permanent, the distortion becomes structural. Collateral transformation is another tool with mixed results. The Fed's Main Street Lending Program tried to convert illiquid loans into liquid credit, but the program only booked around $2 billion against a $75 billion authorized capacity. The problem wasn't demand. It was that banks didn't want to originate loans they couldn't easily sell or pledge. The liability side of the balance sheet wasn't the constraint. The asset side was. This is the fundamental insight that most liquidity frameworks miss: you can't solve a funding problem with more funding. Sometimes you need to fix the collateral framework. The European Central Bank's approach has been different. Their targeted longer-term refinancing operations provide four-year liquidity at favorable rates, conditional on banks maintaining lending standards. The data shows this works for individual bank stability but does little for systemic liquidity. When the whole system is deleveraging, cheap funding from the central bank doesn't solve the problem that no one wants to lend to anyone else. The ECB had to pivot to pandemic-era quantitative easing because the targeted operations weren't moving the needle on interbank markets.
Edge Cases That Break The Models
I worked on a project assessing liquidity risk for a pension fund with a significant municipal bond allocation. The models showed adequate liquidity coverage based on average daily volume and bid-ask spreads. That was in 2022. When rates moved the way they did, the municipal market became illiquid almost overnight. There were no buyers for anything beyond the most liquid issues. The fund had to sell Treasuries at a loss to meet redemptions, which further depressed Treasury prices and triggered margin calls on their repo positions. This is the interconnectedness problem that static liquidity models ignore completely. Crypto markets present an even sharper version of this. The Terra/Luna collapse in 2022 showed that algorithmic stablecoins could maintain apparent liquidity through incentive mechanisms that collapsed when confidence shifted. The on-chain data looked fine right up until the moment it didn't. Liquidity pools drained in minutes, not hours. This isn't unique to crypto. It happened in the commercial paper market during 2008 too. The difference is that crypto markets operate 24/7 with no circuit breakers and no lender of last resort. Another edge case that policymakers keep missing: liquidity risk in illiquid asset categories creates contagion through accounting, not through direct exposure. Mark-to-market losses on held-to-maturity securities don't trigger defaults directly. They trigger capital adequacy problems, which trigger lending contraction, which triggers economic slowdown, which triggers defaults. The Sillicon Valley Bank failure in 2023 followed this exact path. Their HTM securities were fine if you held them to maturity. They didn't have to sell them. The deposit outflows forced the sale, realized the losses, and wiped out equity before regulators could respond.
Practical Frameworks For Assessment
If you're evaluating liquidity risk for an institution, start with the funding profile, not the asset profile. Most assessments focus on what the institution holds. What matters more is what funds it. A bank with 80 percent retail deposits and 20 percent wholesale funding behaves very differently from one with the opposite mix, even if their asset compositions are identical. Retail deposits are stickier. They don't flee on Twitter. Wholesale funding, especially brokered deposits and repurchase agreements, is price-sensitive and fast-moving. Build a liquidity stress matrix that combines multiple scenarios, not just a single baseline. The LCR gives you one number under a specific stress assumption. That's useful but insufficient. I recommend layering at least three scenarios: a market-wide stress similar to March 2020, aIdiotic-specific stress like the SVB case, and a combined scenario where both happen simultaneously. The combined scenario is where most institutions fail. The individual scenarios are manageable. Together they create compounding effects that exceed any single stress test. Monitor leading indicators, not lagging ones. Bid-ask spreads, trade volume, and rollover rates tell you about current liquidity. What matters for policy is predicting when liquidity will shift. The TED spread, the Amber Index, and cross-currency basis swaps are useful. More importantly, watch the behavior of your largest creditors. If your top five depositors represent more than 20 percent of total deposits, you have a concentration risk that no aggregate liquidity ratio captures. The SVB case is the textbook example here. Their deposit base looked diversified until it wasn't.
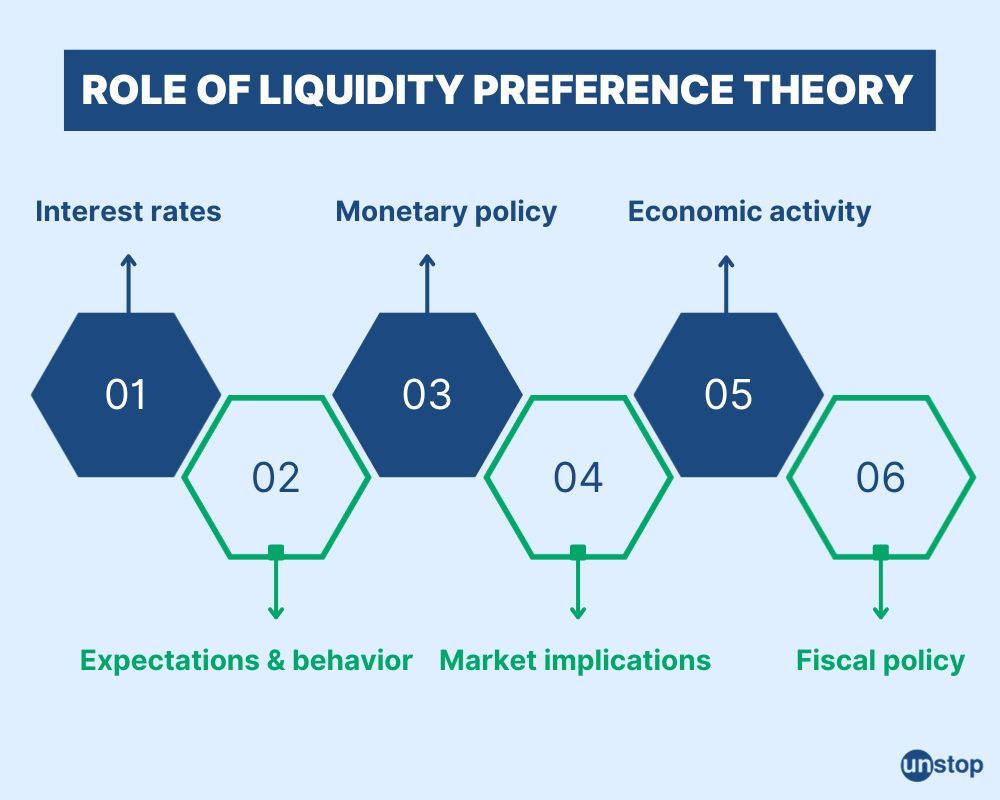
Regulatory capital frameworks remain the weakest component of liquidity policy. Capital absorbs losses. It doesn't provide liquidity. The distinction matters because institutions can be well-capitalized and still fail on liquidity. First Republic Bank had a capital ratio above 10 percent. It failed anyway. The proposed Basel III endgame rules address this partially by linking capital requirements to liquidity risk weights, but the methodology is still contested and the implementation timeline keeps shifting.
What Still Needs To Be Solved
The fundamental unresolved question in liquidity theory is how to price liquidity risk correctly in normal times so that institutions hold enough buffer without being unnecessarily constrained. Current frameworks overbuild during calm periods and underbuild during stress because they're backward-looking. The countercyclical capital buffer helps but only applies to credit risk, not liquidity risk. A symmetric liquidity buffer that accumulates during good times and releases during bad would be more effective, but politically difficult to implement because it raises funding costs when markets are already cheap. Another gap is cross-border liquidity coordination. Capital flows don't respect jurisdictional boundaries. A dollar funding shortage in Europe affects US money market funds, which affects US commercial paper issuance, which affects US corporate borrowing. The IMF's swap line network addresses this partially, but the terms are ad hoc and the eligibility criteria create hierarchy among reserve currencies. Emerging market central banks have proposed alternatives, but none have gained traction against the existing framework. The most practical recommendation I can make, based on years of watching these frameworks succeed and fail, is to treat liquidity risk as a portfolio problem, not an individual institution problem. Stress testing should include correlation assumptions between funding sources, asset classes, and counterparty behaviors. The default assumption should be that correlations approach one during stress, not zero. This alone would change how much liquidity buffer institutions need and make the system more resilient without requiring massive additional regulation.
Policymakers keep looking for elegant solutions. The reality is messier. Liquidity is a behavioral phenomenon as much as a mathematical one. It depends on confidence, on narrative, on what participants believe others will do. No model captures that fully. The best frameworks acknowledge the limitation and build in margins of safety that account for what the models can't see. That's not a failure of theory. It's a feature of reality.