What This Worksheet Actually Is
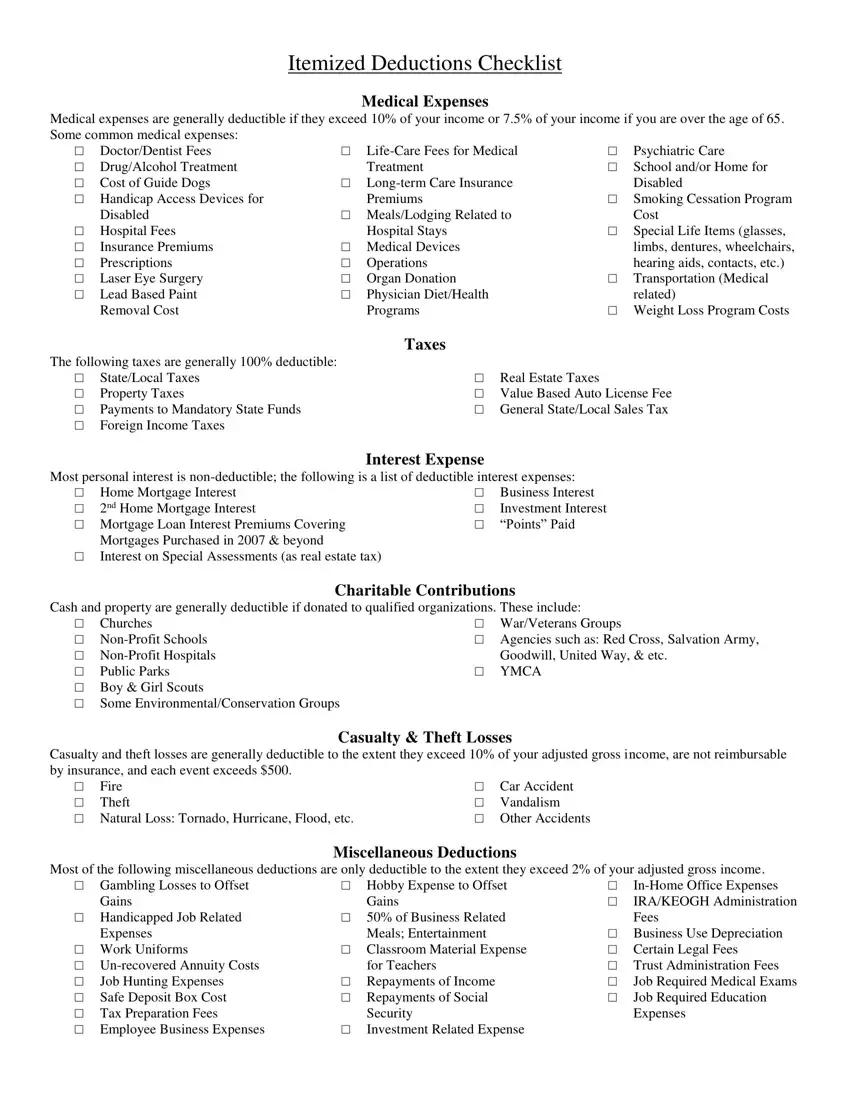
A List Of Itemized Deductions Worksheet is just a tracking document you use to organize the expenses you plan to claim on Schedule A of your Form 1040. You wouldn't see it filed with the IRS. It's something you keep for yourself, usually as a spreadsheet or printed sheet, so you don't lose track of where every number came from when October hits. The IRS doesn't provide an official "worksheet" for this. What exists are tax preparation software templates, third-party PDFs from accounting firms, and the generic schedules built into tools like TurboTax or H&R Block. The worksheet itself is whatever format lets you separate and total your qualifying deductions before they go on the actual return.
List Of Itemized Deductions Worksheet
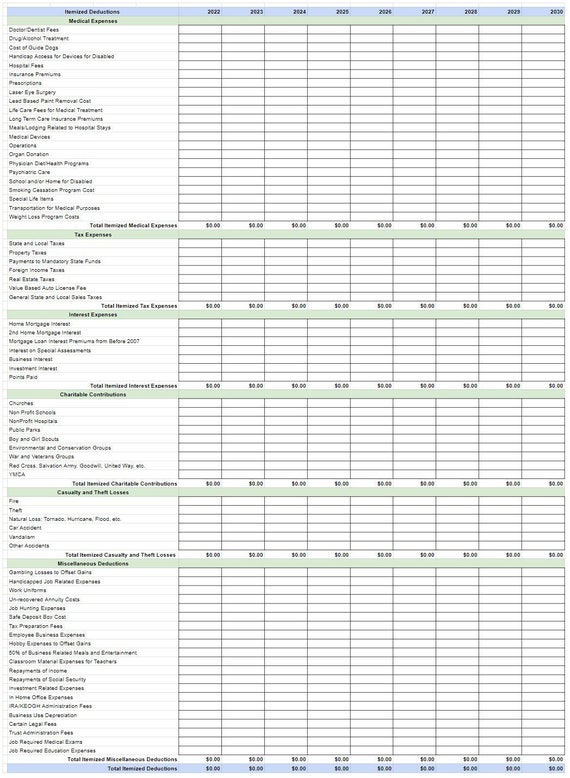
That's the title most people search for when they want something concrete to work from. Below is a practical breakdown of how to build and use one, plus where things tend to go wrong. Start with a simple table. Columns should include: category, description, amount, source document reference, and whether it's subject to any limitation. Rows correspond to the major Schedule A buckets: medical and dental, state and local taxes, mortgage interest, charitable contributions, casualty and theft losses, and miscellaneous deductions (though the latter is mostly suspended through 2025 under the TCJA). I've seen people make the mistake of just listing dollar amounts without noting the source document. That comes back to bite you during an audit or when you're trying to remember why you wrote off $3,412 in mortgage interest in March. Always record the statement date, the institution, and the form number—1098 for mortgage interest, 1099-DSP for charitable distributions, that kind of thing. Five seconds per entry now saves two hours of hunting later.
Keep the worksheet separate from your actual tax forms. Don't try to fill out Schedule A and your tracking sheet at the same time. Write the numbers onto the Schedule A only after they've been cross-checked against the original documents. This habit alone prevented me from accidentally double-counting a charitable cash contribution once. I had written it down on a receipt and then also on a bank statement, totaling it twice in my head. The worksheet caught it because I was forced to mark each item as "verified" against a source before moving on.
Get the Full Details

The Categories And What Actually Qualifies
Medical and dental expenses go here only to the extent they exceed 7.5% of your adjusted gross income. This is the part people consistently mess up. They total every medical cost they can find and forget to subtract that threshold. If your AGI is $90,000, that's $6,750 you have to exceed before anything counts. I once had a client who brought in $14,000 in medical receipts and was devastated to learn only about $2,500 of it was deductible. The worksheet needs a line at the bottom for the AGI floor calculation so you see the real number immediately. State and local taxes are capped at $10,000 combined for real estate, income, and sales taxes. You can't beat the cap by filing separately with your spouse and each claiming $10,000. That restriction is real. The worksheet should have a clear subtotal for SALT with the cap called out so you know when you've hit the limit mid-year rather than discovering it at filing time. Mortgage interest is generally straightforward if you only have one loan. Secondary homes, refinances, and home equity loans introduce nuance. Interest on home equity debt is only deductible if the funds were used to buy, build, or substantially improve the home. That distinction matters and most people ignore it until they're three years into ownership with a HELOC they used for a kitchen renovation. Put the loan purpose in your worksheet notes.
Charitable contributions require documentation for anything over $250. A text message screenshot isn't enough. You need a cancelled check, a bank statement, or a written acknowledgment from the charity. The worksheet should have a column flagging whether you have proper documentation on file. I learned this the hard way when the IRS disallowed a $500 donation because I only had a credit card statement without the charity's name clearly printed. The worksheet would have flagged that gap before I ever filed. Casualty and theft losses are only deductible now if they occur in a federally declared disaster area. This changed significantly after the TCJA and it's a trap for people who still think any random home damage qualifies. If you have a qualifying loss, the worksheet needs to capture the adjusted basis, insurance reimbursements, and the $100 per-event reduction before the 10% AGI threshold applies.
A Few Things Nobody Tells You
The standard deduction changed dramatically with the TCJA. For 2024, it's $14,600 for single filers and $29,200 for married filing jointly. For 2025, it's $14,800 and $29,600 respectively. Your itemized deductions need to meaningfully exceed these amounts before the exercise is worth the effort. A lot of taxpayers who itemize out of habit are leaving money on the table by taking the standard deduction instead. Charitable non-cash contributions over $500 require Form 8283. Over $5,000 per item requires a qualified appraisal. The worksheet should include a column for whether Form 8283 is needed so you don't miss that requirement until after you've already filed. Giving appreciated stock to charity is more efficient than donating cash. You deduct the fair market value and avoid capital gains tax on the appreciation. Most people don't know this and just sell the stock, pay the tax, and donate the proceeds. If you hold appreciated securities, the worksheet should have a separate section for non-cash contributions with a note about the tax advantage.
When The Worksheet Breaks Down
Spreadsheets are fragile. If you use Excel or Google Sheets and the formulas break, you're left with a pile of numbers and no way to verify the totals. I've recovered corrupted spreadsheets where a single misplaced cell reference caused the medical expense threshold calculation to be wrong by several thousand dollars. Use simple addition formulas where possible. Avoid complex conditional logic unless you understand exactly how it works. Test your sheet with known numbers before relying on it for your actual return. If your situation is complex—multiple properties, business use of home, significant non-cash donations, or a mix of state and local tax situations—the worksheet approach might not be enough. In those cases, a CPA or enrolled agent who uses professional tax software will catch more edge cases than a self-made tracking sheet ever could. The worksheet is fine for straightforward itemization. It's not a substitute for professional help when your situation has multiple moving parts. Another limitation: the worksheet doesn't protect you from documentation requirements. It tracks your numbers but it doesn't store your receipts. You still need to keep all source documents for at least three years from the filing date, or longer if you're claiming a theft loss or bad debt deduction. Consider scanning everything and storing it in a dedicated folder structure that mirrors your worksheet categories. This removes the physical hunt from the process entirely.
Where To Get A Ready-Made Version
The IRS doesn't publish a ready-made List Of Itemized Deductions Worksheet. You'll find free templates on sites like the IRS.gov download center under Schedule A instructions, along with various accounting firm websites that offer them as lead magnets. Many tax preparation platforms include one automatically when you switch from the standard deduction to itemizing. If you want a printable PDF you can fill out by hand, search for "Schedule A worksheet printable" and you'll find several options from reputable tax resource sites. Just verify the template matches the current tax year. The rules for charitable contributions and SALT caps have shifted enough in recent years that using a 2021 worksheet for a 2024 return will give you incorrect numbers. Check the publication year on any template before you invest time in it.