The PMT Function Is Only The Beginning
Building a proper Loan Amortization Calculator Excel tool requires more than dropping a PMT formula into a cell and calling it a day. Anyone who has tried to replicate an actual bank statement in spreadsheets knows this quickly. The simple payment amount is only the most visible piece. The real complexity sits underneath, in how each payment splits between interest and principal over time. I built my first version roughly ten years ago because a client needed to compare two mortgage offers side by side, and every calculator online assumed a 30-year fixed loan with no extras. It took me about three hours to get something functional, and another six to make it actually handle the edge cases. Most people don't need that depth, but if you're going to build something yourself, you should understand where the common failure points are.
Loan Amortization Calculator Excel: Core Structure
The skeleton of any amortization schedule is straightforward. You need five input cells and a repeating table. The inputs are the loan amount, the annual interest rate, the loan term in years, the payment frequency, and optionally whether payments occur at the beginning or end of each period. Everything else derives from those. Here is how the standard calculation actually works in practice: Monthly payment formula: =PMT(rate/nper,pv,[fv],[type])
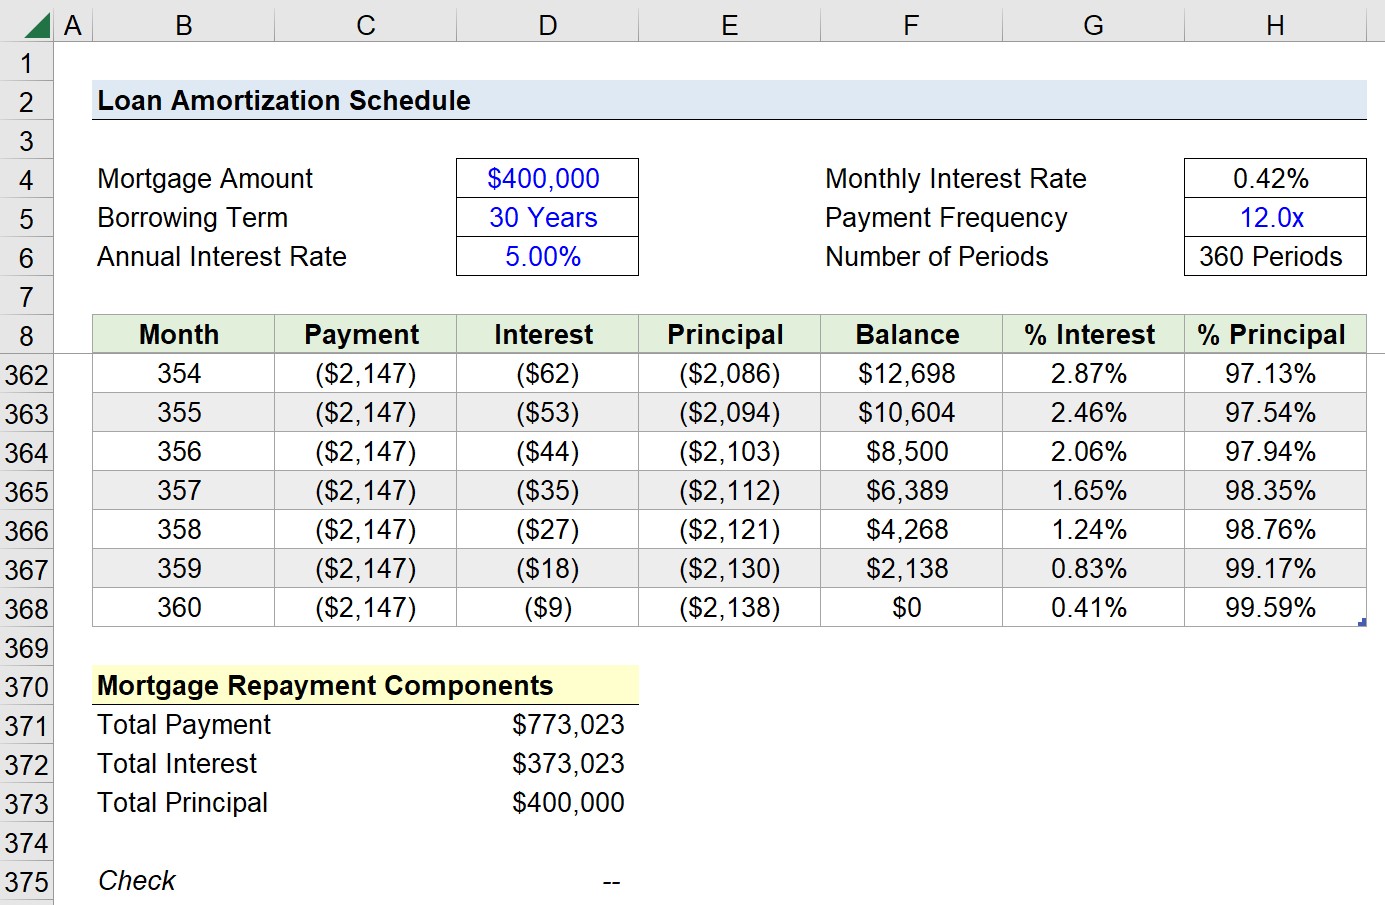
Where rate is the annual rate divided by periods per year, nper is the total number of payments, pv is the present value or loan amount entered as a negative number so the result is positive, and type is 1 for beginning-of-period payments or 0 for end-of-period. The parentheses around fv and type indicate they are optional, but skipping them will silently assume zero future value and end-of-period payments, which is wrong for many loan types. The amortization table then repeats this pattern for every period. Each row calculates the interest portion as the remaining balance multiplied by the periodic rate. The principal portion is the total payment minus that interest amount. The new balance is the old balance minus the principal paid. This creates a curve where interest dominates early payments and principal dominates later ones, which is exactly how every standard amortizing loan works. A typical twelve-row structure looks like this when laid out across columns:
Get the Full Details

Column A: Period number Column B: Payment amount (usually constant for fixed loans) Column C: Interest portion
Column D: Principal portion Column E: Remaining balance Column F: Cumulative interest paid to date
The interest formula in row 3 would be =E2*$B$1/$B$2, assuming the rate is in B1 and periods per year in B2, and the previous balance is in E2. The principal portion in column D is simply =B3-C3. The remaining balance in E3 is =E2-D3. Copy those down for the full term and the schedule builds itself. This is the basic version. It handles standard fixed-rate loans cleanly. But real loans are messier than textbook examples, and that is where most online tutorials stop and leave you stranded.

Where People Actually Get Stuck
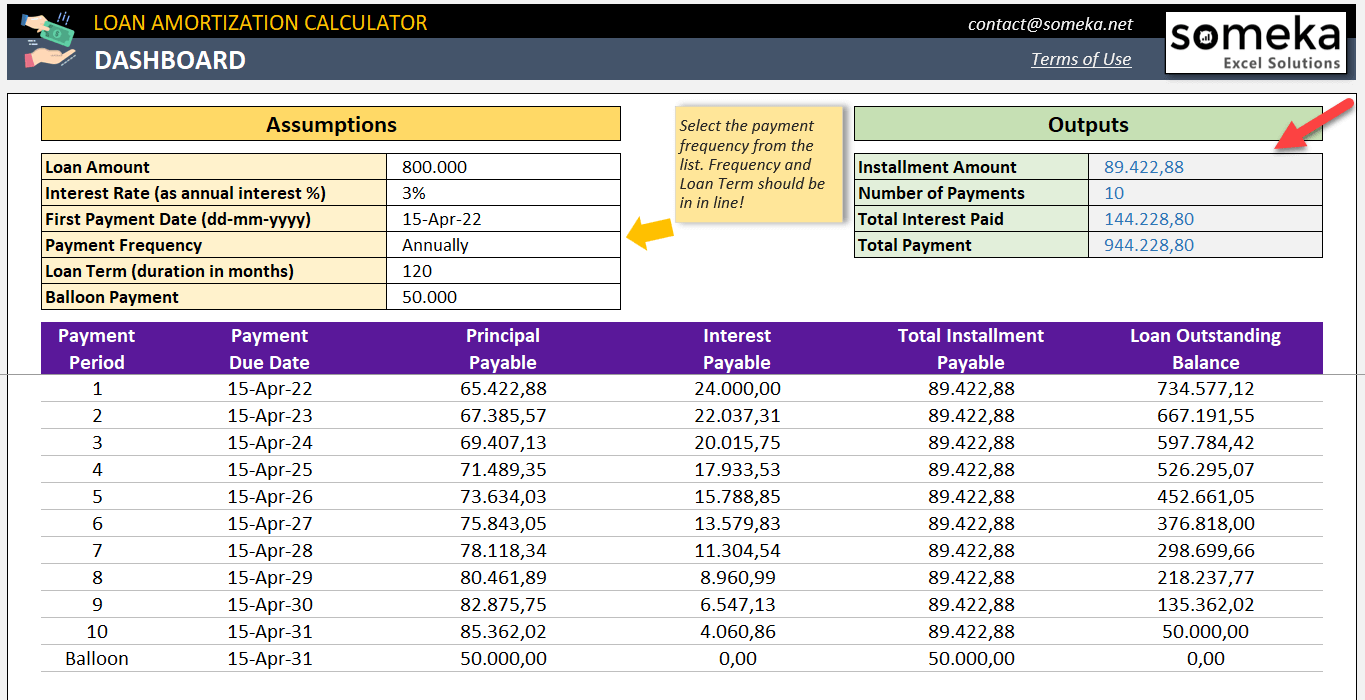
The first problem that trips people up is leap years and irregular payment dates. If your loan starts on January 15 and you make monthly payments, the payment dates shift through the calendar year. Excel's standard PMT function does not account for this. It assumes perfectly equal periods. For residential mortgages this matters less because servicers often smooth it out, but for commercial loans and auto financing it can throw off your entire schedule by several hundred dollars over the life of the loan. The second problem is down payments and closing costs buried in the loan amount. If the purchase price is 300,000 and the buyer puts 20 percent down, your present value input should be 240,000, not 300,000. I see this mistake constantly in templates shared on forums. The down payment is ignored and the calculator compounds interest on money the borrower never actually received. The third issue is balloon payments. A Loan Amortization Calculator Excel setup that assumes the balance reaches zero at the end of the term will give you wildly incorrect results for a balloon loan. You have to adjust the future value parameter or manually truncate the schedule and add the balloon payment as a separate line item.
Here is a specific example from my own work that I still think about. A client asked me to model a $185,000 loan at 6.75 percent over 30 years with monthly payments. The standard PMT function gave a payment of about 1,199 dollars. They verified it against their bank statement and found a discrepancy of about fourteen dollars per month. The issue was that their bank uses a 360-day year for interest calculations, not the actual 365-day calendar. The PMT function in Excel calculates based on actual period counts, not day-count conventions. Switching to a day-count-aware custom calculation brought the numbers within a few cents of the bank statement. This is the kind of thing that does not appear in any basic tutorial.
Advanced Nuances Most Beginners Miss
One counter-intuitive detail is how the type parameter actually affects the payment. Setting type to 1 (beginning of period) reduces the payment amount because each payment earns one extra period of interest reduction. The difference seems small on paper but on a 30-year loan it can save thousands in total interest. Most people never check this setting and assume it defaults to something sensible. It defaults to zero, which means end-of-period, which is correct for mortgages but wrong for leases and some rent structures. Another nuance is the difference between nominal and effective annual rates. If your loan document states an annual percentage rate of 5 percent but compounding is monthly, the periodic rate is 5 percent divided by 12, not the effective monthly rate derived from (1.05)^(1/12) minus 1. The nominal approach is standard for consumer loans in the United States, but some international products use effective rates, and plugging the wrong one into PMT will skew every number in your schedule. Prepayment behavior is the third area where basic calculators fail. Once a borrower makes an extra payment, the entire schedule shifts. The next period's interest calculation changes because the balance is lower. A static Loan Amortization Calculator Excel template cannot handle this without restructuring. The workaround is to build a dynamic table where the balance column references the previous row rather than using a fixed sequence. When you enter an extra principal payment in a given row, all subsequent rows automatically recalculate with the new lower balance.
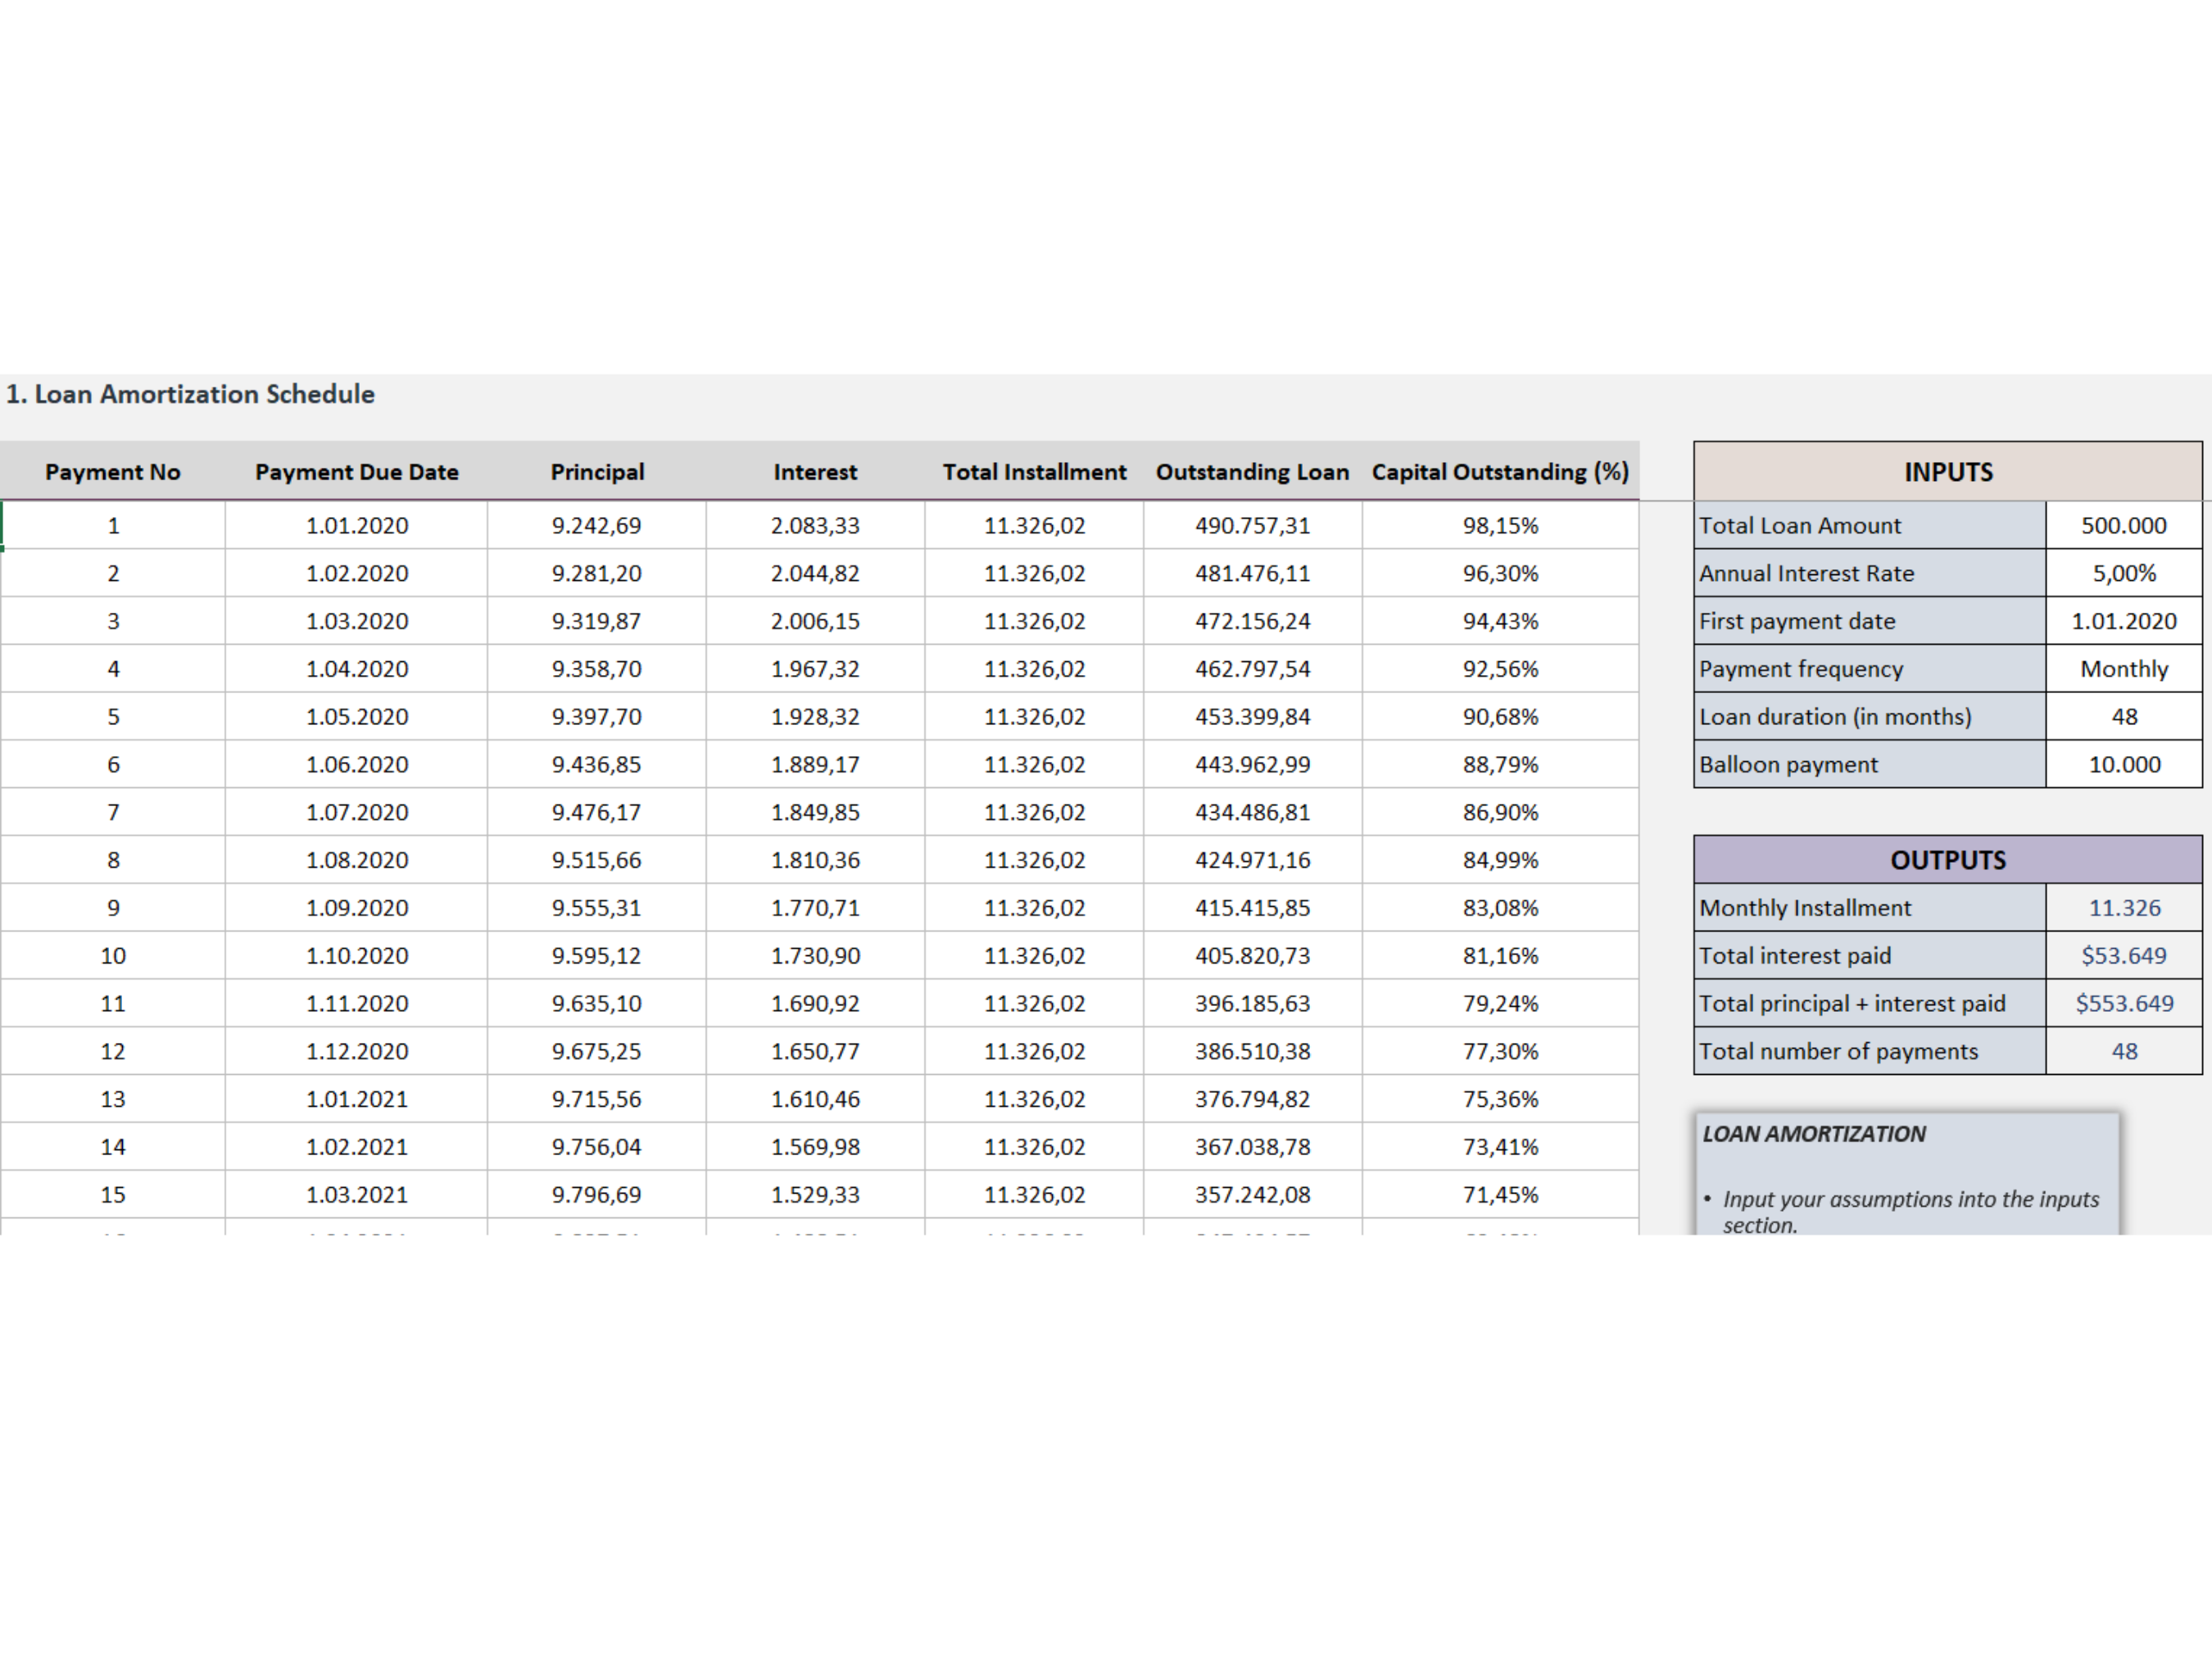
Here is how that looks in practice. Instead of hardcoding the period count, you use a formula like =IF(E3
=0,"",E3-D4) for the balance column with an IF statement that stops generating rows once the balance hits zero. Add a separate input cell for extra principal payments per period, link that into the principal paid calculation, and let the remaining balance cascade. This single change turns a static 360-row table into a responsive model that adjusts to whatever payment pattern the borrower actually follows.
Practical Implementation Notes
If you are building this from scratch, start with the inputs section at the top of your sheet. Label each cell clearly. Use data validation to restrict the payment frequency dropdown to monthly, biweekly, semi-monthly, and quarterly. Biweekly payments are common enough that ignoring them leaves a real gap. The PMT formula adjusts automatically if you divide the annual rate by 26 and multiply the term by 26, but the total interest savings from biweekly payments is not the same as making half a monthly payment every two weeks due to the extra payment that occurs in most years. This is a detail most calculators miss and it matters for honest comparisons. For formatting, keep the schedule table clean. Use conditional formatting to highlight any row where the extra payment exceeds zero. Freeze the top rows so the headers stay visible when scrolling through a 360-period schedule. Add a summary section at the bottom that shows total interest paid, total amount paid, and the effective annual cost including any upfront fees if you are tracking those separately. One more thing about scaling. If you need to model multiple loans simultaneously, do not duplicate the entire table. Build one master calculator and use indirect references or a lookup structure to pull different input sets into the same calculation engine. This keeps your file from becoming unmanageable and makes updates trivial. I learned this the hard way when a client asked me to compare fifteen different loan scenarios and I had built fifteen separate sheets instead of one flexible model.
When Excel Is The Wrong Tool
A Loan Amortization Calculator Excel works well for standard fixed-rate loans, basic adjustable-rate mortgages, and simple auto or personal loans. It breaks down when you need to model complex commercial structures with tiered interest rates, irregular payment dates across multiple currencies, or loans with embedded options like prepayment penalties that vary by year. For those scenarios, a dedicated loan modeling platform or a database-driven solution is more appropriate. Spreadsheet models become fragile past a certain complexity threshold because every manual adjustment introduces the risk of a broken reference. The main bottleneck with any spreadsheet-based amortization tool is transparency versus flexibility. You can see every calculation step, which is excellent for auditability, but you also have to maintain every formula yourself. A commercial loan calculator service handles the edge cases and updates automatically when regulations change. Building the equivalent in Excel requires ongoing maintenance and a solid grasp of financial mathematics to avoid subtle errors that look correct on the surface. For most personal finance purposes, a well-built spreadsheet is sufficient. Just make sure you test it against a known output before relying on it. Pull a sample amortization schedule from your bank or lender, enter the same parameters into your calculator, and verify that the numbers match to within a reasonable rounding margin. If they do not, trace through the interest calculation formulas row by row until you find where the divergence starts. That process usually reveals whether the issue is a rate convention, a day-count assumption, or a simple cell reference error.