Why Most People Build Their Own Amortization Schedules (And Why They Shouldn't)
I've spent years reviewing loan documents for investment properties, and the single most common mistake I see isn't in the interest rate calculation or the term length. It's in how people present their amortization data. A sloppy spreadsheet with inconsistent formatting gets flagged faster than one with slightly off numbers. The numbers can be right, but if the table looks amateur, lenders and investors will assume the worst. This is why having a proper Loan Amortization Table Template matters. Not because the math is hard — it's not — but because the template does the heavy lifting on clarity, consistency, and trust. When someone hands you a clean schedule that tracks principal, interest, remaining balance, and cumulative payments across every period, they're saying something about their professionalism without writing a word.
The Core Structure of a Loan Amortization Table Template
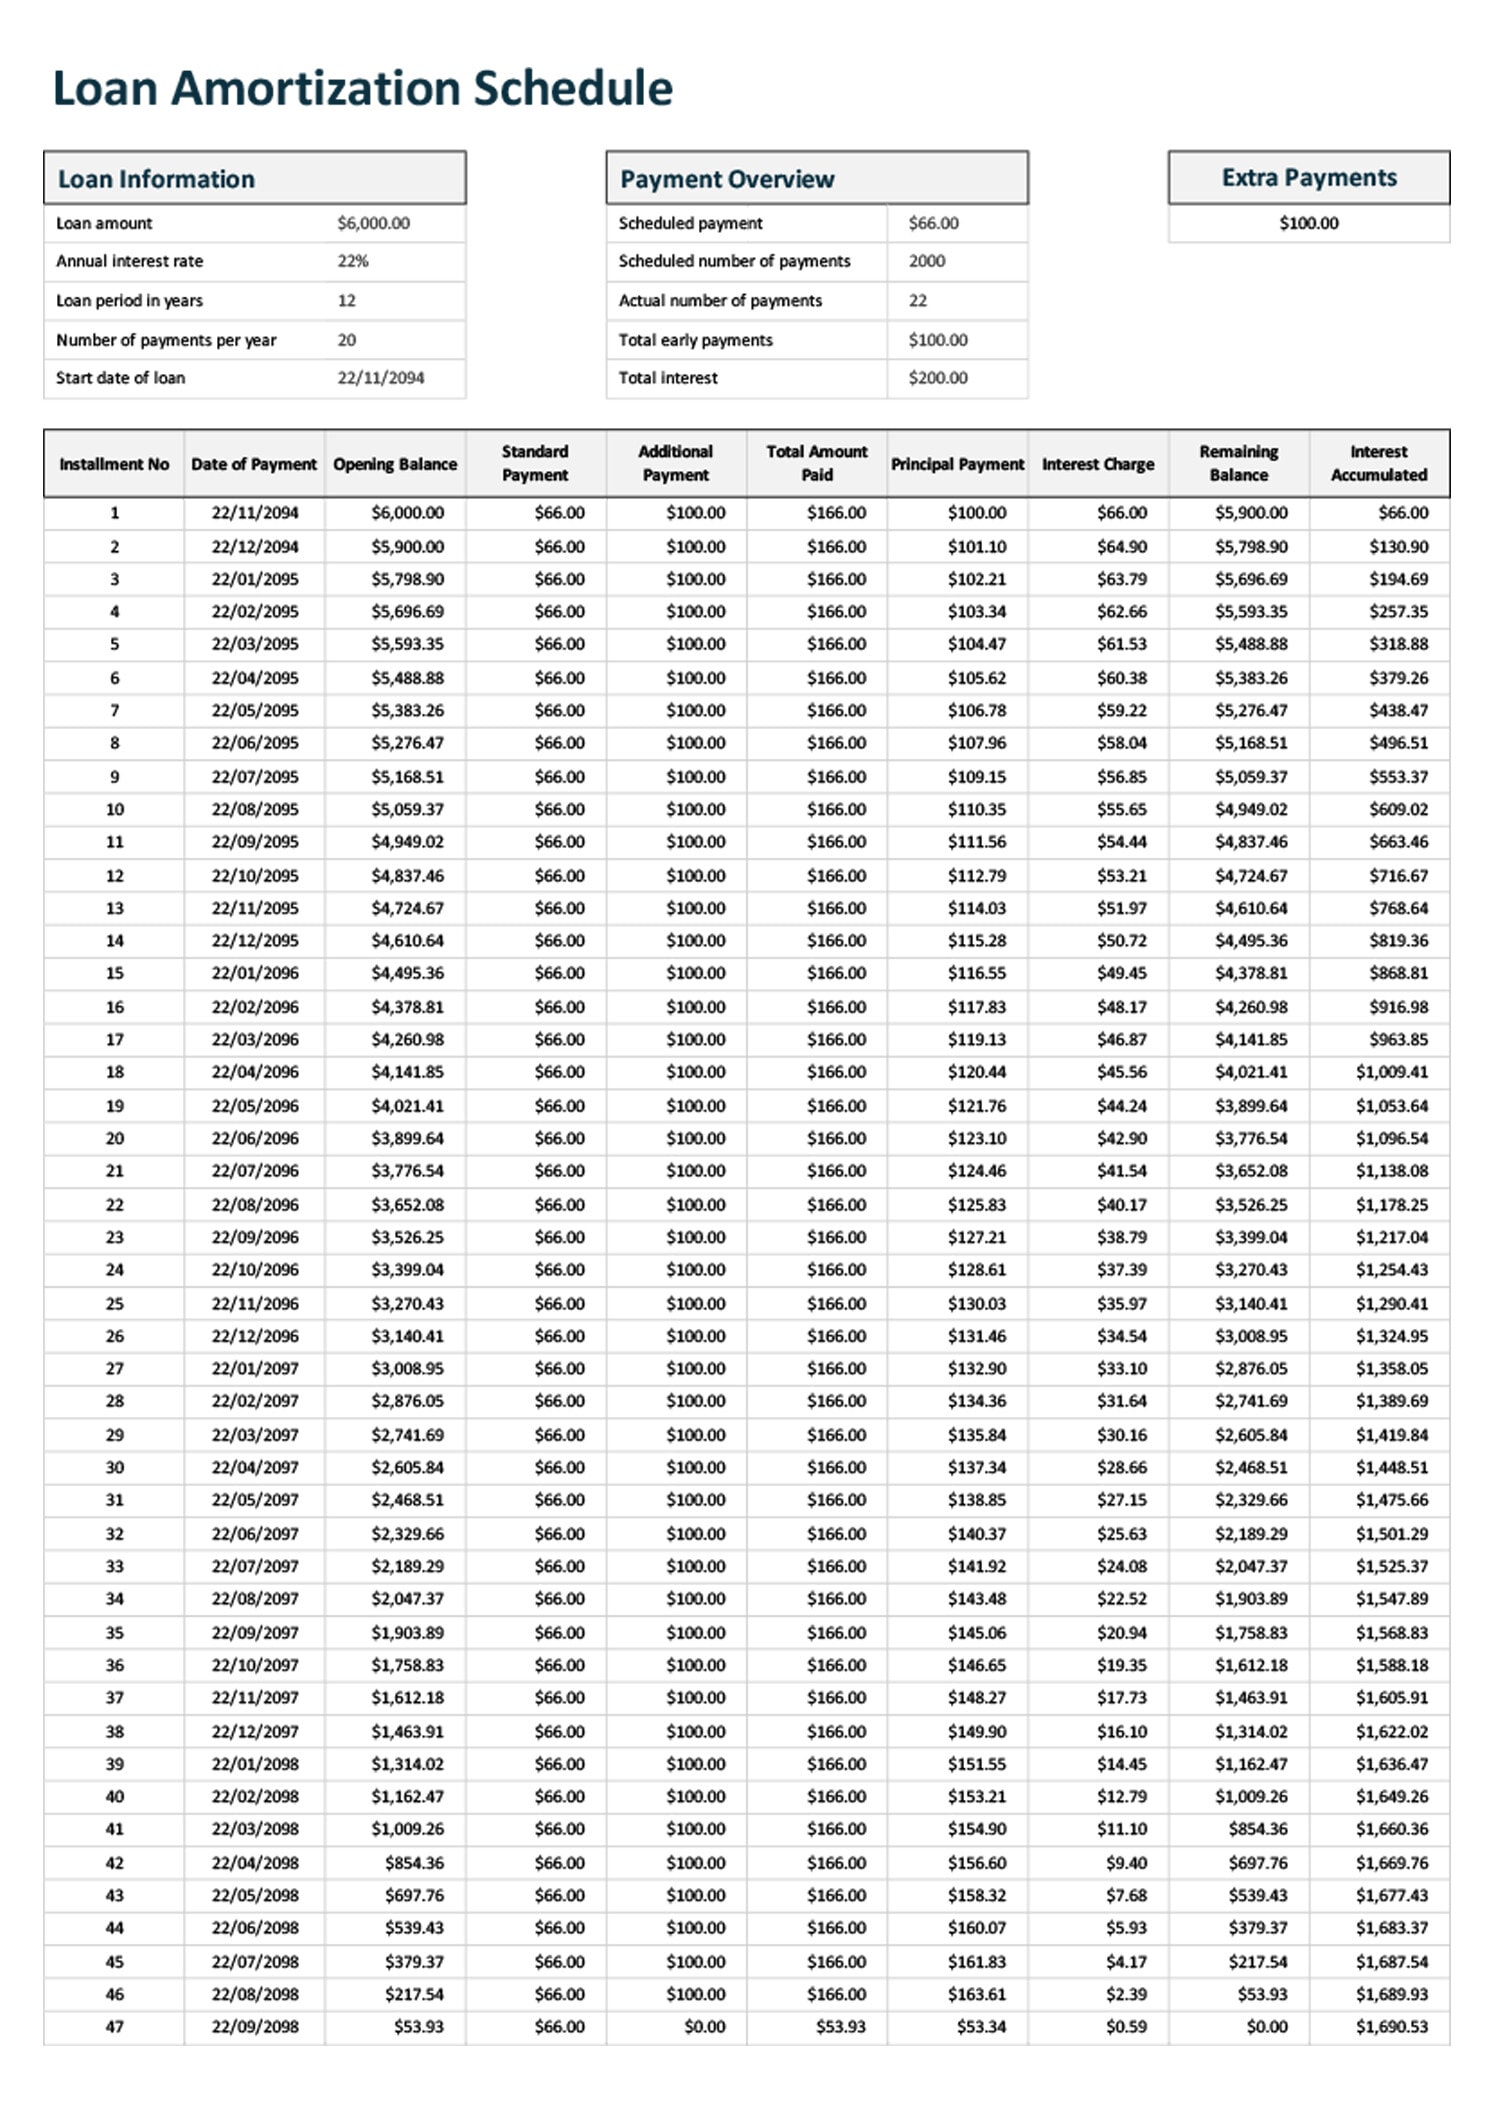
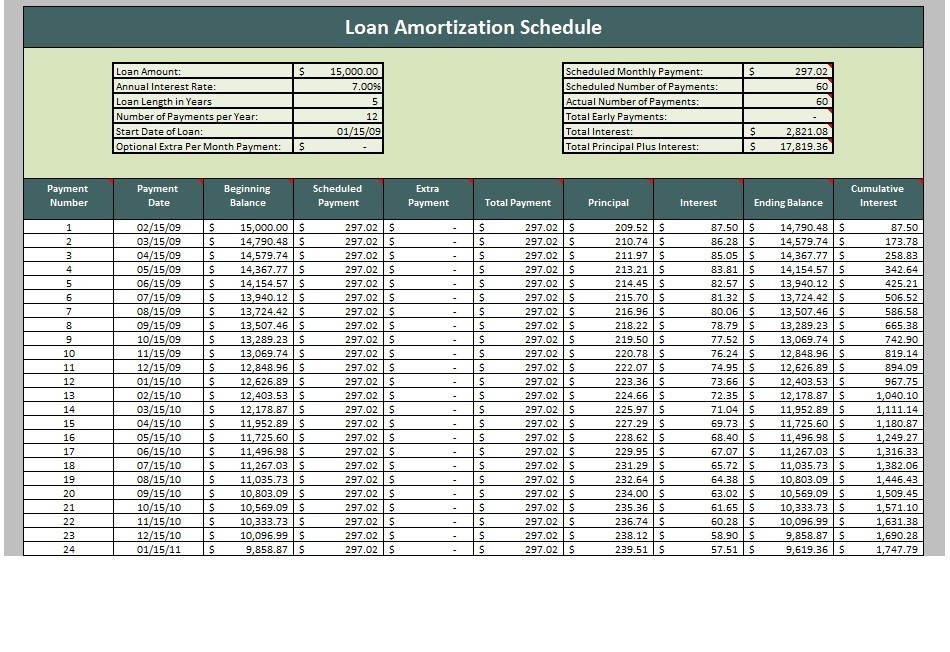
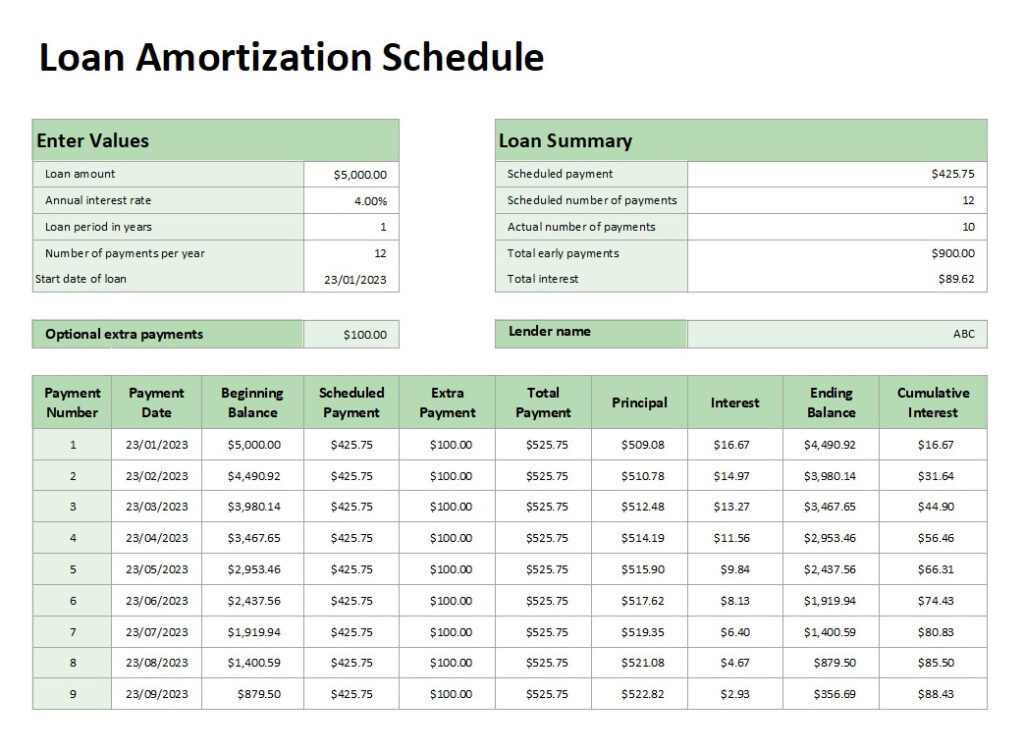
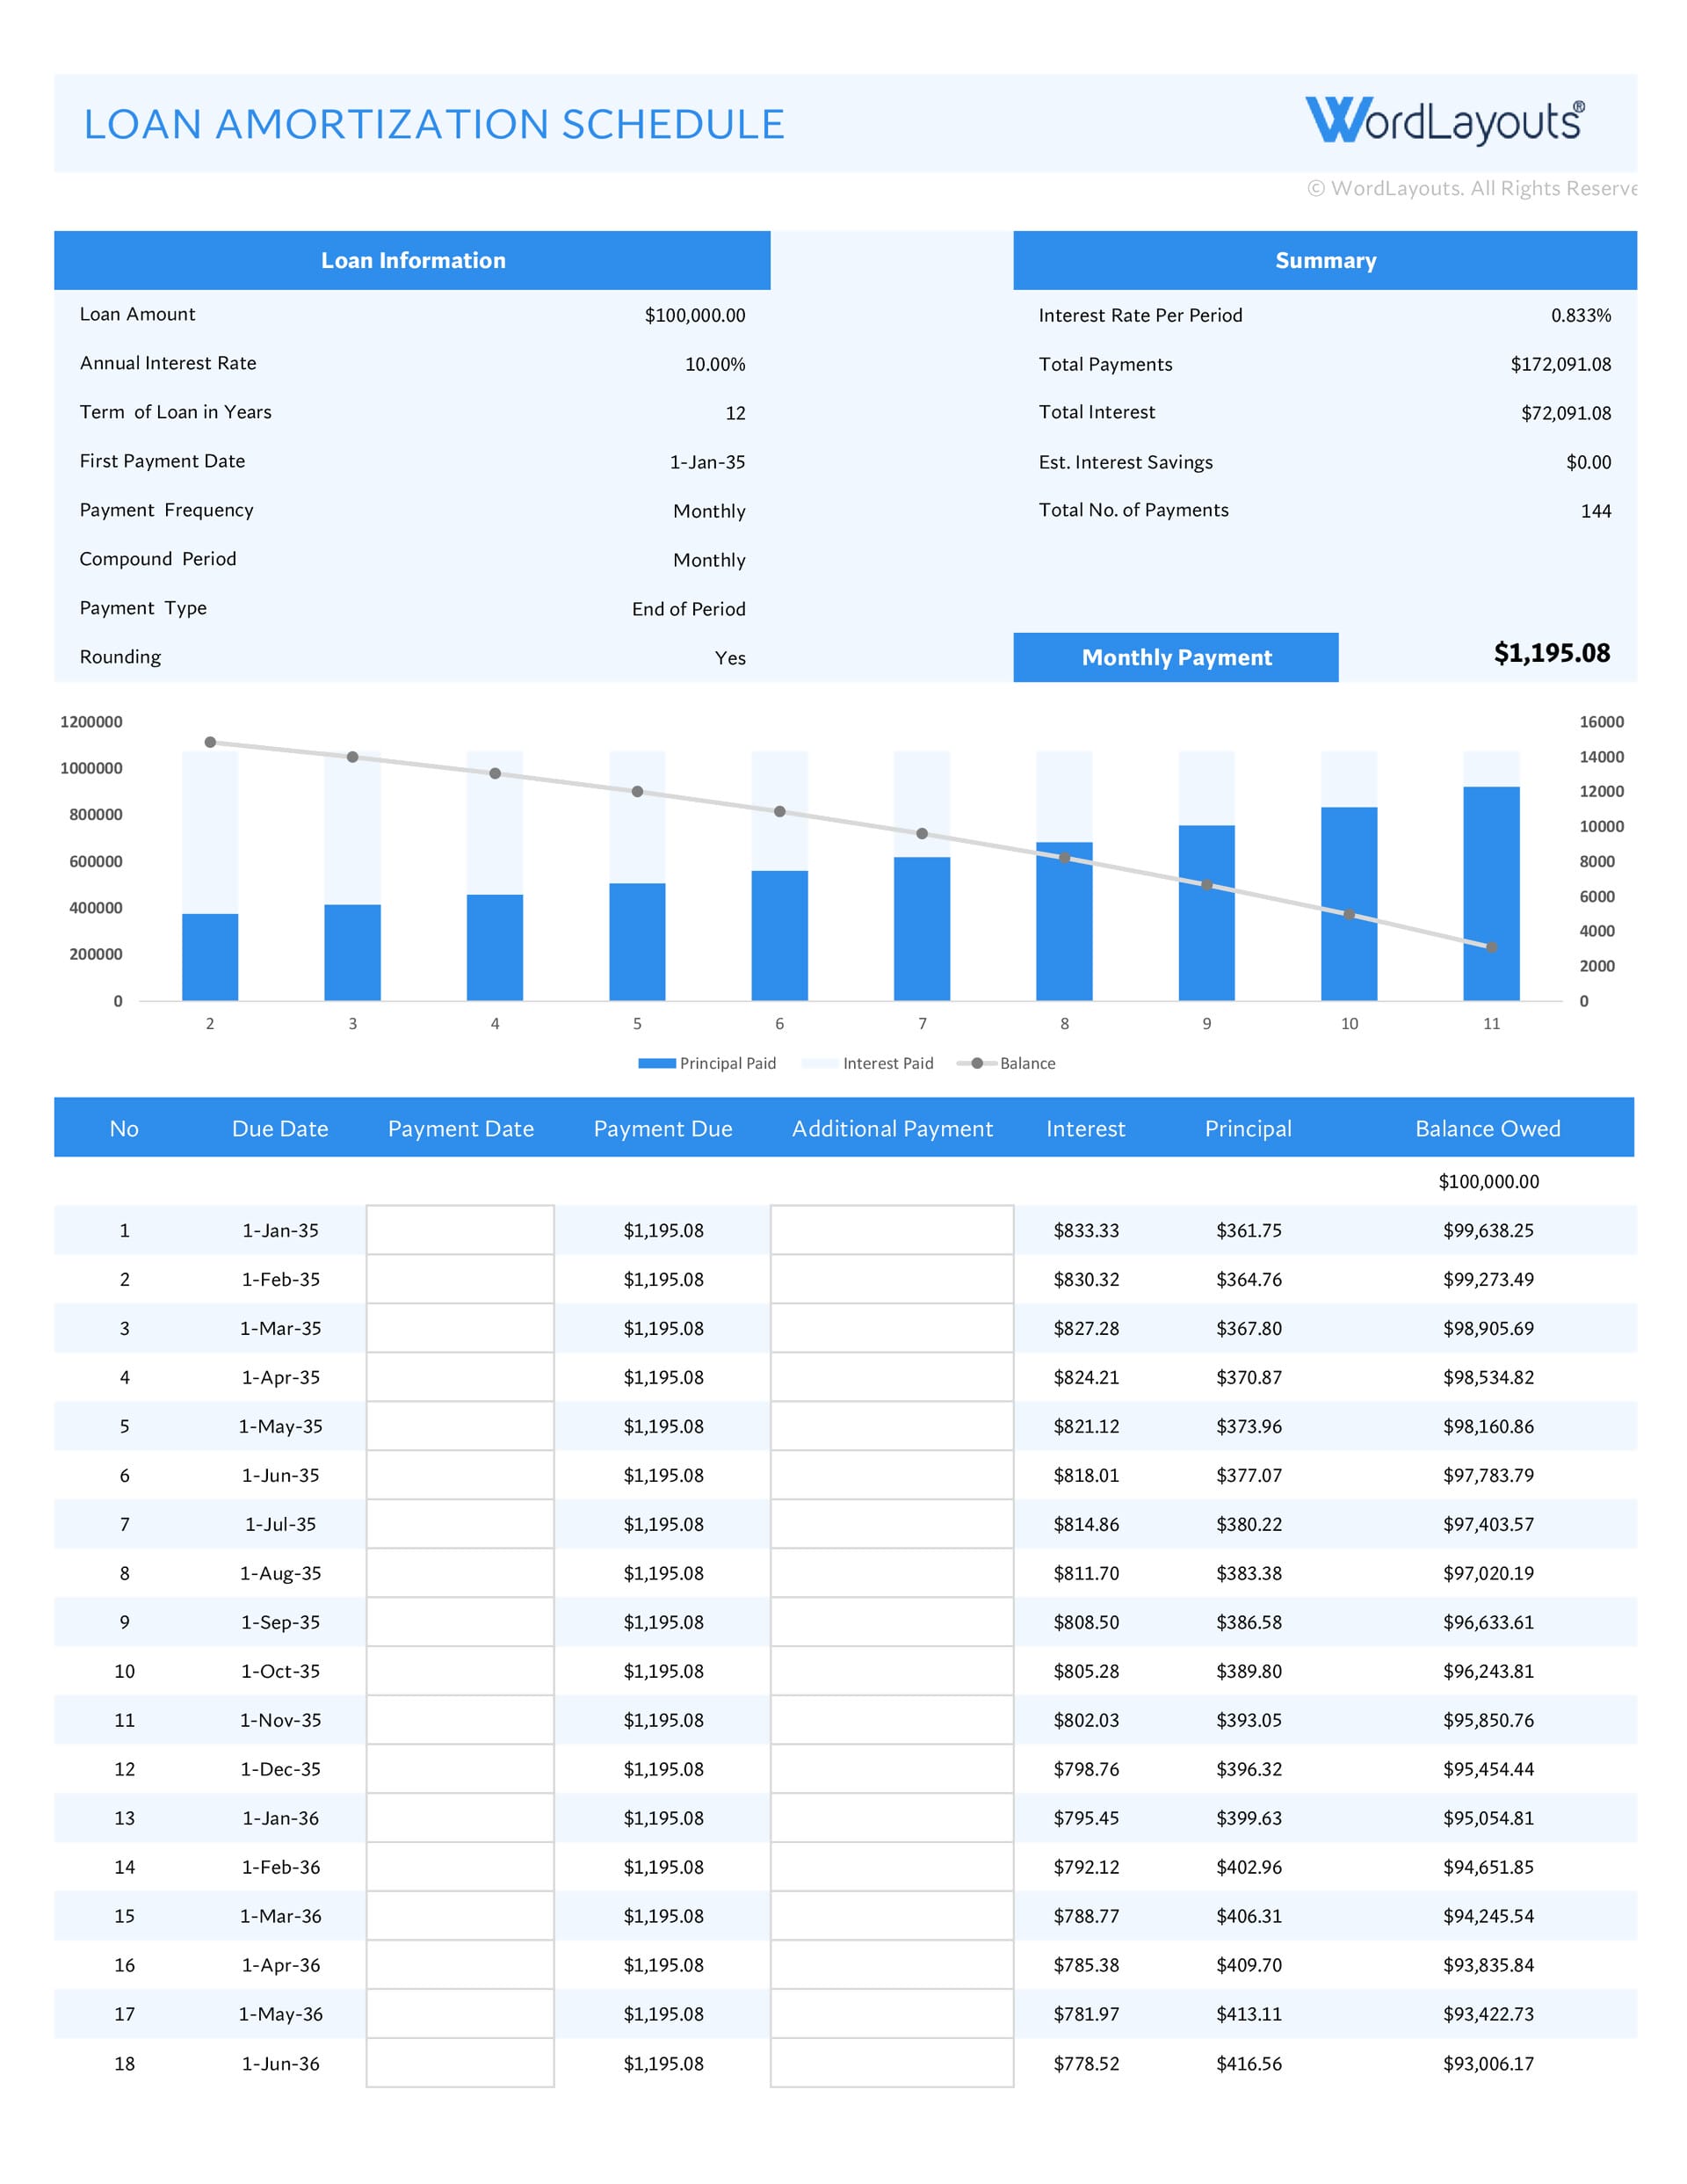
At its most basic level, an amortization table has five essential columns: the payment period number, the total payment amount, the principal portion, the interest portion, and the remaining balance after each payment. That's it. The standard formula that drives it all is the annuity payment formula: M = P × [r(1+r)^n] / [(1+r)^n 1], where M is the monthly payment, P is the principal, r is the monthly interest rate, and n is the total number of payments. But the real trick isn't the formula. It's what happens after. Take a $350,000 loan at 6.75% annual rate over 30 years. Your monthly payment works out to about $2,271.41. In month one, the interest portion is $1,968.75 and the principal portion is only $302.66. By month 360, you're paying almost nothing in interest. Most people don't realize how lopsided that distribution is until they see it laid out column by column. That's the whole point of the exercise. The template forces you to see the structure of your debt, not just the monthly number.
How I Build My Templates (And What I Learned the Hard Way)
I use Excel for most of my work. It's fast, it's familiar, and it lets me build conditional formatting that highlights when a balloon payment is approaching or when the principal portion finally overtakes the interest portion. Here's the practical setup I use: Column A: Payment number (1 through n). Column B: Payment date (auto-fills by adding months to the start date). Column C: Beginning balance. Column D: Total payment (absolute reference to the calculated monthly payment cell). Column E: Interest payment (beginning balance times monthly rate). Column F: Principal payment (total payment minus interest). Column G: Ending balance (beginning balance minus principal payment). Column H: Cumulative principal paid. Column I: Cumulative interest paid. The formula in Column E, for example, is simply =C5*$G$1/12, where $G$1 holds the annual rate in a locked cell. The ending balance in G5 is =C5-F5, and the beginning balance in C6 is =G5, creating a chain that references itself down the entire sheet. This self-referencing chain is what makes the whole thing automatic. Change the loan amount or rate at the top, and everything below recalculates.
Get the Full Details
Here's the edge case that cost me three hours once: a borrower had an adjustable-rate loan with a cap of 2% per adjustment, and the rate changed at payment 48, 120, and 240. My original template assumed a fixed rate throughout, so the schedule broke at period 48 — the balance values became meaningless because the payment amount was still calculated from the original rate. The workaround was to add a separate section in the template where I could input rate change dates and new rates, then use IF statements to switch between payment calculations. I ended up building a hybrid model that had one set of formulas running through the first cap date, then recalculated the payment for the new rate and continued the balance chain. It's a bit more complex, but once it was built, it saved me from doing the whole table by hand for every adjustment scenario. That experience is why I now always include a small, clearly labeled input area at the top of any Loan Amortization Table Template I produce. Rate changes, extra payments, payment holidays — anything that deviates from the standard model goes in that input area, and the formulas below react to it.
The Counter-Intuitive Things No One Tells You About Amortization Schedules
First, the order of the columns matters for how quickly you can spot problems. I used to put the payment date first because it felt chronological. What I found was that putting the beginning balance first lets you scan down the column and immediately see where the big shifts happen — balloon payments, rate resets, or periods where you've made no progress on the principal. It takes getting used to, but it cuts review time significantly. Second, most people don't realize that an amortization schedule is fundamentally a liability, not an asset. When you're valuing a property for purchase, the schedule on the existing loan tells you something very specific: how much equity you're actually buying into. A $400,000 property with a $320,000 loan balance sounds like 20% equity. But if that loan has been amortizing for two years, the actual remaining balance might be $308,000. The difference is the difference between breaking even and walking away with a profit. I've seen deals fall apart because the buyer looked at the original loan amount instead of the current balance from the schedule. Third, and this is the one that trips up everyone: the total interest paid over the life of the loan is almost never the number people expect. For a $350,000 loan at 6.75% over 30 years, the total interest comes to roughly $467,000. That's 133% of the principal. People hear "6.75% interest rate" and think they're paying 6.75% on the full amount every year. They're not. They're paying 6.75% on the declining balance. The total cost is brutal precisely because the balance stays high for so long.
Common Pitfalls in Amortization Templates
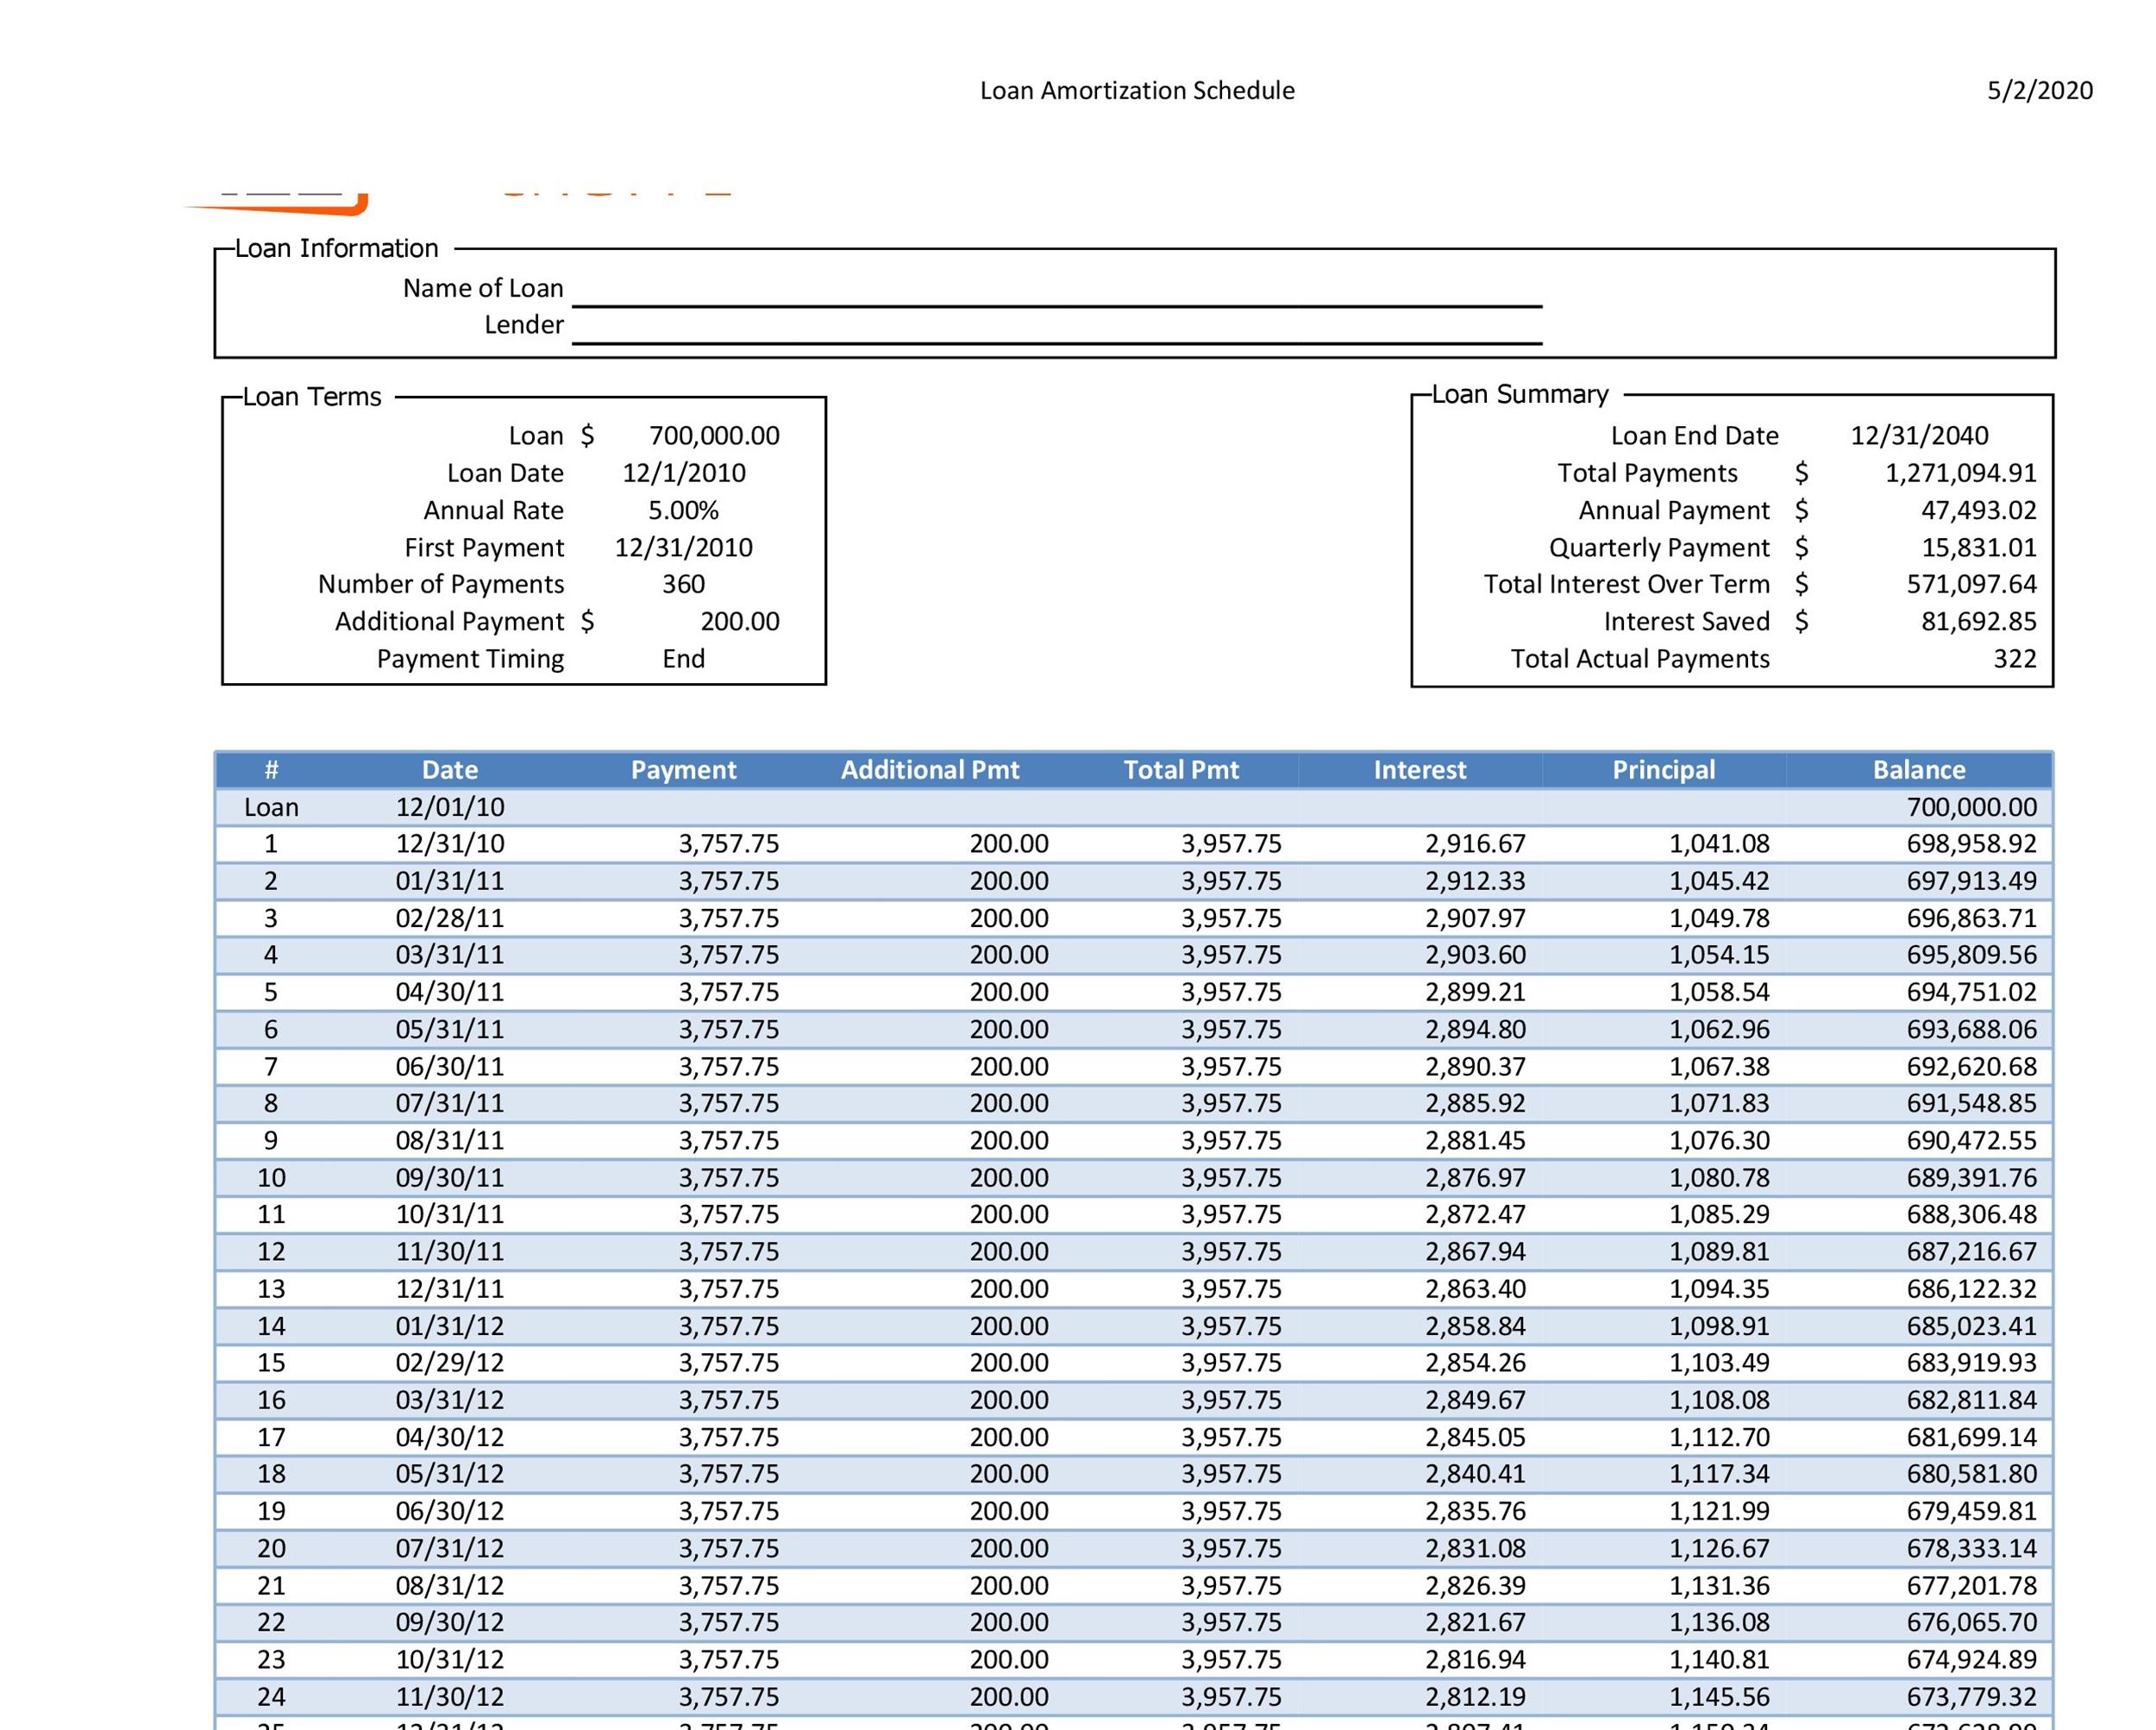
The most frequent error I encounter is the leap year problem. February has 28 days normally and 29 in leap years, which shifts every subsequent payment date by one day. For most residential loans, this doesn't matter because payments are monthly and the bank absorbs the variance. For commercial loans with daily interest accrual, it matters enormously. I've seen schedules where the accrued interest for a given period was off by nearly two days' worth of interest because the template treated every month as 30 days. The fix is straightforward: use a date-based calculation rather than a period count. Let the actual calendar drive the accruals. Another common trap is rounding. If you round each monthly payment to the nearest cent and then recalculate the balance from that rounded figure, the final payment won't zero out the loan. You'll have a penny or two left. The proper approach is to keep all intermediate calculations at full precision and only round the display values. Excel does this by default if you set your cells to show two decimal places without actually rounding the stored value. Check your cell formatting, not just your formulas. A third issue is prepayment. If the borrower makes an extra payment in month 12, the standard template doesn't account for it unless you manually adjust the balance going forward. I've built a version where you can input lump-sum payments in a separate table, and the main schedule picks them up automatically. The formula uses a VLOOKUP to match the payment date against the extra payment table, and if there's a match, it subtracts that amount from the principal before calculating the next period's interest.
When a Template Won't Cut It
Not every situation fits neatly into a standard amortization schedule. I've worked with interest-only loans where payments are flat for the first decade and then jump to a fully amortizing amount. These require a split-template approach where the first section shows the interest-only payments and the second section recalculates based on the remaining term and the outstanding balance at the switch date. Building these in a single sheet gets messy fast. Graduated payment mortgages are another case where templates struggle. The payments increase at set intervals according to a predefined schedule, which means you can't use the standard annuity formula for the entire term. You'd need to calculate separate payment amounts for each phase and chain the balances together manually. It's doable but time-consuming, and one wrong linkage will throw the whole table off by thousands. For these more complex products, specialized loan servicing software is the better option. Tools like Yardi, RealPage, or even Excel-based financial calculators from Bloomberg Terminal handle these edge cases without you having to build the logic yourself. The tradeoff is cost and learning curve. If you're only dealing with a handful of standard fixed-rate or adjustable-rate loans, a well-built template is faster and cheaper. If you're managing a portfolio with mixed loan types, the investment in proper software pays for itself within a few months.
What I'd Change About My Own Templates
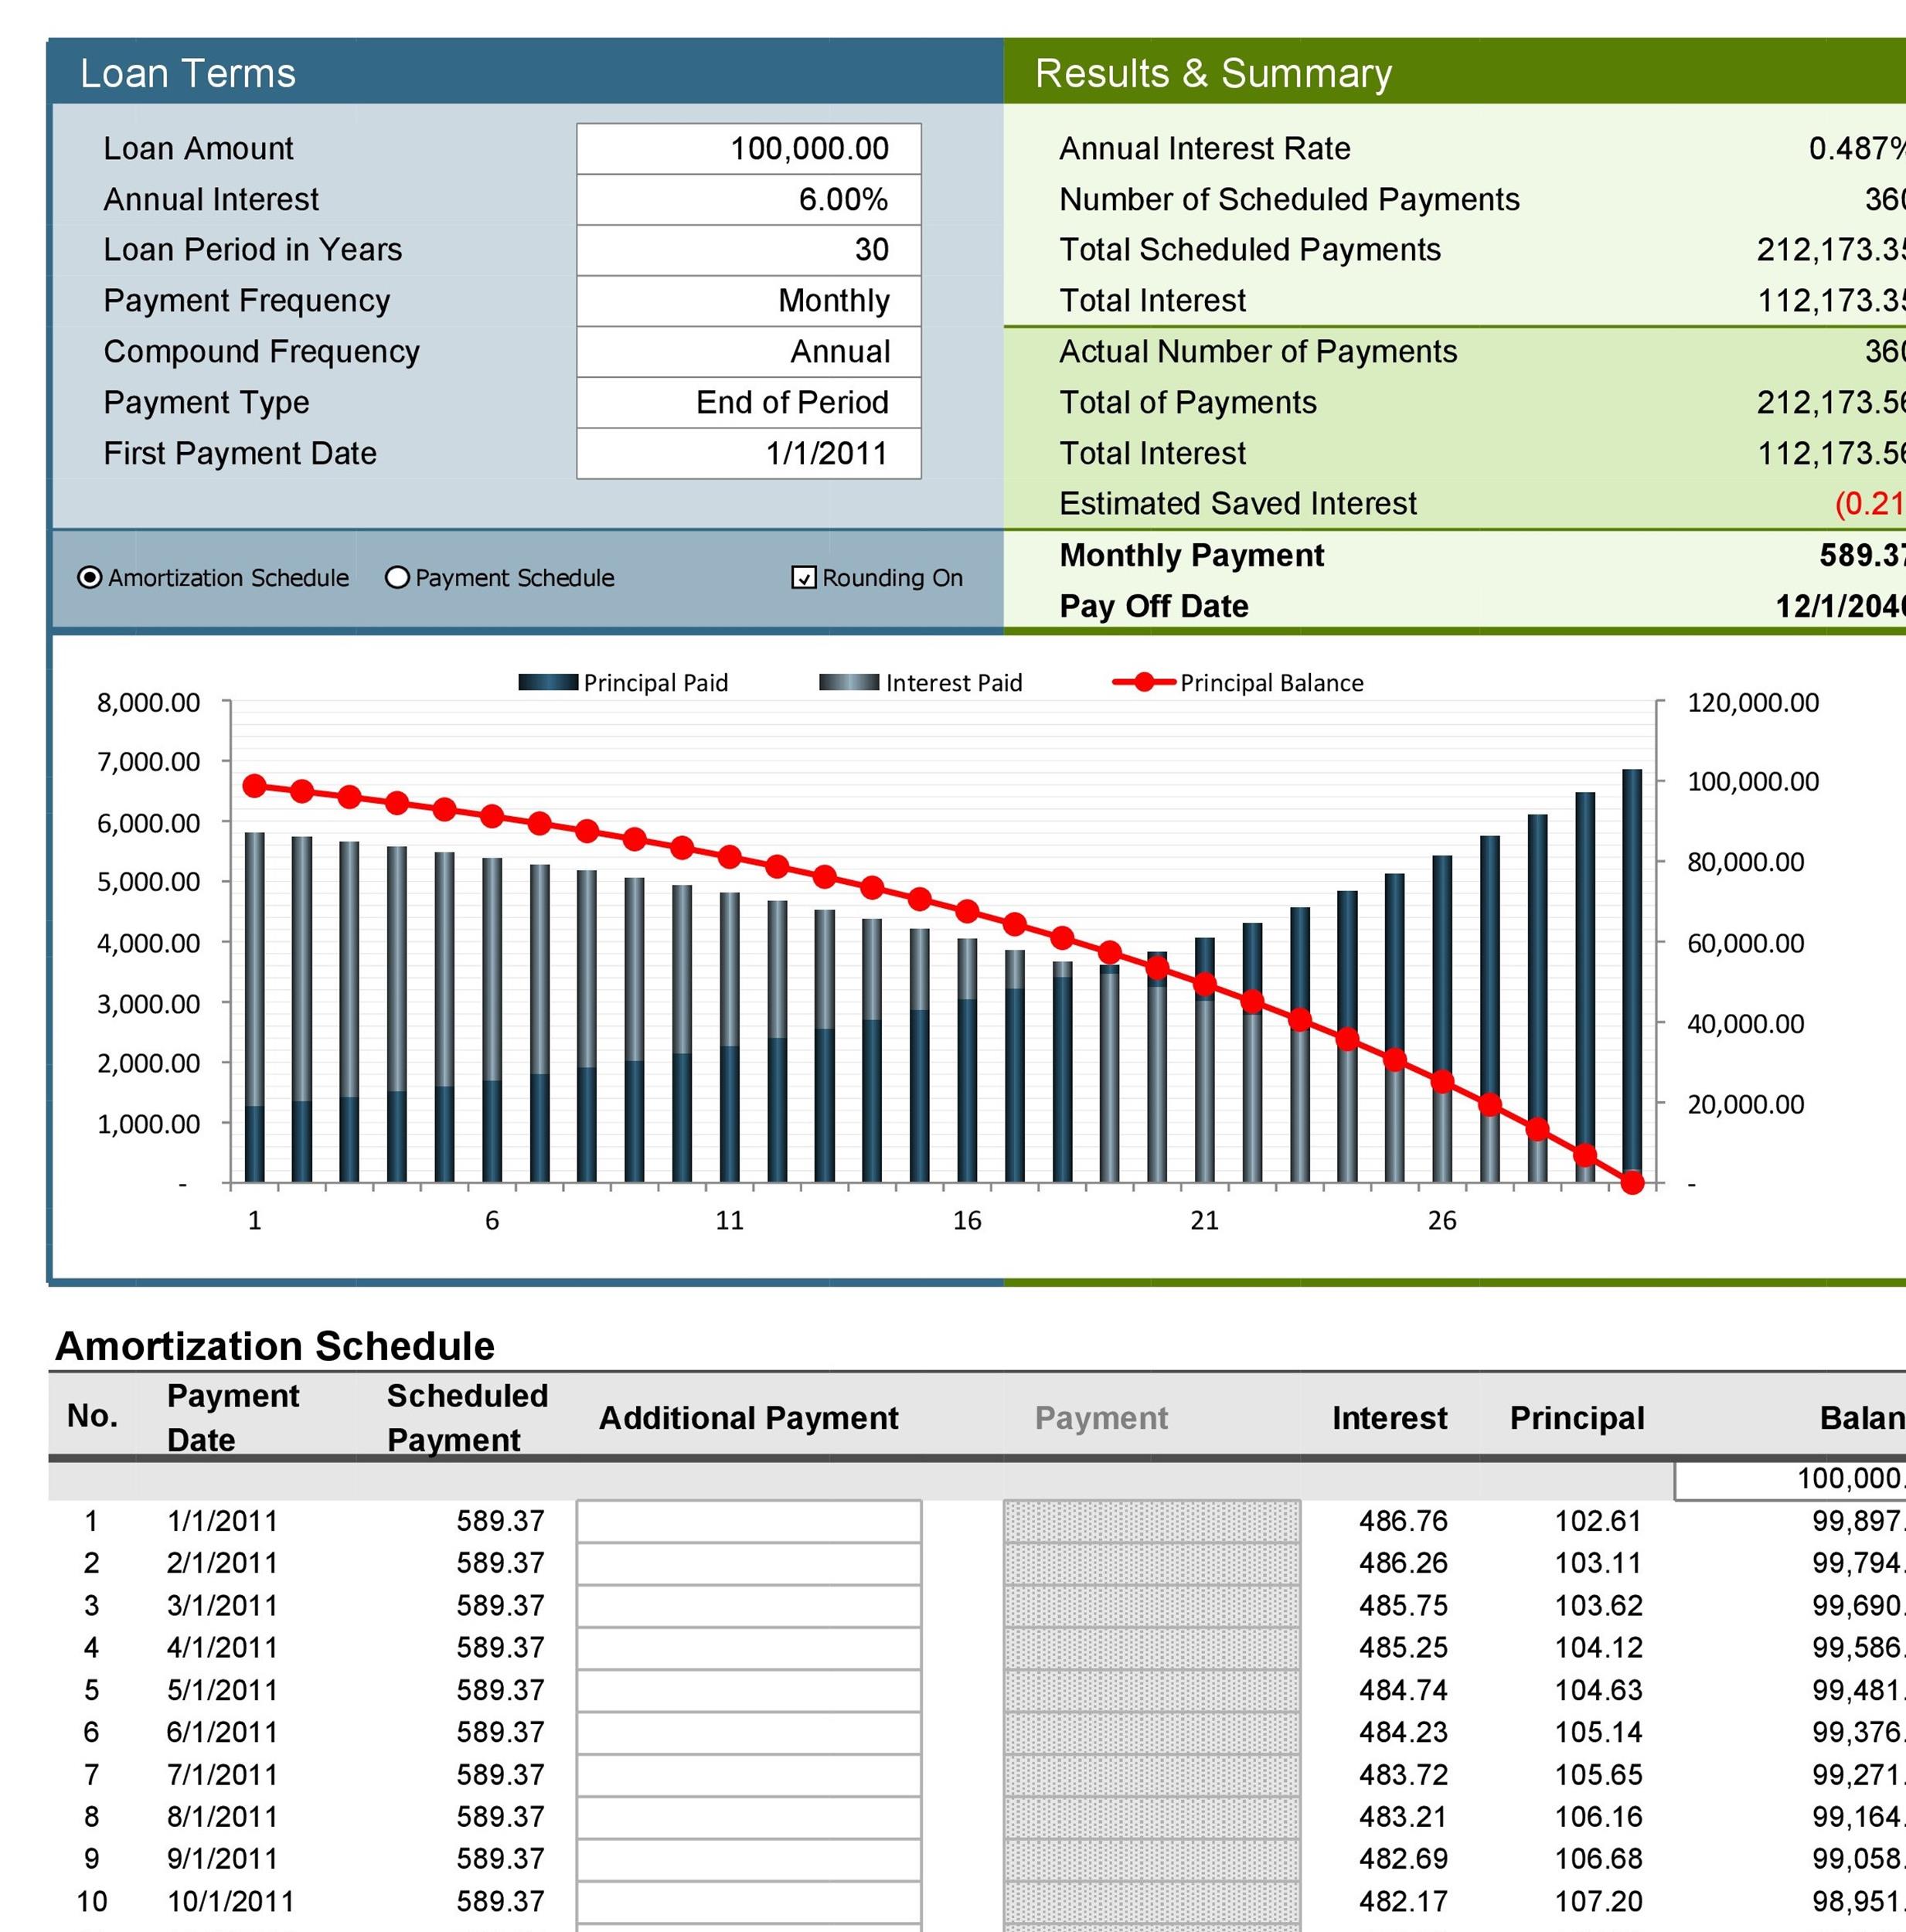
If I could redo my amortization templates from scratch, I'd add a summary tab that shows the loan parameters and key metrics in one place: original principal, current balance, total interest paid to date, remaining interest, total cost of the loan, and the break-even point where principal overtakes interest. Having all of that on a single screen is invaluable when you're comparing multiple loans side by side, which is something I do constantly in my work. I'd also add a visual component. A simple line chart showing the principal and interest portions of each payment over the life of the loan makes the amortization curve immediately visible. It's the same data as the table, but in chart form, you can see at a glance where the inflection point is and how steep the decline in interest payments is. This helps when you're explaining loan structure to clients who aren't comfortable reading spreadsheets.
Where to Get a Working Template
You can build your own from scratch using the structure above. It takes about 15 minutes if you know what you're doing and longer if you're still getting comfortable with the formulas. If you'd rather not start from zero, there are several solid options available online. Microsoft's own template gallery includes a basic amortization schedule that handles standard fixed-rate loans. The free version works fine for simple scenarios, though it lacks the rate-change and extra-payment handling I described earlier. For something more robust, the Loan Amortization Table Template available through standard financial modeling repositories tends to cover the most common cases, including adjustable rates and partial prepayments. I typically download a base template and modify it to match the specific structures I'm working with rather than building from scratch each time. The time savings are real — what used to take me an hour now takes about ten minutes. Whatever source you use, verify the formulas before relying on the output. I've seen too many downloaded templates with hardcoded values or incorrect references that produce sensible-looking but wrong results. Cross-check a few periods against a manual calculation. If the numbers match, you're in business. If they don't, you've just avoided a very expensive mistake.