How to Build a Loan Amortization Table That Actually Handles Extra Payments
Most amortization calculators online treat extra payments like a nice-to-have footnote. They aren't. They change the entire shape of your loan. I spent three years building financial models for a mid-market lending firm, and the first thing I learned is that standard templates break the moment you add even a modest biweekly payment. Here's how to do it properly. The core mechanic is simpler than most people think. Each month, your regular payment gets applied to interest first, then principal. When you throw in an extra amount, that entire chunk goes straight to principal — it doesn't pay next month's interest first, it just reduces what's left owed. That reduction then shrinks the next month's interest charge, which means more of your regular payment goes to principal, and the spiral continues. I used to see people try to model this in spreadsheets by manually adjusting each row. That works fine for one or two extra payments. It falls apart after that. What actually works is a single formula-based structure where the extra payment column feeds directly into the principal calculation.
The formula for monthly interest is straightforward: outstanding balance multiplied by the monthly rate. Monthly rate equals annual rate divided by twelve. For principal, take your regular payment and subtract the interest portion. Then add any extra payment you've entered for that month. The new balance is previous balance minus total principal applied. Do this in a loop and you have your table.
Setting Up the Spreadsheet
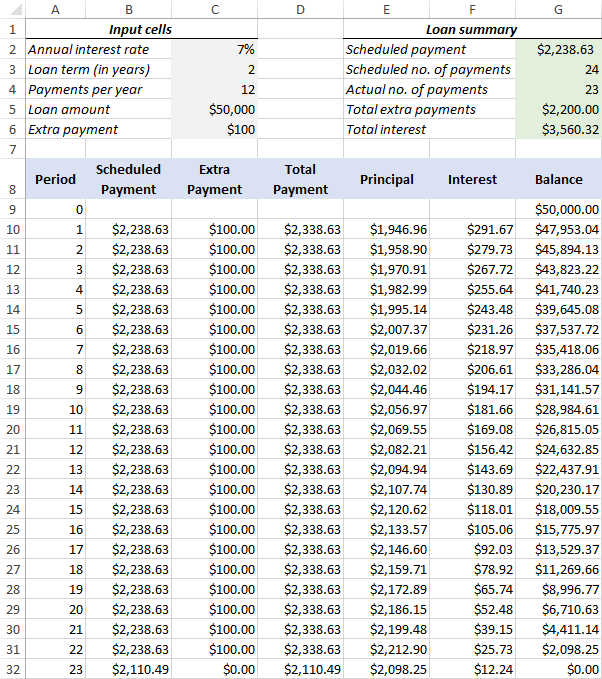
Start with these columns: Period Number, Beginning Balance, Regular Payment, Interest Portion, Principal Portion, Extra Payment, Total Principal Paid, Ending Balance. That last one feeds back into the beginning balance of the next row. You're building a chain here. For the interest calculation, use something like =B2*$C$1/12 where B2 is your beginning balance and C1 is your annual interest rate locked with absolute references. The regular payment can be calculated with the PMT function if you need it, or just hardcode your actual monthly payment amount. The principal portion is then =D2-E2. Add your extra payment, get your ending balance, and drag the formula down. The problem most people run into is that once extra payments come in, the payoff date shifts. Your standard 360-row table for a 30-year loan suddenly has zeroes at the bottom because the loan paid off early. You need a conditional check: if the ending balance hits zero or below, stop the calculations there. I use something like =IF(F2
=0, 0, F2-G2) to prevent the balance from going negative and cascading garbage through the rest of the rows.
Get the Full Details

What Happens When You Pay Biweekly Instead of Monthly
This is where things get tricky and where I personally made a costly mistake early in my career. A client wanted a comparison between monthly and biweekly payment schedules. The naive approach is to just halve the monthly payment and double the rows. That sounds right but it's technically wrong because biweekly payments hit at different points in the compounding cycle. Interest accrues daily on most loans, so paying every two weeks means you're making payments slightly earlier in some months and slightly later in others compared to a pure monthly schedule. The workaround I ended up using was to calculate daily interest accrual instead of monthly. That means the interest for each period is =Beginning Balance * Annual Rate / 365 * Days in Period. For a standard monthly payment schedule that's roughly 30.44 days on average, and for biweekly it's exactly 14. But here's the catch — not every lender calculates this way. Some use 30/360 day counting while others use Actual/365. If you're building this for actual use with a real loan, you need to confirm which day-count convention your lender uses. I've seen people lose hundreds of dollars because they assumed Actual/365 when their loan was on 30/360.
Counter-Intuitive Things Nobody Tells You
First: extra payments don't always save as much as you think if you start late. I ran the numbers on a $350,000 loan at 6.5% over 30 years with an extra $500 per month thrown in after year five. The interest savings were real but significantly less than if that same $500 had been added from month one. The early years of a loan are where the interest balloon is heaviest, and throwing extra money at principal early creates a compounding effect that late extra payments can't replicate. It's not that late extra payments are useless — they're just dramatically less efficient. Second: lump-sum extra payments have a different impact than recurring ones, and most calculators conflate them. A one-time $10,000 payment in year three does something very different from $278 per month for thirty-six months. The lump sum wipes out a chunk of principal instantly, which recalculates your entire remaining schedule. With a recurring extra payment, you're gradually shifting the curve. Some lenders will re-amortize after a lump sum, which means they rebuild your payment based on the new balance and remaining term. Others just shorten the term without changing your monthly payment. These produce very different outcomes and most generic calculators don't let you choose between the two.
A Specific Edge Case I Dealt With
I once had a loan with a partial prepayment penalty clause. The borrower wanted to make extra payments, but the first two years carried a 2% penalty on any amount over $5,000 per year. My spreadsheet was showing clean interest savings until I factored in the penalty structure. After month 24, every extra dollar beyond the annual cap cost 2 cents immediately. The math shifted from "extra payments save money" to "extra payments above the penalty threshold cost more than they saved in interest during the penalty window." I had to build a conditional column that checked whether cumulative extra payments for the year exceeded the threshold, applied the penalty to the excess, and then only fed the non-penalty portion into the principal reduction. It added about ten minutes of setup but saved me from presenting wildly optimistic projections to the client. This approach assumes a fixed-rate loan. Variable rates require you to rebuild the table whenever the rate changes, which means splitting your spreadsheet into segments with different rate periods. Most people don't account for this and end up with tables that look right but are wrong after a rate adjustment. There are ways to handle it — you can create a lookup table that maps periods to rates and reference that in your interest calculation — but it adds complexity that most simplified guides skip over. Another limitation is that your regular payment amount stays fixed in the standard model. If you're doing a recast instead of a re-amortization, your payment amount changes after the extra payment. A true amortization table with variable payments needs a flag system that either keeps the term constant and reduces the payment (recast) or keeps the payment constant and reduces the term (re-amortization). Mixing these up in your spreadsheet will give you incorrect results, and the error compounds over time because each row depends on the previous one.

For most personal use cases, a straightforward fixed-rate model with a consistent extra payment amount is sufficient. But if you're modeling for a client or making actual financial decisions, the assumptions you build into your table matter. The spreadsheet isn't just a calculation tool — it's a model of reality, and if your model has the wrong structure, the numbers will be confidently wrong, which is worse than just being wrong because you'll trust the output.