How Balloon Payments Actually Work in Practice
A balloon payment loan is just a regular amortized loan where the final payment is supposed to wipe out the entire remaining balance all at once instead of spreading it out. The monthly payments are calculated as if the loan will be paid off normally over the full term, but then a large lump sum comes due at the end. You might hear this called a "balloon mortgage" or a "bullet payment" in some markets. Same structure, different name. Here is the thing most people miss. The monthly payment does NOT reflect the balloon. It is computed using the full amortization schedule. So if you take out a $200,000 loan at 6% over 30 years with a 7-year balloon, your monthly payment is the same as a normal 30-year loan at 6%, which comes out to roughly $1,199.10 per month. Then at the end of year 7, you owe whatever is left, which is about $171,000. That is the balloon.
Loan Amortization With Balloon Payment Explained
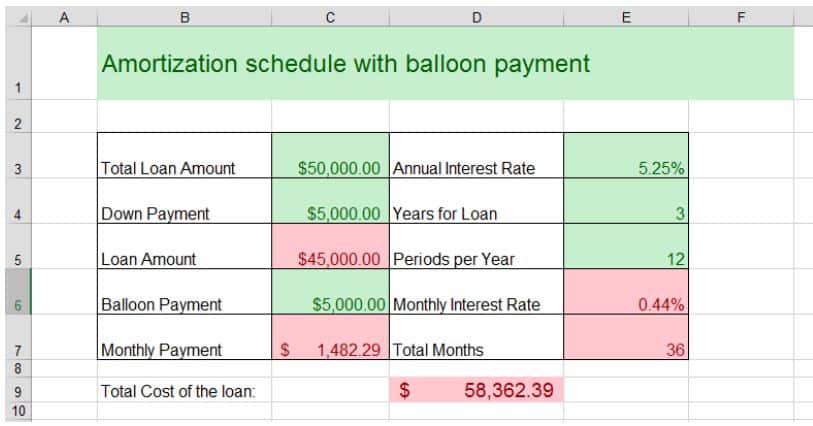
The math behind it is straightforward but slightly different from a standard amortization schedule because the schedule doesn't actually run to completion. You use the standard amortization formula to find the monthly payment, then you calculate the remaining balance at the balloon date using the future value of an annuity formula. I usually just plug it into a spreadsheet. The RATE function in Excel handles the monthly payment, and then you can use FV to get the remaining balance. It takes about three minutes once you have the template set up. The remaining balance formula at any point is: Balance = P × [(1 - (1 + r)^-n) / r], where P is the monthly payment, r is the monthly interest rate, and n is the number of payments remaining if you were to pay it off normally. For the balloon date, you substitute the remaining term from that point forward. A lot of calculators online skip this nuance and just show you the payment amount without telling you what the actual balloon figure will be. I've seen people get blindsided because they assumed the balloon was built into the payment calculation.
Where the Real Problems Show Up
I worked with a commercial real estate client last year who refinanced a $4.2 million property on a 10-year balloon loan at 5.75%. The monthly payment was around $25,800. They projected a refinance at the end of year 10 based on property value appreciation and rising rents. The problem wasn't the math. The problem was the gap between when the balloon came due and when they could actually close on the new loan. Commercial refinancing can take 60 to 90 days. If the market shifts during that window, you're dealing with higher rates or tighter ltv requirements right when you have no choice but to borrow. That client narrowly avoided a liquidity crisis because their appraiser came in 8% above the broker's estimate, which made the difference between qualifying for the refinance and not. Another edge case that comes up constantly involves the prepayment penalty structure. Some balloon loans carry a yield-maintenance clause rather than a simple percentage penalty. This means if you prepay, you owe the lender the present value of all the interest they would have earned for the remaining term at the current market rate minus your contract rate. On a rising rate environment, this can cost significantly more than a flat prepayment fee. I had to negotiate a conversion from yield maintenance to a sliding-scale percentage penalty on a $1.8M balloon loan because the borrower's plan included selling the asset within 18 months, and the yield maintenance calculation would have erased their profit margin entirely. The lender agreed after about two weeks of back-and-forth.
Get the Full Details

What Most Amortization Calculators Get Wrong
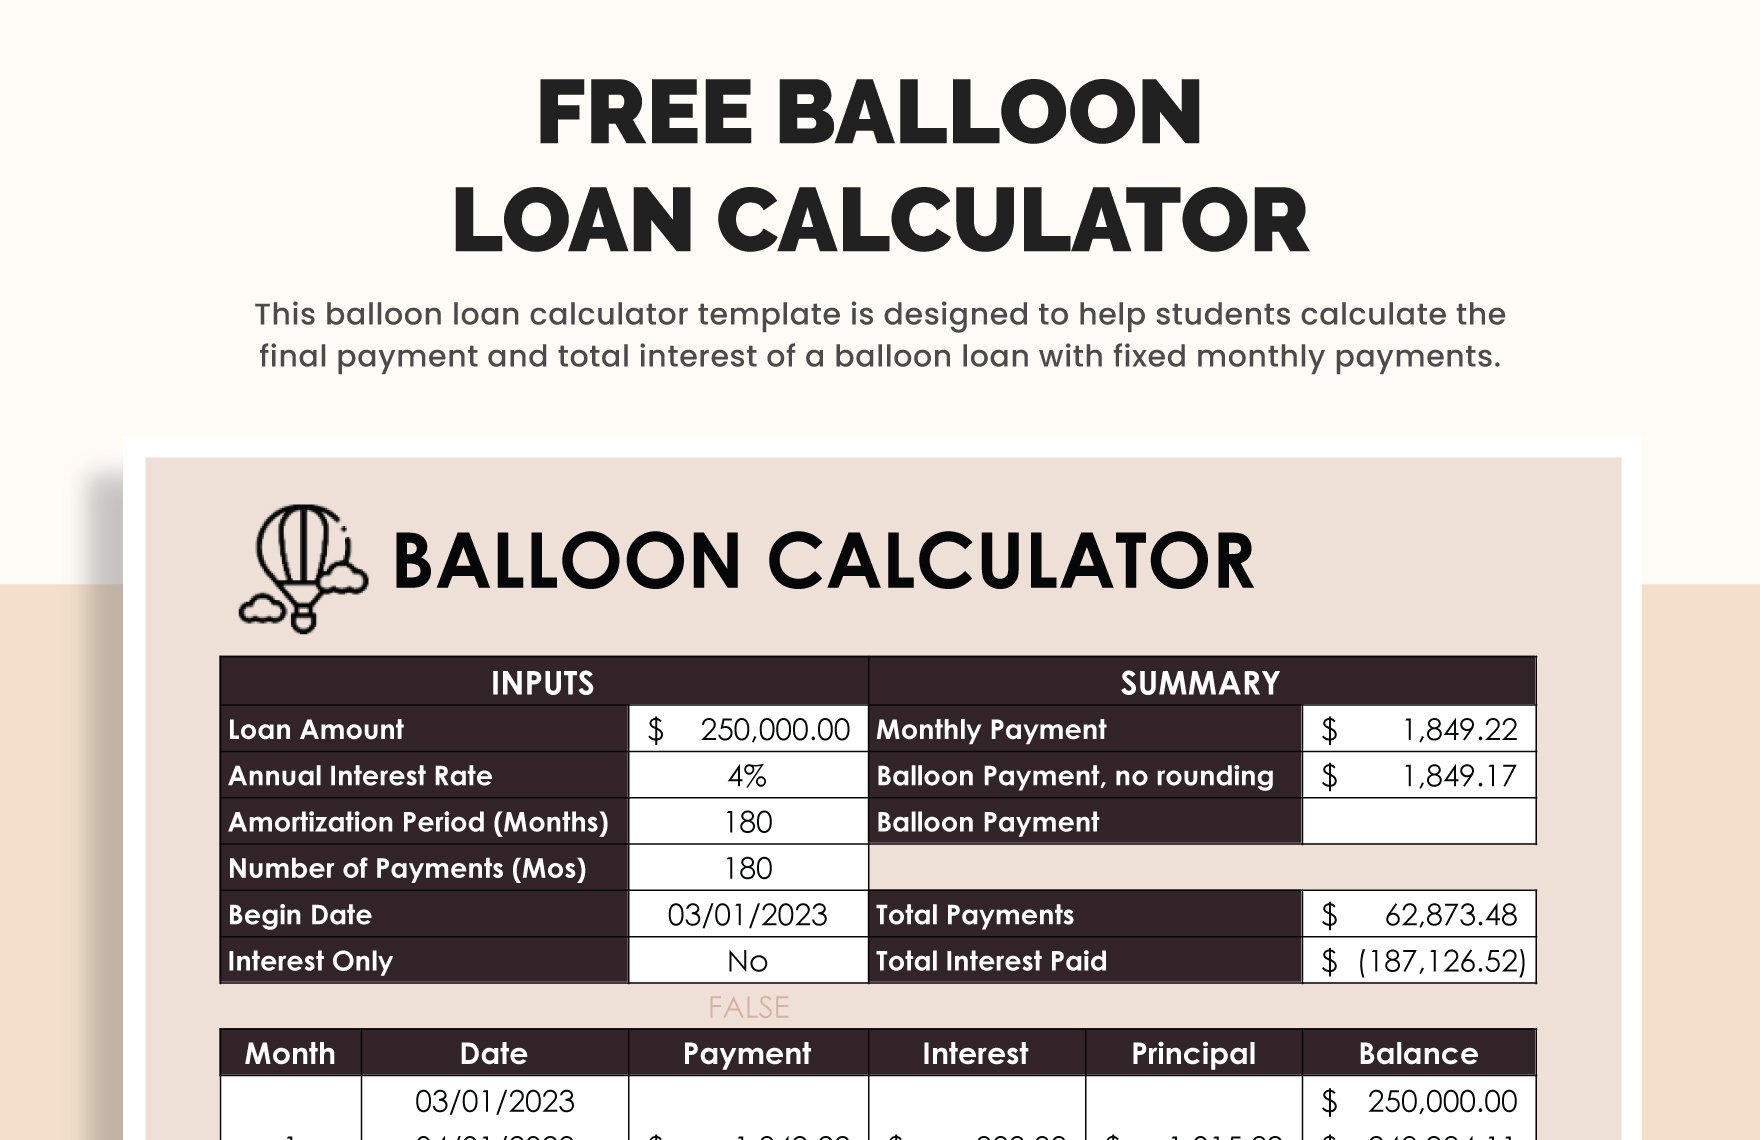
Online calculators that claim to handle balloon payments often just extend the schedule artificially or misapply the NPER function. A proper balloon amortization schedule needs three distinct sections: the payment period before the balloon, the balloon payment itself, and ideally a projection of what happens if you refinance versus what happens if you don't. I build my own templates because nothing I found online handled the scenario analysis properly. My template calculates the remaining balance at each potential balloon date, projects the total interest paid under different refinance scenarios, and flags when the debt service coverage ratio would drop below 1.2x under stress conditions. It cuts the analysis time from about 45 minutes to roughly 12 minutes per loan. You can find a basic Excel version of a balloon amortization calculator online if you search for "balloon loan amortization schedule template," but most of them are crude. A decent one should let you input the loan amount, annual rate, full amortization period, balloon date, and then output the monthly payment, the balloon balance, and the total interest paid. Look for one that shows the amortization schedule row by row so you can verify the numbers. If it only gives you summary figures without the breakdown, skip it.
When This Structure Makes Sense and When It Doesn't
Balloon loans exist because they serve a purpose, but that purpose is narrower than most borrowers realize. They work well when you have a clear exit strategy with a high degree of confidence, like a property that will be sold or refinanced within a known timeframe. They also tend to come with slightly lower rates than fully amortizing loans because the lender's exposure is shorter. The tradeoff is that you are taking on refinancing risk, which is real and measurable. A 2022 study by the Federal Reserve Bank of New York found that approximately 18% of commercial balloon loans required extension or modification at maturity due to borrower financial distress or market conditions. The alternative is a fully amortizing loan with a slightly higher rate, or a bridge loan structured for a fixed short term with a clear path to permanent financing. If you don't have a documented exit strategy and reasonable confidence in executing it, a balloon loan is a liability masquerading as a tool. I always ask borrowers to walk me through what happens if their plan fails. The answer is never satisfying, but it's better to hear it upfront than at the maturity date.
Quick Reference Numbers
For a $150,000 loan at 5.5% amortized over 30 years with a 5-year balloon, the monthly payment is approximately $851.97 and the balloon balance at year 5 would be around $134,200. Total interest paid over those 5 years comes to about $16,118. If you refinance the balloon at the same rate for another 30 years, your next payment would be roughly the same amount, but you'd have reset the clock and paid another $150,000 in principal slowly over the new term. The cost of rolling a balloon into a new loan is usually understated because people focus on the payment amount without tracking the principal balance over time. The structure itself isn't complicated. The risk comes from treating it like a standard loan and ignoring the maturity event. Once you account for the balloon in your cash flow projections and stress-test the refinance scenario, it's manageable. Most problems arise from skipping that step.