Building a Loan Calculator That Actually Works
Most people start with the PMT function and assume they are done. I learned that lesson three years ago when I handed a team a fully formatted spreadsheet that looked perfect on the surface, then watched them try to model a commercial loan with quarterly payments and a balloon maturity, and completely break it within twenty minutes. The built-in functions only work the way you tell them to work. They do not adapt to real-world loan structures unless you build that adaptation yourself. A basic amortization schedule requires five cells: principal, annual interest rate, loan term in years, payment frequency, and whether the rate is fixed or floating. From there, you convert the annual rate to a per-period rate by dividing by the number of periods in a year. You multiply the term by the same factor to get total periods. Then you run PMT against those converted values. That gives you a monthly or quarterly payment figure that matches the actual compounding structure, not some theoretical annual figure that nobody uses in practice.Loan Calc Excel
The most common mistake I see is treating the rate and nper arguments in PMT as if they are already in the right units. They are not. If your loan compounds monthly but you feed in an annual rate of 7.5 without dividing by 12, the payment comes out wildly wrong. I had a case where a financial analyst used a 10% annual rate directly in PMT against 30 periods and got a payment that was roughly four times higher than the correct figure. She spent two days trying to debug it before someone pointed out that 30 periods was months but 10% was annual.
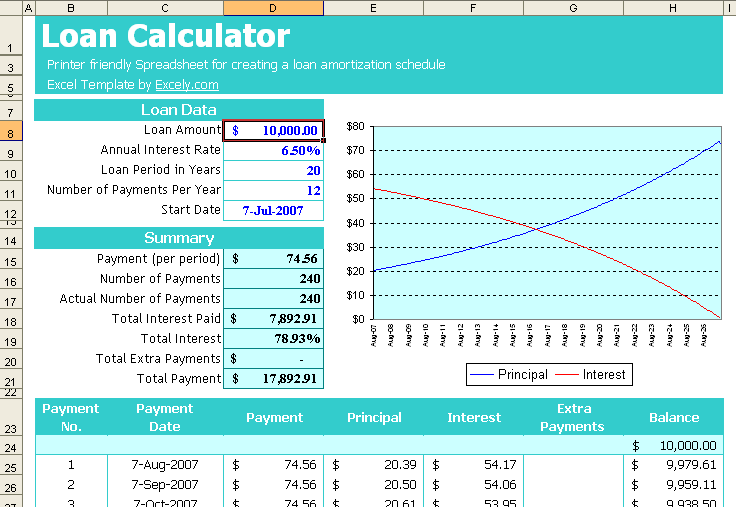
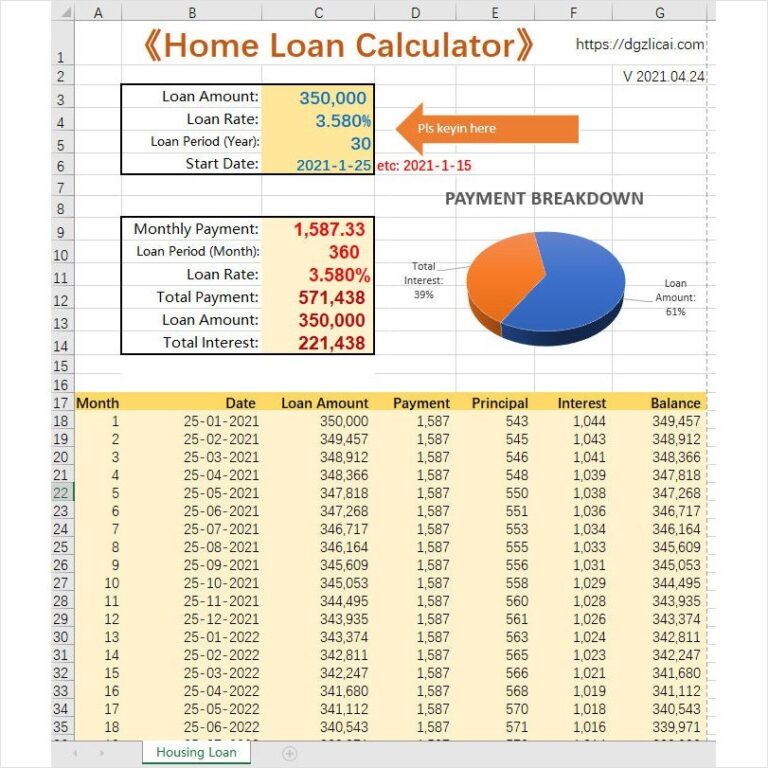
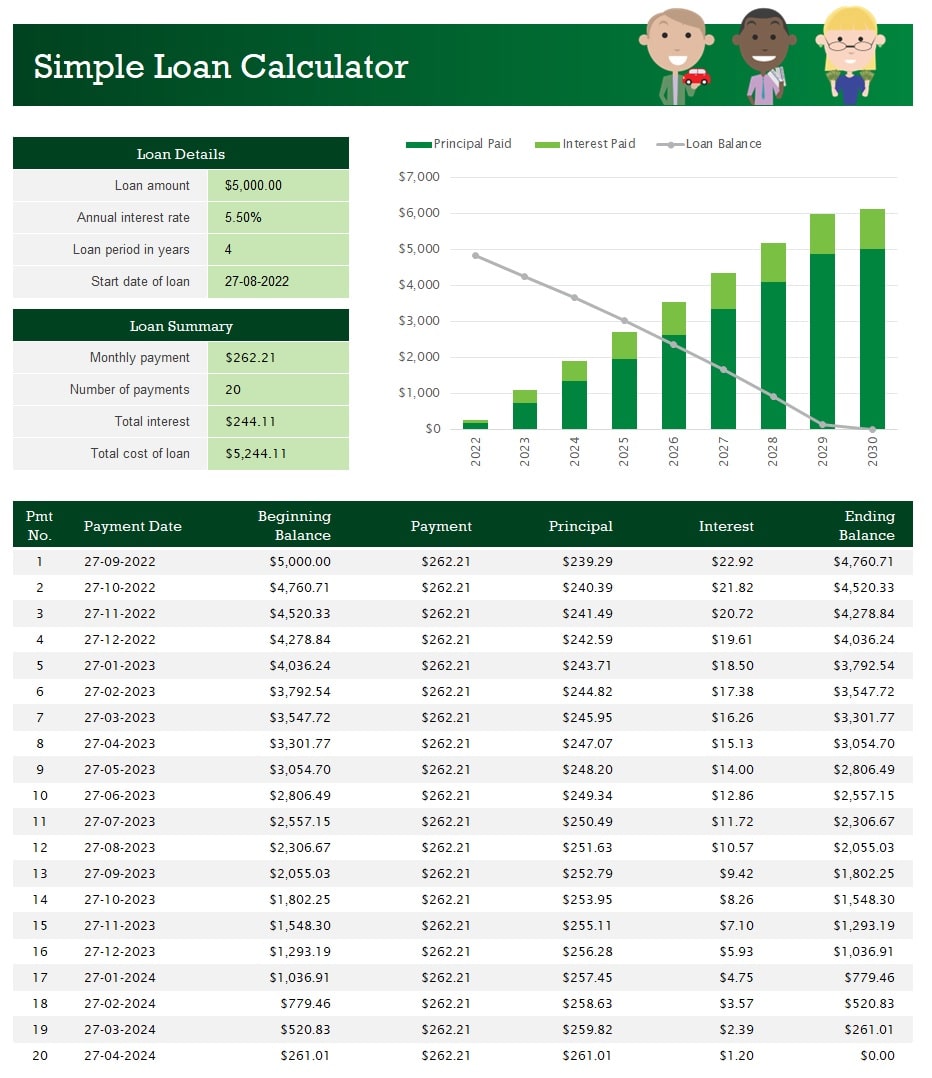
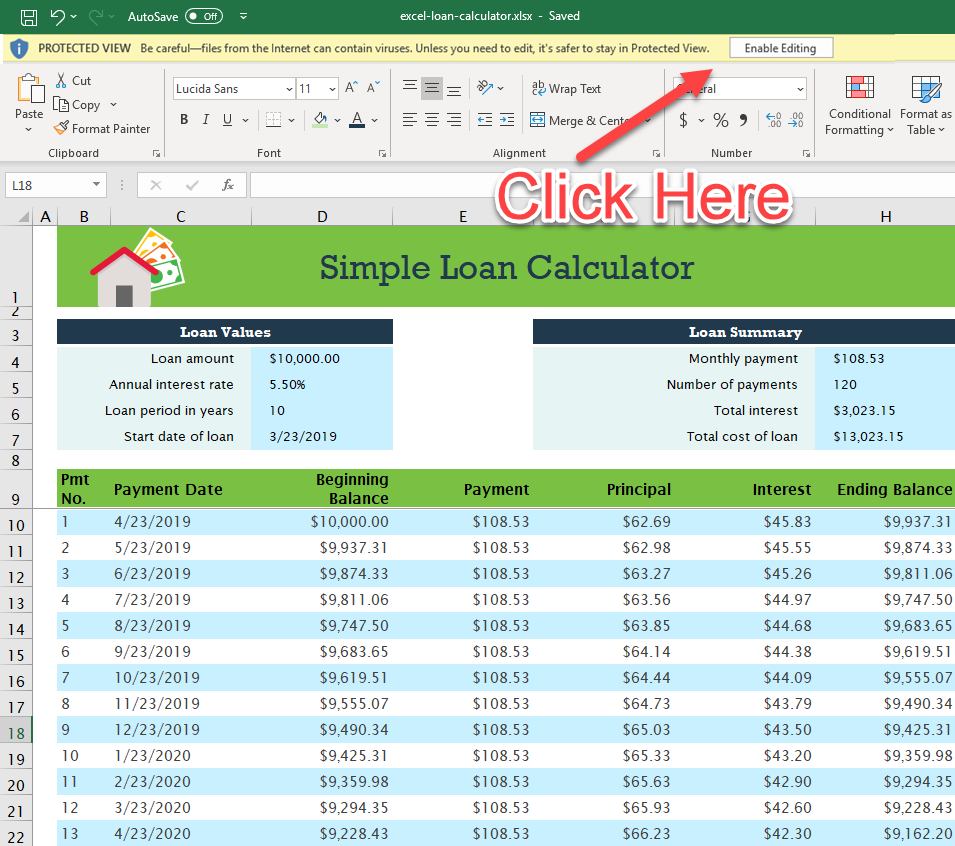
Step one is alignment. Whatever period your payments occur in, both the rate and the period count must be expressed in the same units. This is not optional. It is the single most important structural decision in any loan calculation model. Once you lock that down, the rest becomes mechanical. I set up my working model with a dedicated input section at the top, formatted distinctly from the calculation engine below it. You can tell the difference because the input cells are the only ones with a light blue background. Everything else is white. I learned this from watching people manually type numbers into cells that were already formula-driven, which overwrote the model and made it impossible to trace back where the error came from. A clear visual separation between inputs and outputs reduces that risk significantly. The PMT function itself is straightforward: =PMT(rate, nper, pv, [fv], [type]). The fv and type arguments are where most models go soft. FV represents the future value of the loan after all payments are made. For a fully amortizing loan, that is zero. For a balloon payment structure, it is the remaining balance due at maturity. Type is either 0 for payments at the end of the period or 1 for payments at the beginning. Most consumer loans use 0. Some commercial leases use 1. Your model should let the user specify this explicitly rather than hardcoding a default. Amortization schedules follow a recursive pattern. Each row calculates interest for that period by multiplying the outstanding balance at the start of the period by the per-period rate. The principal portion of the payment is the total payment minus that interest charge. The new balance is the old balance minus the principal portion. You drag this formula down for the full term, and you get a complete schedule showing how the loan pays down over time. Here is where it gets complicated in practice. I once built a model for a bridge loan with an interest-only period of eighteen months followed by a thirty-six-month amortization phase. The payment switches from pure interest to principal plus interest partway through the schedule. Standard PMT alone does not handle this. You need to calculate two separate payment streams and merge them into one timeline. The interest-only phase uses =principal * rate_per_period for each month. The amortizing phase uses PMT with the remaining balance and remaining periods. The transition point requires you to recalculate the effective rate based on the new balance and remaining term, which is not intuitive but follows directly from the time value of money. Another edge case that trips people up involves loans with fees. Origination fees, points, and closing costs reduce the effective amount you actually receive, which means the real annual percentage rate is higher than the stated rate. I built a workaround using XIRR on the actual cash flows: the net proceeds you receive upfront, the periodic payments you make, and any balloon payment at maturity. This gives you the true internal rate of return on the loan, which is what matters for comparison purposes, not the stated rate that the lender advertises. The XNPV and XIRR functions are your tools for irregular schedules. If your loan has payments on non-standard dates, or if there is a grace period, or if the first payment is partially adjusted, use these functions instead of the standard PV or RATE functions. They require a date column and a cash flow column, and they handle the actual day-count conventions automatically. Limits and failure modes deserve honest attention. Excel-based loan calculators break down when you introduce variable rates tied to an index with caps and floors. You can approximate this with IF statements and scenario tables, but the model becomes fragile and difficult to audit. For floating-rate commercial loans with complex adjustment mechanics, a dedicated financial modeling tool or a custom VBA solution is more reliable than a spreadsheet that relies on nested conditionals. I have seen models with over forty nested IF statements that took hours to recalculate and produced incorrect results under certain parameter combinations. That is not a sustainable approach. Another limitation is handling prepayment. If a borrower pays extra toward principal, the amortization schedule shifts. Standard PMT does not account for this because it assumes fixed payments. You need to build a dynamic engine that recalculates the remaining balance and adjusts the payment or term based on the prepayment amount. I typically add a prepayment column that users can fill in for any month, then shift the subsequent rows to reflect the reduced balance. This adds complexity but is necessary for any model that needs to answer the question of how much interest a borrower actually saves. For download references, I do not host files directly. What I can offer is a structural template you can reproduce in under an hour if you follow the approach above. Start with the input section, build the PMT calculation, generate the amortization table with interest and principal columns, add the prepayment and fee layers, then validate against a known benchmark like the Federal Reserve's published mortgage calculation examples. If your output matches theirs within a cent, your model is working correctly. The real value of a Loan Calc Excel model is not in the PMT function itself. It is in the structure around it. How you separate inputs from calculations, how you handle edge cases, how you make the model auditable and transparent to other users. These are the decisions that determine whether the spreadsheet is useful or whether it is just another file nobody trusts.