How Interest-Only Loans With Balloon Payments Actually Work
Most people see the low monthly payment and assume they have more room than they do. The structure is straightforward on paper: you pay only the interest for a set period, then owe the full principal plus any remaining interest in one lump sum at the end. But the details matter more than the summary.Calculating the interest-only portion is simple multiplication. Take your loan amount, divide by the number of payments per year, then multiply by the annual rate. A $200,000 loan at 6.5% annual interest with monthly payments means $200,000 × 0.065 ÷ 12 = $1,083.33 per month for the interest-only period. That is the payment you will see in any decent Loan Calculator Interest Only With Balloon Payment tool. The balloon payment is where people get confused or mislead. The full principal comes due at the end of the term, or sometimes a large partial balance does. If your loan is structured as interest-only for five years with a 30-year amortization schedule underneath, the remaining balance after those five years becomes the balloon. That is not always the entire principal. It depends on how the loan is actually documented.
Using a Loan Calculator Interest Only With Balloon Payment
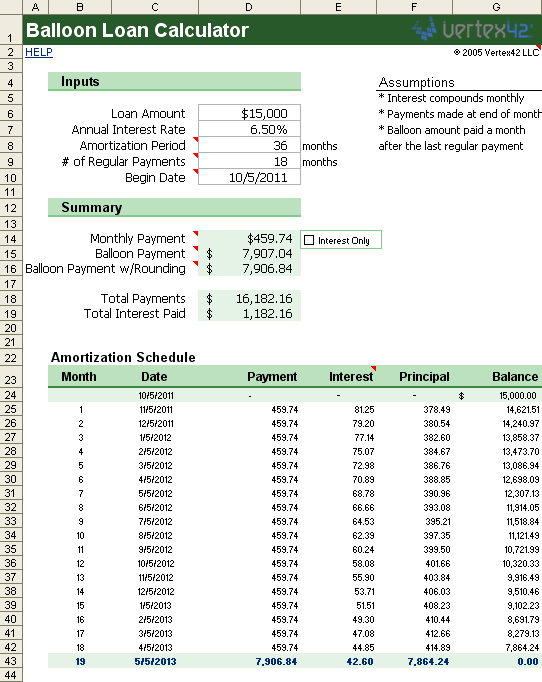
The most practical approach is to input the loan amount, annual rate, interest-only period length, and total amortization period. The calculator then shows two distinct numbers: your monthly payment during the interest-only phase and the final balloon amount due at maturity. You should always verify what the calculator assumes about the balloon, because some tools default to the full remaining principal while others use the scheduled unpaid balance from an amortization table. I once ran a calculation for a client who assumed a $350,000 interest-only loan at 5.75% for seven years would have a $350,000 balloon. It did not. The loan was amortized over 25 years beneath the interest-only period, so after seven years of interest-only payments, the remaining balance was approximately $298,400. That difference of about $51,600 changed the entire refinancing strategy. The tool I was using had an option to specify the amortization term separately from the interest-only term, and most free calculators online do not include that field. I switched to a spreadsheet model where I could control the amortization schedule explicitly and back-calculate the exact payoff balance at any point. Here is what you need to enter into a proper calculator: the loan amount, the annual interest rate, the length of the interest-only period in months or years, the total amortization period if the balloon is not the full principal, and the balloon date. Some calculators also let you account for whether the rate is fixed or adjustable. If the rate adjusts, your interest-only payment will change and the calculator should reflect that in a year-by-year breakdown. If it only gives you a single number for the life of the loan, it is probably assuming a fixed rate.
The Details That Cost People Money
Prepayment penalties are common in interest-only balloon loans. Lenders often charge a fee if you pay off the balloon early, typically a percentage of the outstanding balance that decreases the longer you hold the loan. A 3% penalty on a $300,000 balloon is $9,000. That is not included in any standard calculator. You have to factor it in separately if you plan to refinance or sell before the balloon matures. Tax implications are another hidden factor. The interest deduction on an interest-only loan works the same way as any other mortgage interest, but if you use the property for business or rental purposes, the rules shift. A calculator will never tell you about this. Your tax advisor will, usually after you have already made assumptions that do not hold up under scrutiny. The biggest mistake I see is treating the interest-only payment as the true cost of the loan. It is not. The monthly payment during the interest-only phase is artificially low because no principal is being reduced. When the balloon arrives, you either need cash reserves, a refinanced loan, or a sale. If you are counting on appreciation to cover the balloon, you are gambling, not planning. Markets do not always cooperate.
Get the Full Details
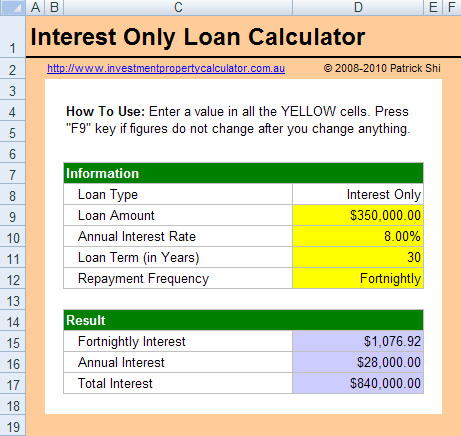
Another thing calculators rarely show is the impact of escrow. Property taxes and insurance are typically bundled into your monthly payment, which means your actual out-of-pocket cost is higher than the interest-only payment alone. On a $400,000 property in a high-tax area, escrow could add $400 to $800 per month on top of the interest payment. A thorough Loan Calculator Interest Only With Balloon Payment should include an escrow input field, but most do not.
When This Structure Makes Sense and When It Does Not
Interest-only balloon loans work well for short-term flip investments where you plan to sell within the interest-only period. The lower monthly payment preserves cash flow during renovation. They also make sense for borrowers who expect a significant income increase or a liquidation event before the balloon matures, such as a bonus, inheritance, or business sale. They fail when the borrower underestimates the balloon amount, overestimates their ability to refinance, or ignores prepayment penalties. I watched a borrower in 2019 roll a $275,000 balloon into a new loan without realizing the new rate was 8.25% instead of the 5.5% they had been paying. Their payment more than doubled overnight. The calculator had shown them a comfortable monthly figure for years. It did not show the refinancing scenario because nobody asked it to. If you are using this loan structure, build a worst-case scenario into your analysis. Assume you cannot refinance. Assume the property does not appreciate. Can you pay the balloon from your available cash without disrupting your other obligations? If the answer is no, you are taking on risk that a simple calculator output will not reveal.
What to Look for in a Reliable Calculator
A useful tool should break down the interest-only period month by month, show the exact balloon amount at maturity, and let you adjust the amortization schedule independently. It should also display total interest paid over the life of the loan and total principal paid, so you can see the real cost compared to a standard amortizing loan. Most free online calculators skip half of this. The ones that include it are usually part of a broader mortgage or loan analysis platform. For anything beyond a basic estimate, a spreadsheet gives you the control you need. You can model rate changes, escrow, prepayment penalties, and multiple balloon scenarios in one document. The initial setup takes maybe twenty minutes, but it saves you from making decisions based on incomplete numbers later. I keep a template that pulls the interest-only payment, remaining balance at any future date, and total cost comparison against a conventional loan in a single view. It has replaced most calculator tools for my own work. The bottom line is that an interest-only loan with a balloon payment is a tool, not a product. It can work if you understand the exact terms and have a plan for the balloon. It can destroy your finances if you treat the low initial payment as the full story. Run the numbers, stress-test them, and do not trust a single output from a generic calculator without checking what assumptions went into it.