How balloon loans actually work under the hood
A balloon payment is just a big lump sum due at the end of a loan term. The monthly payments are calculated as if the loan will be fully paid off over the term, but then the entire remaining balance just becomes due all at once. Most people see low monthly payments and think they're getting a deal. They usually are, for about two years, until the balloon hits. Here is what most online calculators do not tell you about balloon payment calculations. Standard amortization formulas assume equal payments throughout. A balloon loan breaks that assumption. You pay a calculated monthly amount based on the full term, then suddenly owe the remaining principal in one shot. The math itself is straightforward, but the edge cases are where things get ugly. The formula for a balloon payment looks like this. First calculate the monthly payment using the standard amortization formula:
M = P × [r(1+r)^n] / [(1+r)^n - 1] Where P is the principal, r is the monthly interest rate, and n is the total number of payments. Then calculate the remaining balance at the balloon date: B = P × [(1+r)^n - (1+r)^p] / [(1+r)^n - 1]
Where B is the balloon balance and p is the number of payments already made. That remaining balance is what comes due. Simple enough on paper. I ran into a specific problem recently that most calculators completely miss. A client was comparing two balloon loan offers. One showed a monthly payment of $1,247 and a balloon of $62,000. The other showed $1,189 monthly with a balloon of $71,500. The second looked better on the surface because the monthly payment was lower. But when I dug into the actual total cost, the second loan ended up costing nearly $14,000 more over the full term because the balloon was so much larger and the interest rate was slightly higher. Most people would have picked the lower monthly payment without checking the total picture. I built a comparison spread sheet that tracks total interest paid across both the payment period and the balloon payoff, which took about twenty minutes to set up and saved us from making a costly mistake.
Get the Full Details
Common pitfalls that catch people off guard
The biggest mistake I see is treating a balloon loan like a conventional mortgage. In a conventional loan, your monthly payment gradually shifts from mostly interest to mostly principal. In a balloon loan, the principal portion of your payment stays tiny because the big payoff is deferred. You are not building equity at anywhere near the rate you think you are. Another issue is refinancing risk. When the balloon comes due, you typically need to refinance or sell. Interest rates can move against you. I worked with a borrower in 2022 who had a balloon payment of $180,000 coming due. Rates had jumped from 4.5% to 7.8% in the twelve months leading up to their balloon date. Their refinanced payment was nearly double what they had been paying. They had to sell the property at a loss because they could not qualify for the new payment. The calculator showed comfortable monthly numbers for three years. It did not show that those numbers would vanish entirely when the balloon arrived.
What to look for in a good balloon loan calculator
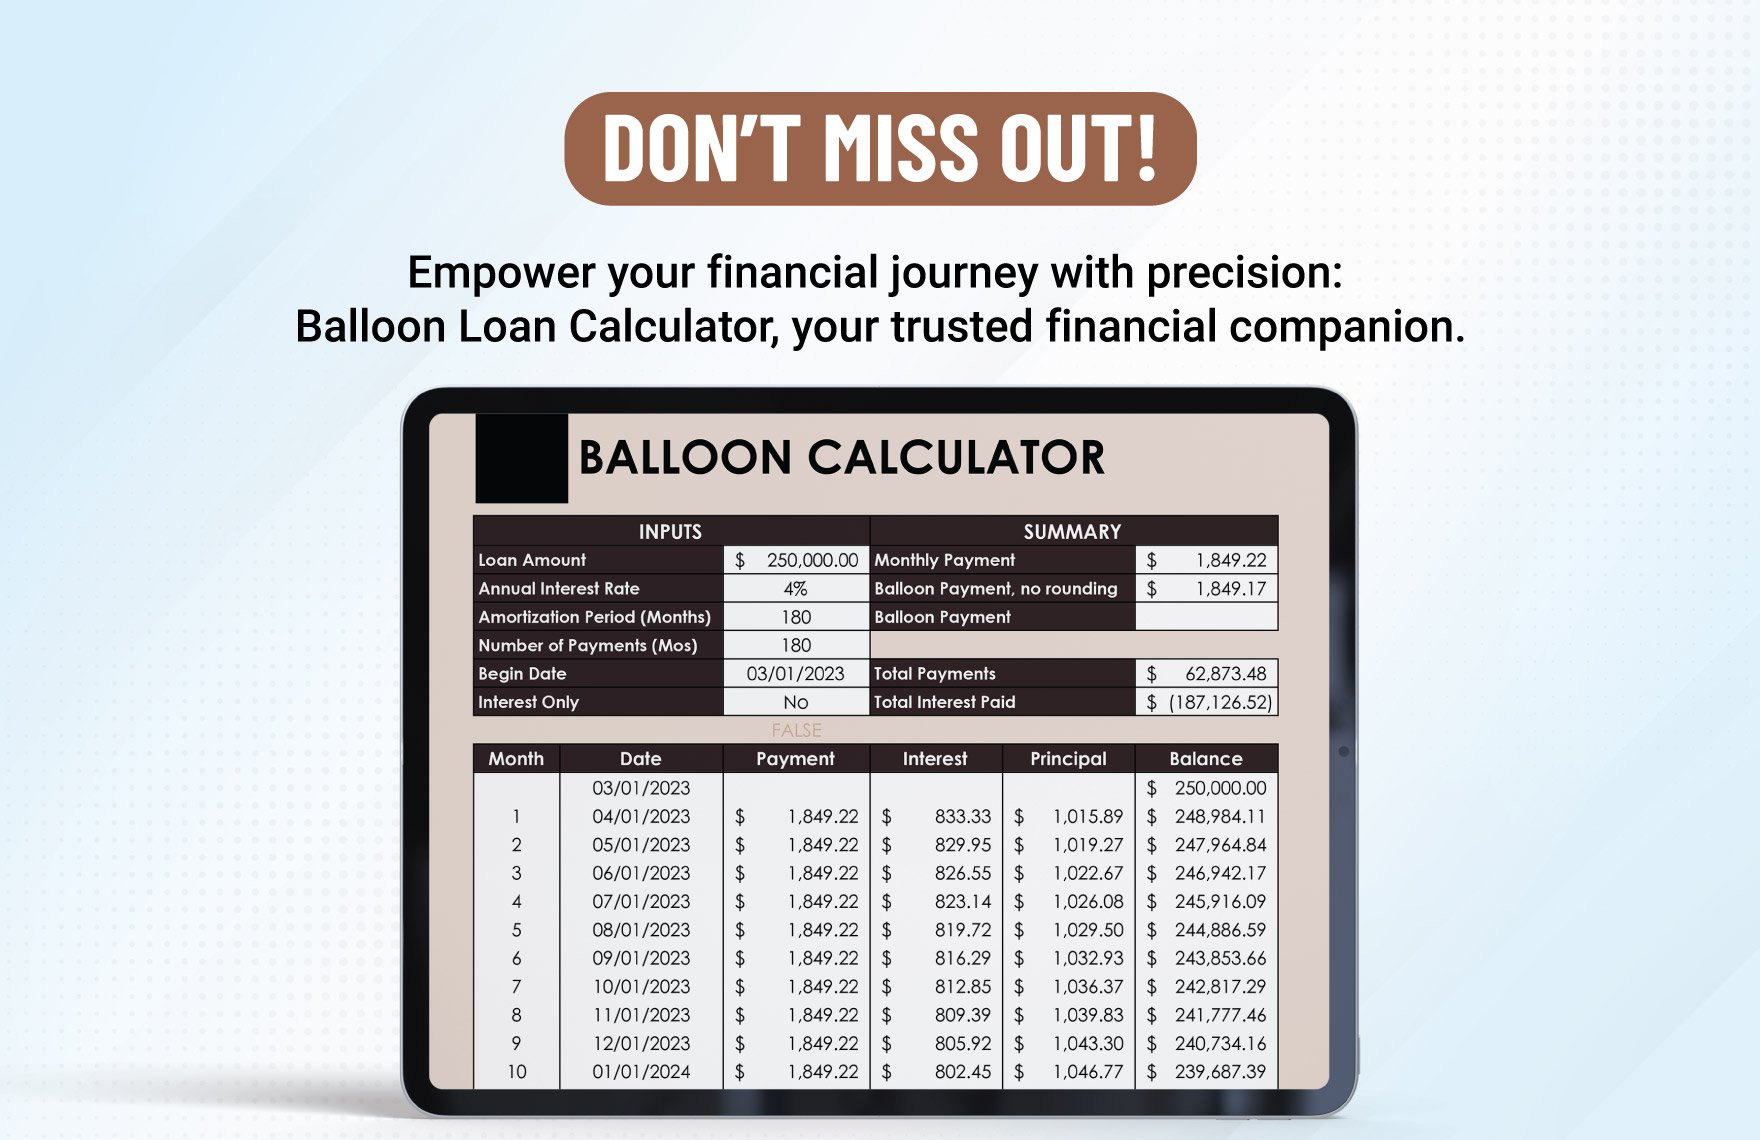
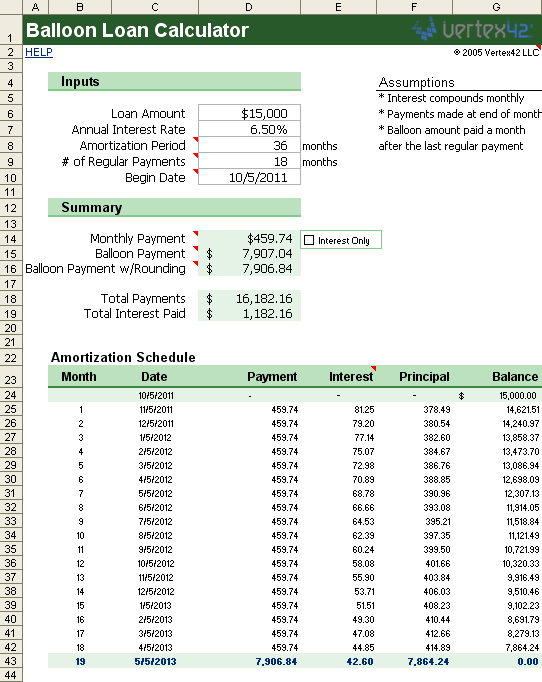
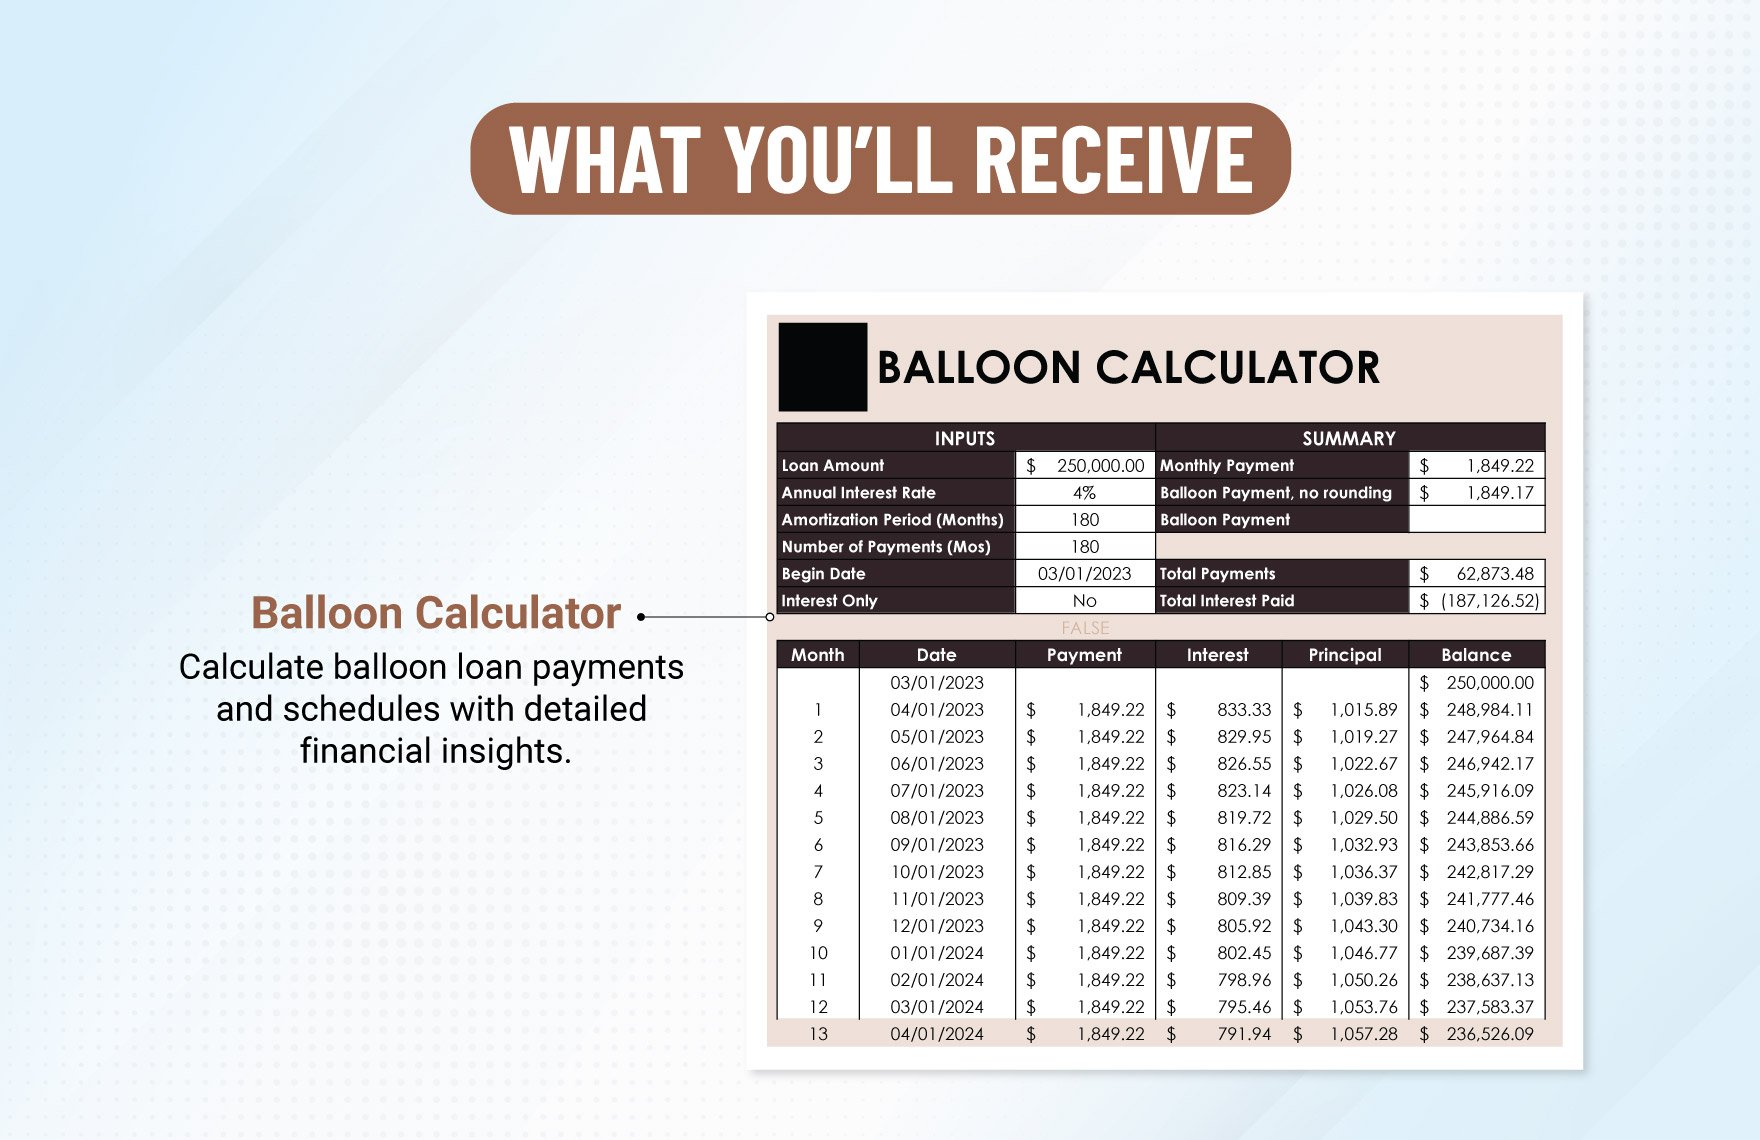
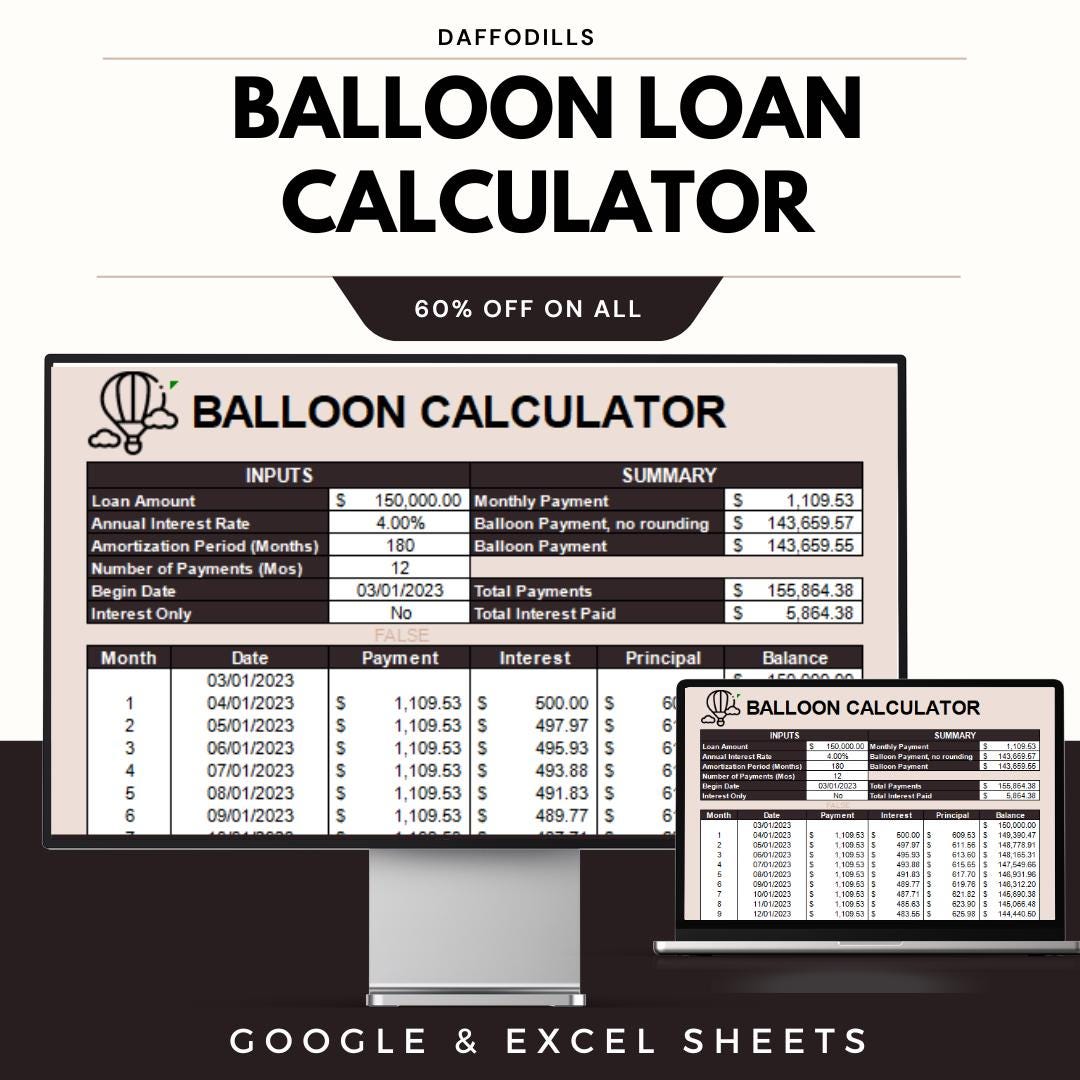
A proper Loan Calculator With Baloon should show you more than just the monthly payment. It needs to display the remaining principal at the balloon date, the total interest paid during the payment period, and ideally a comparison between the balloon structure and a traditional amortizing loan over the same term. Some calculators also factor in whether the balloon is a partial balloon where you pay down some principal but still owe a large remainder. The calculators that are worth your time also handle different payment frequencies. Monthly, biweekly, and annual balloon structures all produce different results, and most free online tools only do monthly. If you are working with a biweekly payment schedule, you need a calculator that can adjust the rate and period accordingly. I usually just tweak the inputs manually in a spreadsheet when the online tool does not support it. Takes about five minutes. There are also limitations you should know about. Most balloon loan calculators assume you will make every payment on time. They do not account for late fees, payment skips, or variable rate adjustments. If you have an ARM with a balloon feature, the interest rate could change before the balloon date, which throws off all the projected numbers. The calculator gives you a snapshot, not a guarantee. Real world conditions like prepayment penalties, rate resets, and refinancing denials all fall outside what any calculator can predict.
If you need something more robust than a free online tool, I recommend building your own model in a spreadsheet. It takes maybe thirty minutes to set up properly, and you get full visibility into every variable. You can build in scenarios for rate changes, early payoffs, and different balloon dates. Free calculators are fine for rough estimates, but they are not reliable for decisions that involve six figures.
When balloon loans actually make sense
They work best when you have a clear exit strategy. Flip properties, short-term business cash flow loans, or situations where you know you will refinance within a specific window. If you are confident you can sell or refinance before the balloon due date, the lower monthly payments can free up capital for other uses. The problem is when people lose sight of that exit strategy and assume the balloon will just sort itself out. The numbers do not lie, but they also do not tell the whole story. A balloon loan calculator gives you the mathematical outcome based on the inputs you provide. It cannot tell you whether refinancing will be available when the balloon hits, whether your income will support the refinance, or whether the property value will be sufficient. Those are the variables that actually determine whether a balloon loan works for you or becomes a financial trap. I have seen too many people walk away with a loan that looked great on paper because the monthly payment was manageable. The calculator showed comfort. Reality showed otherwise. Always run the numbers for the worst case scenario, not just the base case. That means testing higher interest rates, shorter hold periods, and lower property values. If the balloon structure survives those stress tests, then you might actually have a viable plan.