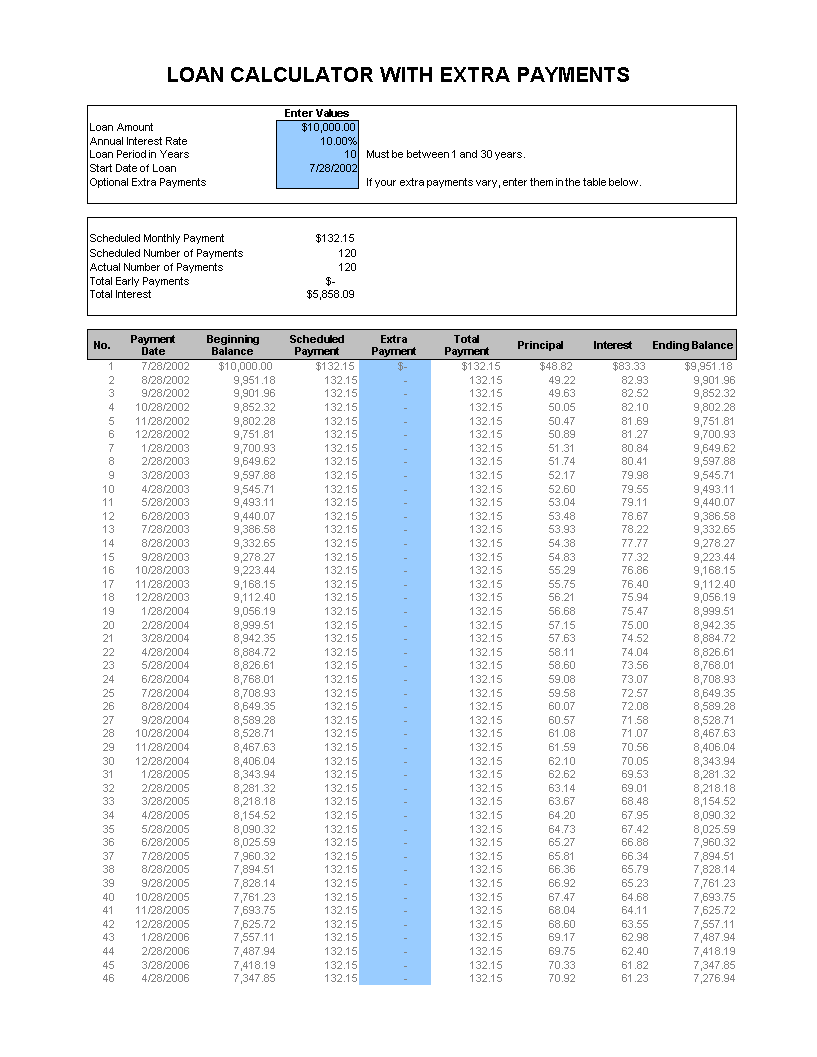
Why standard amortization schedules miss the mark
Most loan calculators show you what happens when you pay exactly what the contract says. That's useful for budgeting, but it's not useful if you're trying to figure out whether making extra payments actually changes anything or if it's just going to get eaten by how the servicer applies the money. I've spent years building payment analysis tools for people who have mortgages, student loans, and auto loans they want to pay off faster, and the difference between a basic calculator and one that handles extra payments correctly is usually the single most frustrating thing for users. They put in a $200 extra payment, the calculator says they'll save $3,400 in interest, and then their bank statement shows none of that happened because the application went toward future principal accrual instead of reducing the actual balance.Building a Loan Calculator With Extra Payments
The core problem is that extra payments interact with amortization in ways most people don't expect. When you make an additional payment, it either reduces your principal immediately, which shortens the term and cuts interest, or it gets applied as a future payment credit, which does nothing until the next scheduled due date. A proper calculator needs to let you specify which bucket the extra money goes into, and then recalculate the entire schedule from that point forward, not just subtract the extra amount from the total interest like some oversimplified tools do.I built my first version around 2018 for a personal project. The initial approach was straightforward: iterate through each month, subtract the scheduled payment's principal portion from the remaining balance, add any extra payment if it was marked for that month, and compound the daily interest. This works fine for a flat-rate situation. It breaks down when your loan has a variable rate, prepayment penalties, or when the servicer handles biweekly payments differently than monthly ones. I learned this the hard way when a client sent me their spreadsheet showing a $4,200 discrepancy between what my calculator predicted and what their actual payoff statement showed. The issue was that their mortgage had a 1% prepayment penalty on any payment exceeding 20% of the scheduled amount in a single year. My calculator had no concept of that.
The workaround was adding a penalty flag system. You define threshold percentages and penalty windows, and the calculator checks each extra payment against those rules before including it in the savings projection. It's not elegant, but it's necessary if you want the numbers to match reality. Most free calculators online don't bother with this, which is why their outputs look suspiciously optimistic. For the interest calculation itself, you're working with the daily periodic rate, not the annual rate divided by 12. Most loans accrue interest daily based on the actual number of days in each period. So a 6.5% annual rate becomes something like 0.00017808 per day, and you multiply that by the outstanding balance and the number of days since the last payment. This is why a 31-day month costs slightly more in interest than a 30-day month even if your payment is the same. A thorough calculator accounts for this, though many skip it because the difference is small on shorter loans. On a $400,000 mortgage over 30 years, skipping daily accrual can introduce errors in the $200 to $800 range depending on how the payment dates align with month lengths. Another frequent mistake is assuming that reducing the term is the only benefit. Some calculators show you the new payoff date but don't break down how much total interest was paid versus the original schedule. Without that comparison, you can't tell if the strategy is actually working or if you've just shuffled the cash flow around. I always make sure my output includes both the revised term and the total interest savings side by side, along with the new monthly payment if the borrower chose to keep the same payment amount and shorten the term instead of keeping the same term and reducing the payment.
There's also the edge case of loans with escrow accounts. Property tax and insurance payments are bundled into the monthly amount, and an extra payment toward principal doesn't affect the escrow portion. Some calculators treat the entire payment as principal reduction, which inflates the projected savings. You need to separate principal and interest from escrow before applying any extra amount, and only the principal and interest portions participate in the amortization recalculation.
What to look for in a working calculator
If you're evaluating whether to build your own or use an existing tool, here are the features that actually matter. First, the ability to add one-time or recurring extra payments on specific dates, not just a flat monthly additional amount. Second, support for different payment frequencies, because biweekly payers who make half-payments every two weeks don't end up with the same results as monthly payers who add half a payment each month, even though the total annual outlay is identical. The difference comes from how often the principal is reduced and how interest compounds between those reductions. Biweekly typically saves about 3 to 5 percent more interest over the life of the loan compared to the monthly equivalent strategy, and a good calculator shows you both paths.Third, the output should display a full revised amortization table, not just summary numbers. If you can't see month by month how the balance changes, you can't verify the calculator is doing what it claims. Fourth, it should handle variable rates, because not every loan is fixed. I've had users with student loans and adjustable-rate mortgages who needed to model rate changes at specific points in the schedule, and basic calculators completely fail there. You need to be able to input a new rate starting from a given period and have the recalculation restart from that point with the updated terms. If you have a federally held student loan on an income-driven plan, for example, the monthly payment changes every year based on your reported income, and extra payments might not even be allowed or might be capped. A generic loan calculator with extra payments won't model that. You'd need either a specialized tool or manual calculations that respect the servicer's actual rules. I've seen people waste hours plugging numbers into a calculator only to discover the loan type they were modeling doesn't permit the payment strategy they were testing. The calculator gave them confident-looking numbers that had zero relevance to their actual situation. Now change the scenario slightly. Keep the $200 monthly extra payment, but instead of shortening the term, use the extra payment to recalculate what your new lower payment would be if you kept the original 30-year term. The calculator should show a payment around $1,447, which leaves you with more monthly cash flow while still paying off the loan in the original timeframe but with substantially less total interest. Some borrowers prefer this approach because it preserves flexibility, and the calculator should present both options clearly so you can compare them directly.
Get the Full Details

If you don't want to build this yourself, there are a few tools that handle extra payments more thoroughly than the typical free calculator found on lender websites. Look for ones that let you import your loan details, specify payment dates, and generate a downloadable amortization schedule with the extra payments factored in. The ones that only give you a single summary number without the underlying table are usually oversimplifying in ways that will mislead you on larger balances or longer terms. A reliable calculator should produce output you can audit, not just a final answer that looks convincing. The ones I tend to recommend are either well-maintained open-source projects on GitHub where you can inspect the source code to verify the math, or desktop applications that export to CSV so you can cross-check the numbers yourself. Web-based calculators are convenient but harder to verify, and that opacity is where errors hide. I've traced incorrect results back to rounding differences at the fourth decimal place in intermediate calculations, which seems insignificant until it compounds across 360 periods and produces a discrepancy large enough to change a decision.