Comparing Loans is Mostly About Reading the Fine Print
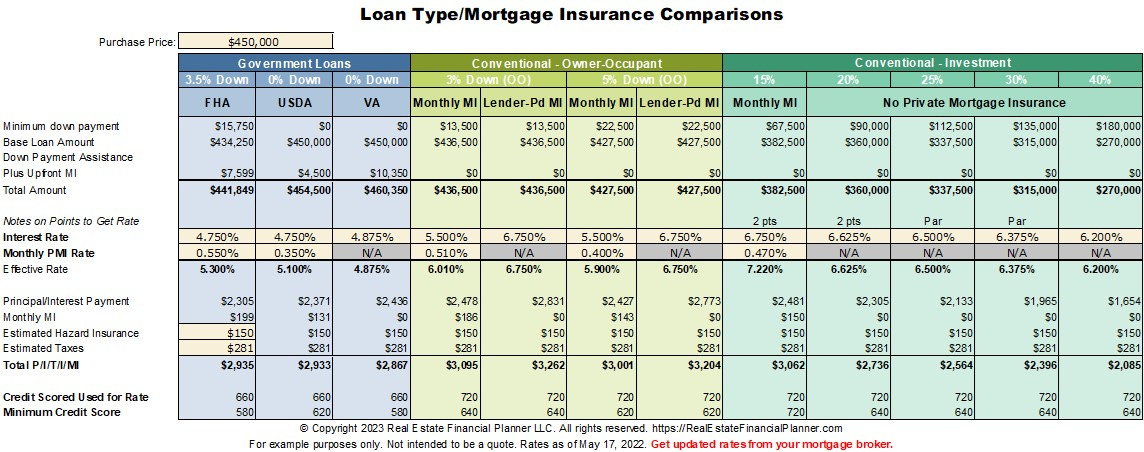
Loan Comparison is not complicated, but most people rush it and pay for it later. The basic idea is putting two or more loan offers side by side and looking past the monthly payment number to see what you are actually paying over the full life of the loan. That matters because a lower monthly payment can sometimes mean you are paying significantly more in interest, especially when the term is stretched out. I set up a quick spreadsheet once to compare three personal loan offers. The first one looked best at a glance because it had the lowest payment. When I dug into the amortization schedule, it turned out to be a seven-year loan with an 11.2 percent rate. The second option had a slightly higher payment but was structured as a five-year loan at 8.9 percent. Over the full term, the second loan cost me roughly four thousand dollars less in interest. The monthly payment looked worse for about twelve months, then I stopped thinking about it entirely.
How to Actually Do Loan Comparison
Start by gathering the real numbers from each lender. I do not mean the marketing page numbers. I mean the documents that come after you submit an application, or the Truth in Lending disclosure if you are in the United States. What you need from each offer is the annual percentage rate, the loan amount, the term length, any origination fees, prepayment penalties, and whether the rate is fixed or adjustable. Skip anything that feels vague and ask the lender to put it in writing. Next, calculate the total cost of each loan. There are online calculators for this, but I prefer doing it myself because you catch things automatically when you work through the numbers. Enter the principal, the APR, and the term. Then add in any upfront fees as if they were part of the loan balance. What you get back is the total amount you will have paid by the time the loan is finished. That single number is usually the one that decides everything. There is a shortcut too. You can use the monthly payment as a rough filter, but only after you confirm the rates and terms are comparable. If one lender is quoting an adjustable rate and another is quoting a fixed rate, the monthly payment comparison is meaningless until you model what happens if the variable rate moves. I ran into this exact problem when comparing home equity lines of credit. One lender offered a teaser rate that was dramatically lower than the fixed-option competitor. I asked for a five-year projection at a two percent rate increase, which is a modest jump from where we were at the time. The teaser loan suddenly looked expensive enough to walk away from.
Another useful step is checking for prepayment flexibility. Some loans charge a fee if you pay them off early, which completely changes the math if you plan to refinance or sell. Others let you make extra payments with no penalty. I once picked a loan that looked fine on paper and then realized there was a three percent prepayment penalty in the first three years. That cost me about eight hundred dollars when I refinanced during a rate drop. I learned to read that clause before signing anything again.
Get the Full Details
What Most People Miss in Loan Comparison
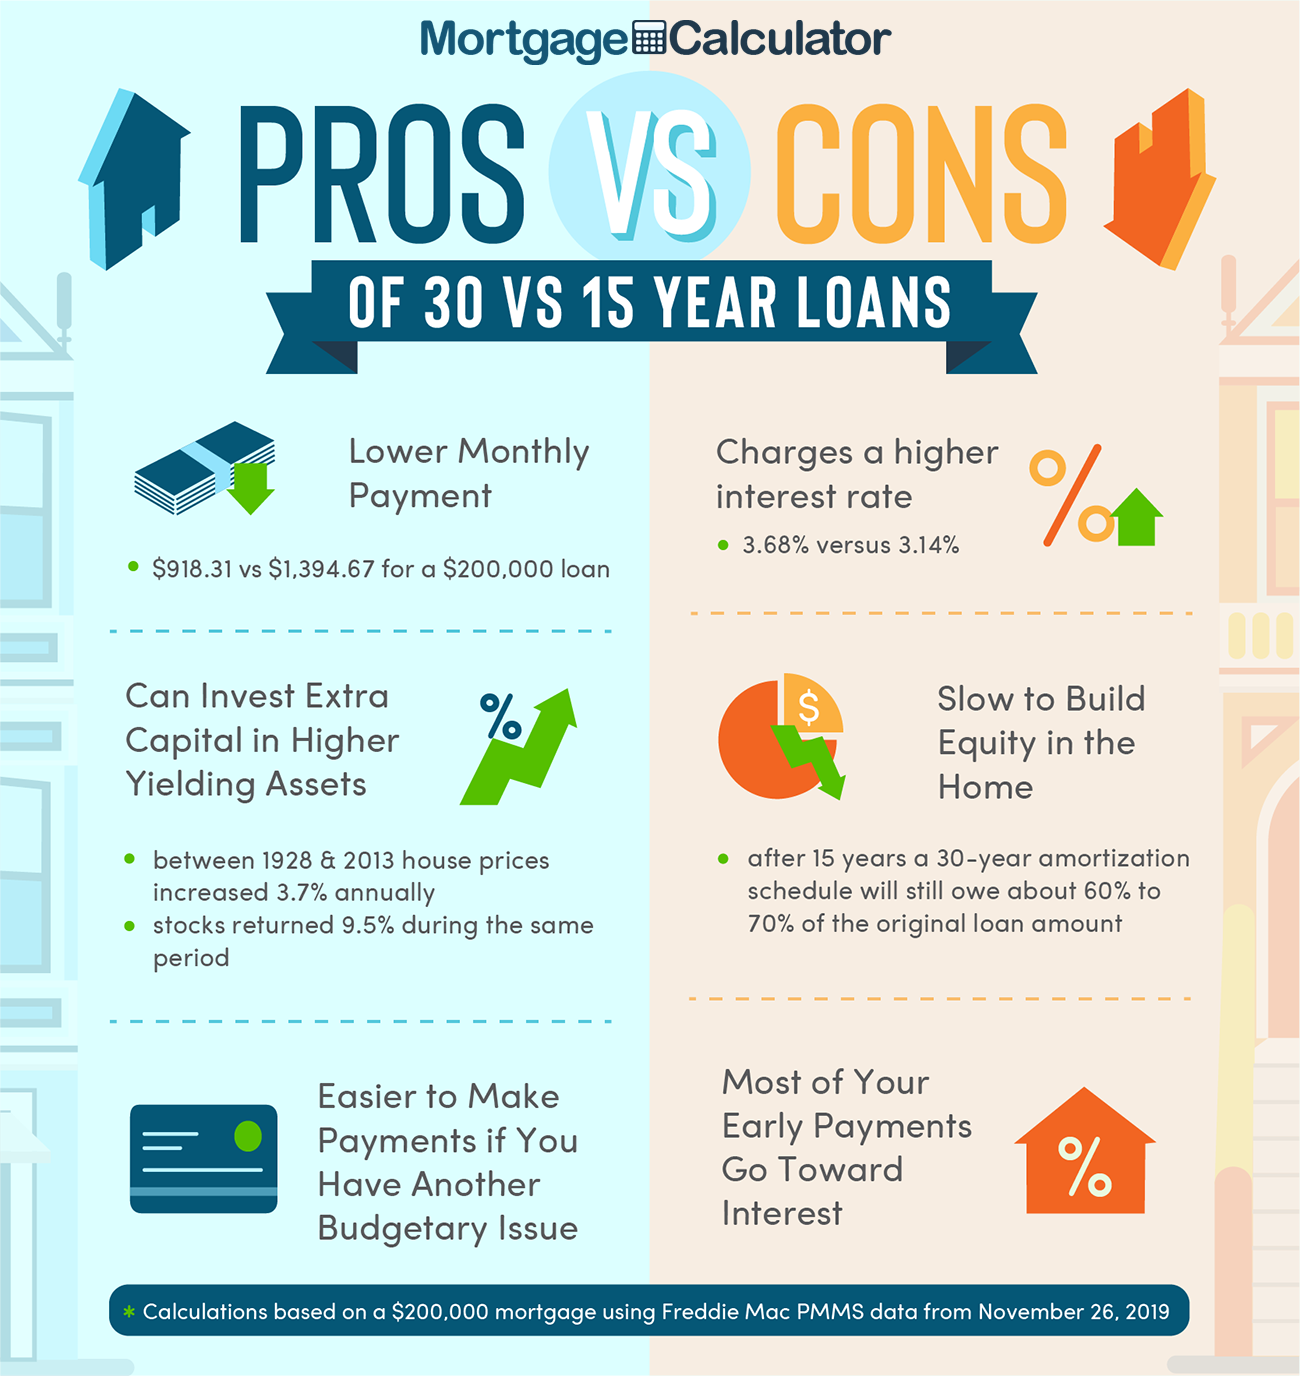
The biggest mistake I see is focusing only on the interest rate and ignoring the fee structure. An origination fee of one percent on a fifty thousand dollar loan is five hundred dollars. That is money you pay upfront and it does not disappear just because the rate looks attractive. If you are paying points on a mortgage, those get amortized over the life of the loan and affect your effective rate differently depending on how long you keep the loan. A less obvious issue is how compounding frequency changes the effective cost. Two loans might advertise the same nominal APR, but if one compounds monthly and the other compounds daily, the actual interest charged can differ slightly. The difference is usually small on short-term loans, but on something like a thirty-year mortgage it adds up. I spotted this when a borrower compared two refinance offers that looked identical on the surface. The fine print showed one was using daily compounding and the other monthly. Over three decades, the daily-compounded loan cost a few hundred dollars more. It is worth noting because lenders rarely point it out. Another thing people overlook is the difference between the stated rate and the effective rate once insurance and other mandatory products are added. Some lenders bundle credit insurance or payment protection into the loan. Those products increase your total cost without changing the advertised rate. In one case I reviewed, the lender had added a twenty-five-dollar per month disability waiver that was not clearly disclosed upfront. Across five years, that added twelve hundred dollars to the cost. Asking for a full breakdown including all required products is the only way to catch this.
When Loan Comparison Breaks Down
Comparison works well when you are evaluating similar products from multiple lenders. It becomes unreliable when the products are structurally different or when the data provided is incomplete. If one lender gives you a full amortization schedule and another gives you a one-page summary, you cannot fairly compare them until you force the second lender to show the same level of detail. I have called lenders and said I need the complete cost disclosure before I will continue the conversation. Most of the time they send it within an hour. A few refuse, and that refusal tells you everything you need to know. Another scenario where comparison fails is with subprime or non-traditional loans. These products often use fee structures and penalty clauses that are so complex that a straight comparison chart does not work. In those cases, you need to run a cash flow simulation that maps out every possible payment scenario, including what happens if you miss a payment or prepay early. I use a simple model that lists every cash outflow month by month, then sums it up. It takes about fifteen minutes to set up once you have all the terms in front of you, and it usually reveals problems that a standard calculator would hide. There is also the question of timing. Loan offers change. Rates move. Fees get waived or added. If you spend two weeks comparing offers and then the market shifts, your comparison may no longer reflect reality. I keep a running note of when each offer was quoted and remind myself that the numbers are a snapshot, not a guarantee. If the terms are still available when I am ready to commit, I recheck them rather than assuming nothing has changed.
Practical Steps for Loan Comparison
Get at least three offers before you decide. Two is barely enough to see a range. Three gives you a usable spread. Make sure the loans you are comparing are for the same purpose and similar amount. Comparing a small personal loan to a large auto loan will not help you. Write down every cost item in one place. Rate, fee, term, prepayment penalty, compounding method, required insurance. Put it in a table. It sounds tedious but it saves you from missing something that will cost you money later. Calculate total cost for each option. Add fees to the interest total. This is the number that matters more than the monthly payment.

Model the worst case. What happens if the rate adjusts up, or if you need to pay early and hit a penalty, or if you miss a payment and late fees stack up? Run the numbers for that scenario. If the worst case is manageable for one loan and brutal for another, the choice becomes clear. Ask about rate locks and expiration dates. An offer that expires in four days is less useful than one that holds for thirty days, especially if you are waiting on documents or a credit check. I prefer lenders who will lock a rate for at least fifteen days without charging a separate lock fee. Anything shorter and you are racing the market. Check the lender's complaint record. A cheap loan from a lender that routinely mishandles payments or refuses to document changes correctly is not a good deal. I look at state licensing boards and the Consumer Financial Protection Bureau database. It takes ten minutes and has saved me from a few bad choices.
The process itself is not exciting, and it will not save you money if you treat it as a formality. It works when you treat it as a real evaluation. Most people skip the part where they ask for the full disclosure and then wonder why the loan they signed is not what they thought it was. Do not skip it. The numbers are honest even when the sales pitch is not.