Understanding How a Loan Comparison Calculator Actually Works
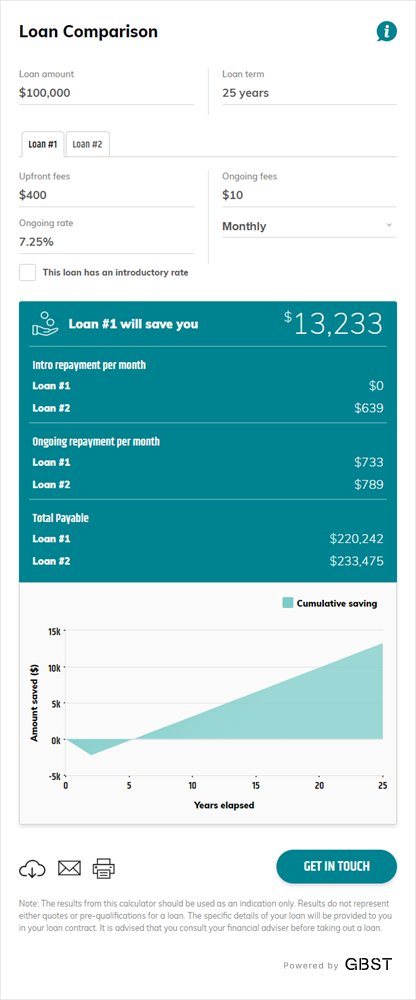
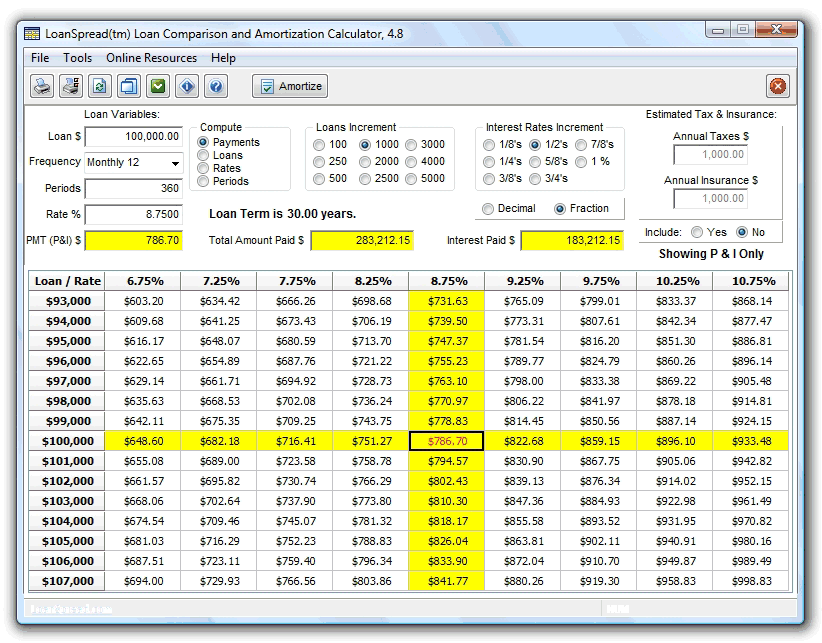
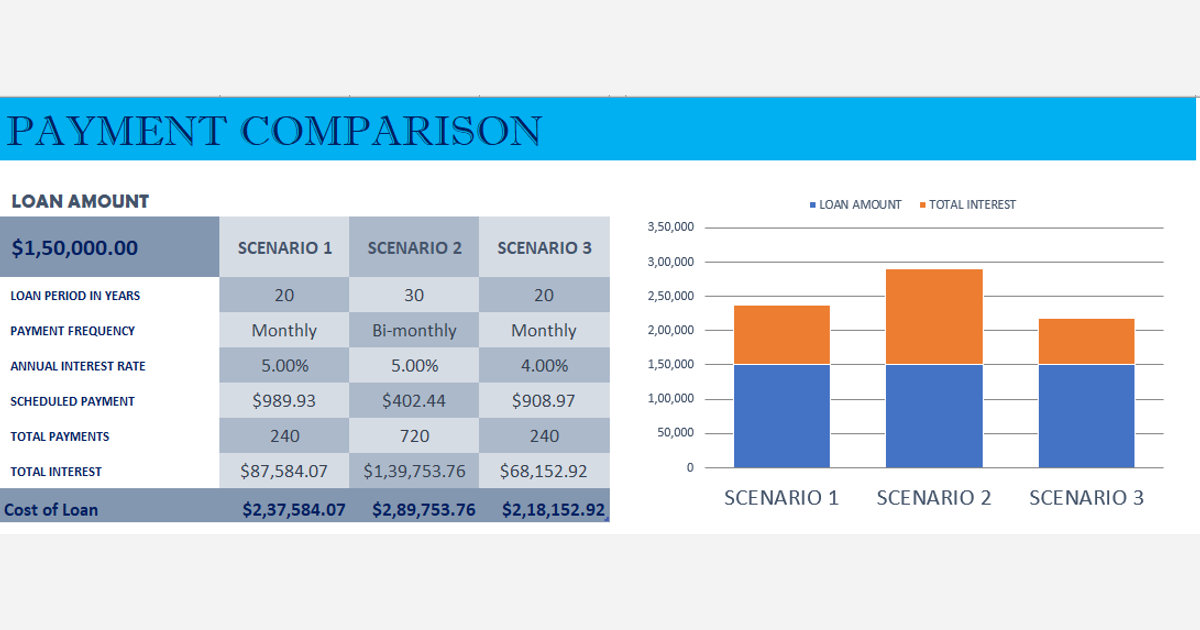
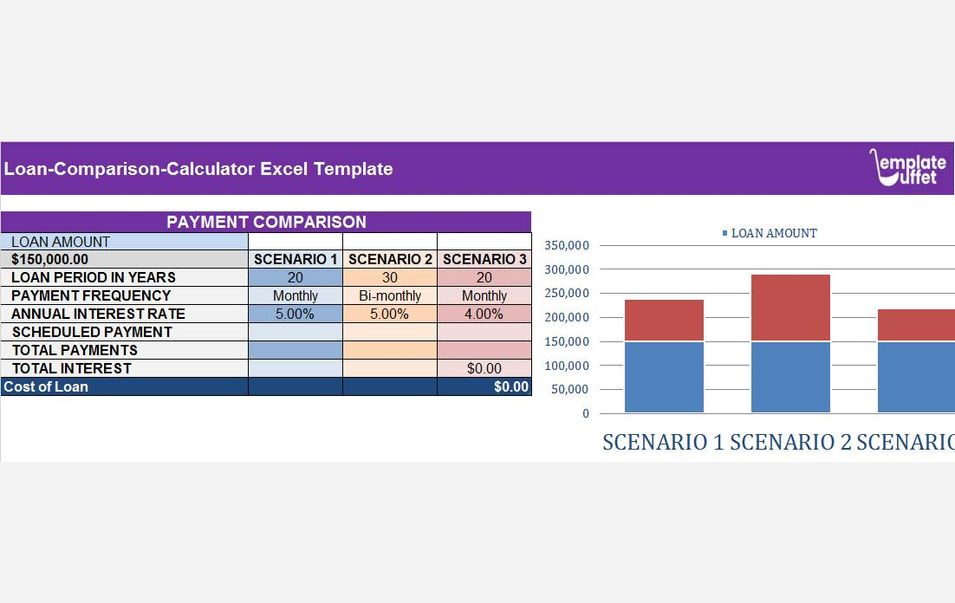
Most people grab a Loan Comparison Calculator because they want to know which loan is cheaper. That is reasonable. The problem is that they use it wrong. They type in two monthly payments, see the lower one, and call it a day. That approach will occasionally give you the wrong answer, and more often than not it will give you the wrong answer quietly, without any warning. A Loan Comparison Calculator takes two or more loan offers and runs them side by side through the same mathematical engine. It uses the principal amount, the interest rate, the loan term, how often payments compound, and whatever fees get rolled into the cost. The output is usually a table that shows monthly payment, total interest paid, total amount repaid, and the annual percentage rate. Some tools go further and generate an amortization schedule so you can see exactly how much of each payment goes toward principal versus interest over the life of the loan. The math itself is straightforward. The standard amortization formula is P = (r * PV) / (1 - (1 + r)^-n), where P is the monthly payment, r is the monthly interest rate, PV is the present value or principal, and n is the number of payments. You do not need to memorize this. You just need to know that the calculator applies it consistently across every loan you feed into it, and that consistency is what makes the comparison valid.
I ran into a situation last year where a client was comparing two refinance offers. One had a slightly lower interest rate but included lender credits that increased the effective rate once you accounted for the reduced upfront costs. The other had a higher quoted rate but transparent pricing with no credits. The basic calculator showed the first option winning on monthly payment. I dug into the amortization schedule and realized the break-even point was 47 months into a 60-month refinancing window. The client would have been locking in a worse deal without knowing it. The workaround was simply pulling the APR and total cost columns instead of fixating on the monthly payment figure.
Common Misunderstandings
APR is not the same as the interest rate. The interest rate is what the lender charges for borrowing money. APR folds in points, origination fees, and certain closing costs, then spreads them across the loan term to give you a single percentage that represents the true annual cost. A loan with a 5% interest rate and $3,000 in fees could have an APR closer to 5.4%. Another loan at 5.1% interest with no fees might come in at 5.12% APR. The second loan is cheaper even though its quoted rate looks worse. Most comparison calculators show both numbers. Read both of them. Monthly payment is a trap if you look at it in isolation. A 30-year mortgage at 6% on $250,000 produces a monthly payment around $1,499. A 15-year mortgage at 5.5% on the same amount produces a payment around $2,034. The 15-year payment is higher, but the total interest drops from roughly $290,000 to about $116,000. That is a difference of $174,000 in interest cost. A Loan Comparison Calculator will show this clearly if you scroll past the monthly payment column. Most people do not scroll. Prepayment penalties exist and they matter. Some loans charge a fee if you pay off the balance early, usually structured as a percentage of the remaining principal during the first few years. I once saw a small business owner compare two equipment loans and pick the one with the lower rate, not realizing one had a 3% prepayment penalty in year two. When they refinanced eighteen months later, the penalty cost nearly as much as the interest savings would have saved them over the remaining term. The calculator did not surface this because the penalty was buried in the fine print and not part of the standard fee fields most tools ask for.
Get the Full Details
How to Use the Tool Correctly
Enter the exact numbers from your loan offers. Do not estimate. If the disclosure document says $2,450 in closing costs, enter $2,450, not $2,500. Small differences in input create small differences in output, and those differences determine whether your choice is sound. Look at total interest and total repayment amount before you look at monthly payment. The monthly payment is what fits in your budget. The total repayment amount is what the loan actually costs you. Both matter. Budget constraints and total cost are not in conflict when you have both numbers in front of you. Check whether the calculator accounts for your compounding frequency. Some loans compound monthly. Some compound daily. Daily compounding on a high-rate loan adds meaningful cost over time. If the tool lets you select the compounding method, use that option. If it does not, flag that as a limitation and adjust mentally.
I compared a standard mortgage against a home equity line of credit last year using the calculator. The HELOC showed a lower monthly payment during the draw period because the calculator was only showing interest-only payments. The moment I switched the model to the repayment period, the payment jumped substantially. The tool did not automatically account for that phase shift. I had to manually adjust the term and payment structure to reflect the actual product. This is a known gap in many consumer-facing calculators.
Limitations You Should Know About
A Loan Comparison Calculator cannot read your mind. It cannot factor in tax implications unless you tell it to. It cannot account for your personal financial timeline unless you input it. It also struggles with variable-rate loans because the future rate is unknown. Some calculators let you model a few rate scenarios, but the output is only as good as the assumptions you provide. If you input a 1% increase on an adjustable-rate mortgage, you get a hypothetical result. It is useful for direction, not for precision. Balloon payments are another blind spot. A loan that requires a large lump sum at the end is structurally different from a fully amortizing loan, and many comparison tools either ignore the balloon or treat it as a regular payment. I have seen three separate calculators handle the same balloon payment differently. Two folded it into the monthly stream incorrectly. One excluded it entirely. None of them produced a reliable result without manual adjustment on my part. If you are comparing student loans with income-driven repayment options, the calculator will likely give you a standard repayment number that has nothing to do with your actual obligation. Income-driven repayment changes the entire math. A Loan Comparison Calculator designed for standard fixed loans cannot model that accurately. You need a specialized student loan tool or a conversation with a loan counselor.

Advanced Tactics
Generate the amortization schedule. The monthly payment table is a summary. The schedule is the detail. It shows you the principal balance after every payment, how much interest you have paid year by year, and when the balance drops below certain thresholds. This is where you catch things like the front-loaded interest problem in mortgages, where most of your early payments go toward interest rather than principal. If you are refinancing, the schedule tells you whether you are restarting the clock on a interest-heavy period and whether the new loan actually moves you forward. Test multiple scenarios. Run the comparison with the base terms, then adjust the term by five years shorter, then five years longer. See how the total cost shifts. Do the same with the interest rate, bumping it up and down by half a percent. This gives you a sense of how sensitive the loan is to changes. A loan that looks cheap at the current rate but explodes in cost if rates tick up by a quarter point is a riskier choice than a loan that stays stable under the same stress test. Consider the break-even analysis for refinancing. Calculate how many months of savings it takes to offset the closing costs. If you refinance to save $150 per month and the closing costs are $4,500, the break-even point is thirty months. If you plan to sell the house in twenty-four months, the refinance is a loss. The calculator can show you this if you include the fees. Many people skip that step and assume lower payments always mean savings.
When the Calculator Is Not Enough
Situations that require professional advice include complex debt consolidation with mixed loan types, business loans with irregular cash flows, cross-border loans involving foreign currency or different legal frameworks, and any situation where prepayment penalties, balloon payments, or variable rates play a central role. A calculator can give you a starting point, but it cannot replace a licensed financial advisor when the products are complicated or the stakes are high. Even for straightforward consumer loans, I recommend treating the calculator output as a screening tool, not a final decision tool. Verify the numbers against the official loan estimate documents. If the calculator shows a monthly payment of $1,234 and your loan document says $1,247, there is a discrepancy worth investigating before you sign anything. The best use of a Loan Comparison Calculator is to eliminate the obvious losers quickly, so you can focus your attention on the remaining options where the real decision lives. It cuts the research phase from several hours of spreadsheet work down to roughly fifteen minutes. After that, you still need to read the documents, check the fine print, and make sure the numbers on the screen match the numbers in the contract. That is where the actual work begins.